What is the market overview and industry significance of the Bio-Polyethylene (PE) Film Ethylene Derivatives Market?
Our analysis indicates that the Bio-Polyethylene (PE) Film Ethylene Derivatives Market plays a critical role in circular economy transitions. Utilizing bio-based ethanol derived from sugarcane feedstocks, players like Braskem S.A. supply drop-in resins that match conventional fossil-based polymers structurally. This sector eliminates fossil depletion impacts while meeting stringent packaging regulations enforced by the European Union.
Structural Growth Drivers and Market Restraints
The market is propelled by corporate Scope 3 emission targets and brand owner mandates for renewable content. However, high capital expenditure and feedstock price volatility tied to agricultural yields act as significant restraints. Producers like TotalEnergies SE and Dow Inc. navigate these supply chain bottlenecks by diversifying regional sourcing networks.
Emerging Trends and Growth Patterns in Bio-Polyethylene (PE) Film Ethylene Derivatives Market
A defining trend is the pivot toward metallocene-based polyethylene films offering superior puncture resistance at lower gauges. Industry leaders such as Nova Chemicals and Borealis AG are optimizing catalyst technologies to enhance film down-gauging, directly addressing consumer goods and retail demands for sustainable, lightweight flexible packaging solutions.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic initially disrupted supply chains and delayed green packaging investments due to lower virgin resin costs. Nevertheless, the post-COVID recovery accelerated exponentially as health, safety, and hygiene priorities drove massive demand for medical-grade film derivatives. Companies like Sealed Air Corporation rebounded swiftly by leveraging localized compounding plants.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately high, dominated by petrochemical conglomerates integrating green chemistry. Saudi Basic Industries Corporation (SABIC) and LyondellBasell Industries utilize existing crackers for co-processing bio-feedstocks. Strategic M&A activity remains intense as multinational converters acquire specialized bio-compounders to secure proprietary green IP portfolios.
Executive Summary: Bio-Polyethylene (PE) Film Ethylene Derivatives Market
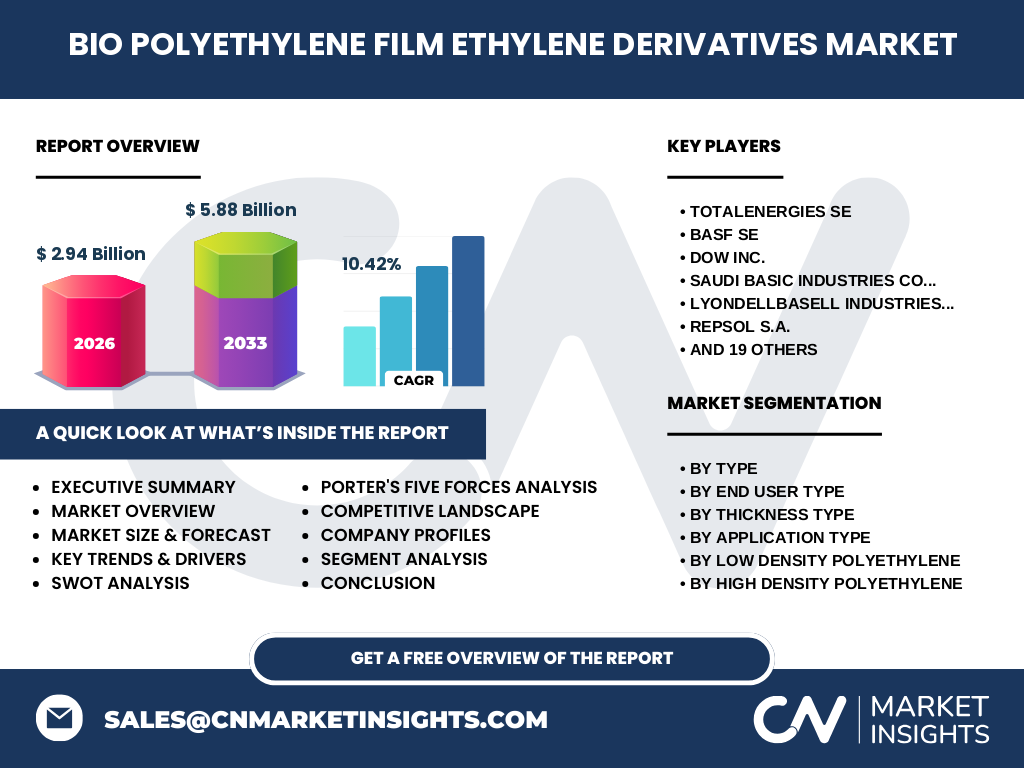
Valued at 2.94 Billion in 2026, the global market is projected to reach 5.88 Billion by 2033, expanding at a robust 10.42% CAGR. This exponential trajectory underscores a structural decoupling from fossil resource dependency, fueled by stringent environmental directives and aggressive retail adoption.
Market Forecast from 2027 to 2033
Our forecast models a stellar 10.42% CAGR, doubling market valuation from 2.94 Billion in 2026 to 5.88 Billion by 2033. This growth is underpinned by capacity expansions from INEOS Group Holdings S.A. and rising regulatory penalties on non-renewable single-use plastic films across North America and Europe.
Segmentation Analysis by Type, End User, Thickness, and Application
The market bifurcates into High Density Polyethylene (covering blow molded, injection molded, and extrusion grade films) and Low Density Polyethylene (encompassing conventional and metallocene-based variants). End-user verticals span food and beverage, healthcare, and retail, utilizing thin, medium, and thick gauges across packaging, agriculture, and consumer goods applications.
Regional Market Analysis and Geographic Performance
Europe commands the highest revenue share due to the Single-Use Plastics Directive, while Asia-Pacific exhibits the fastest adoption rate. Logistics hubs near major ports like Rotterdam and Singapore facilitate vital trade flows of bio-ethanol and finished ethylene derivative films produced by regional innovators like PTT Global Chemical Public Company Limited.
In-Depth Regional Review
Latin America benefits from abundant sugarcane feedstock availability, enabling cost-advantaged production by regional titans. Concurrently, North American markets focus on post-consumer recycled integration, where companies like Berry Global Inc. and Amcor plc deploy advanced extrusion lines to meet localized sustainability compliance standards.
Company Profiles and Strategic Positioning
Industry participants such as Mitsui Chemicals Inc., Toray Industries Inc., and Neste Oyj focus on high-margin specialty film niches. Meanwhile, converters like Mondi plc, Huhtamäki Oyj, and UFlex Limited leverage strategic supplier agreements to ensure uninterrupted access to certified green PE resins.
Porter's Five Forces Analysis
Bargaining power of suppliers is moderate-to-high given proprietary bio-ethanol sourcing limitations. Threat of substitutes remains low due to unique mechanical properties of PE films, while competitive rivalry is fierce as petrochemical giants and specialized green chemical startups race for market share.
SWOT Analysis of the Bio-Polyethylene (PE) Film Ethylene Derivatives Market
Strengths include identical performance to fossil PE and excellent carbon-negative footprints. Weaknesses involve higher production costs than traditional resins. Opportunities lie in agricultural mulch films and premium retail packaging, while threats stem from regulatory pushback on land-use changes for feedstock cultivation.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with agricultural sugarcane or corn cultivation, proceeding through fermentation into bio-ethanol, catalytic dehydration into bio-ethylene, and polymerization into PE resin. Converters then extrude these into films for end-users managed by packaging giants like Constantia Flexibles and Coveris Holdings S.A.
Investment Insights and High-Potential Areas
High-potential investment pockets center on metallocene-based LDPE films for high-barrier food packaging. Venture capital and corporate funds target early-stage biopolymer innovators such as Green Dot Bioplastics LLC and FKuR Kunststoff GmbH to capture proprietary compounding breakthroughs.
Conclusion and Key Takeaways
The Bio-Polyethylene (PE) Film Ethylene Derivatives Market transitions from a niche alternative to a mainstream industrial imperative. Reaching 5.88 Billion by 2033 at a 10.42% CAGR, the sector rewards stakeholders who secure resilient feedstock partnerships and advanced extrusion technologies.
Research Methodology for Baseline Estimates
Baseline estimates are triangulated by combining customs trade registry data, primary stakeholder interviews with C-suite executives at Versalis S.p.A. and Innovia Films Limited, and secondary macroeconomic indicators from chemical trade associations and regional energy boards.
Scope of the Report and Coverage Parameters
This report covers global revenue estimations from 2026 to 2033, breaking down market performance by density type, thickness, end-user vertical, and geographic region. Exclusions involve non-ethylene biopolymers such as PLA and PHA unless used in direct co-extrusion blends with bio-PE.
Recent Developments, Partnerships, and Strategic Moves
Recent milestones feature multi-year off-take agreements between polymer producers and global converters. For instance, strategic partnerships forged by Basf SE and Billerud highlight an industry-wide push to commercialize drop-in bio-based barrier films for demanding pharmaceutical and food shelf-life applications.