What is the scope and market size of the Neurodiverse Workforce Productivity Tools Market?
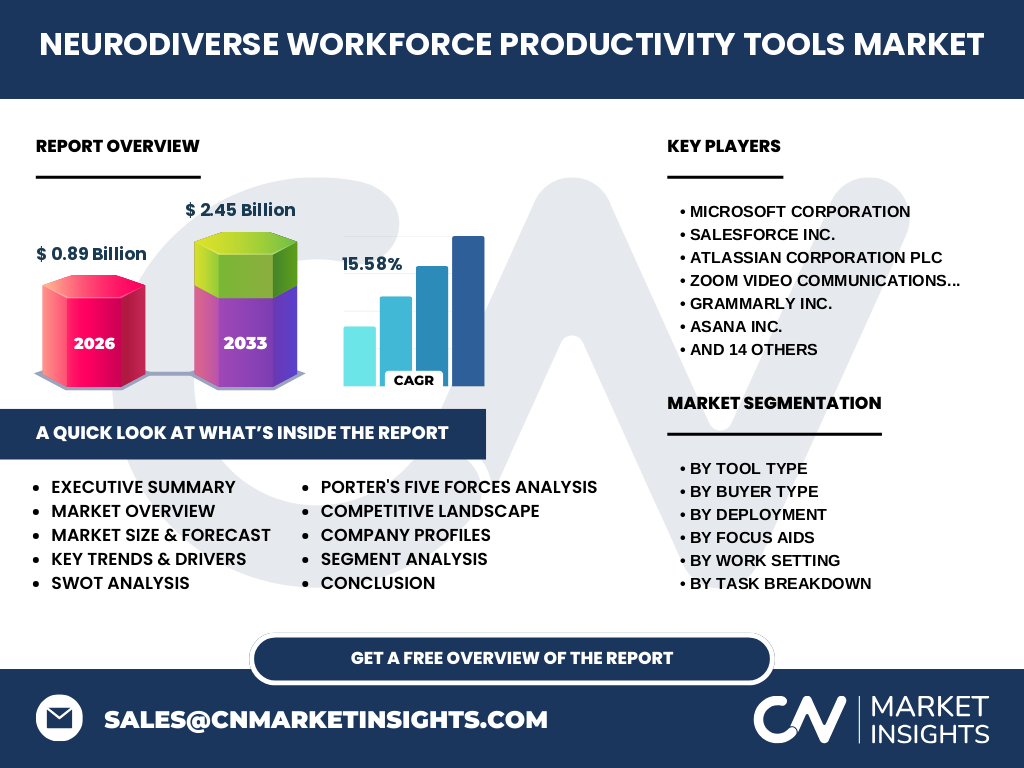
Our analysis indicates that the Neurodiverse Workforce Productivity Tools Market is valued at 0.89 Billion in 2026, encompassing specialized software designed for cognitive accessibility under frameworks like the Americans with Disabilities Act (ADA) and European Accessibility Act.
Key market drivers, restraints, challenges, and opportunities shaping the sector
Rapid corporate adoption of ESG mandates drives the market, whereas legacy IT infrastructure and strict data privacy regulations such as GDPR present deployment hurdles, creating immense opportunities for compliant SaaS solutions.
Emerging trends and growth patterns in the industry
The shift toward neuro-inclusive hybrid offices accelerates demand for AI-driven assistive technologies, with enterprises increasingly prioritizing cognitive ergonomics alongside physical workplace safety standards.
How did the COVID-19 pandemic affect market dynamics and recovery?
The sudden shift to remote work during the pandemic exposed deep accessibility gaps, forcing organizations to fast-track digital accommodation budgets and permanently transforming the recovery trajectory of assistive software.
Competitive landscape and strategic market concentration
The market features a mix of tech giants like Microsoft Corporation and specialized innovators such as Otter.ai Inc. and Grammarly Inc., driving consolidation through strategic feature integrations.
Executive summary of key findings for the Neurodiverse Workforce Productivity Tools Market industry trends
Driven by a robust 15.58% CAGR, the market will surge from 0.89 Billion in 2026 to 2.45 Billion by 2033, reshaping modern enterprise productivity standards.
Market forecast from 2027 to 2033
Projected growth will expand the market from 2027 to 2033 to reach 2.45 Billion by the end of the forecast period, fueled by mainstream acceptance of neurodiversity-affirming employment practices.
Segmentation analysis across core product and buyer categories
Segments span by tool type (Writing Support, Meeting Capture, Task Breakdown, Focus Aids, Reading Support), buyer type (Large Enterprises, Mid Market, Small And Medium Sized Businesses, Public Sector), deployment (Cloud SaaS, Desktop, Browser Add Ons, Mobile), and work setting.
Regional market analysis and geographic distribution performance
North America leads adoption due to stringent EEOC guidelines, while Europe demonstrates rapid growth steered by the European Accessibility Act, outperforming emerging regions in public sector procurement.
In-depth regional review of key markets
North American enterprises dominate early deployment of advanced meeting capture and focus aids, whereas European markets prioritize standardized reading and writing support tools to comply with regional labor laws.
Company profiles and strategic positioning of leading market players
Industry leaders leverage distinct advantages: Salesforce Inc. and Atlassian Corporation Plc embed accessibility natively, while niche providers like Tiimo ApS and Brain in Hand Ltd target executive functioning challenges.
Porter's Five Forces analysis of competitive pressures
Competitive rivalry is intense among established SaaS platforms, while supplier power remains low due to open-source AI models, though buyer bargaining power is moderate given the availability of freemium accessibility extensions.
SWOT analysis for the Neurodiverse Workforce Productivity Tools Market
Strengths include high workplace ROI, weaknesses involve fragmented compliance standards, opportunities lie in deep AI integrations by vendors like Glean Technologies Inc., and threats stem from generic productivity tool encroachment.
Value chain analysis from development to end-user deployment
Value flows from cognitive science research and natural language processing raw data to software developers, channeled through enterprise IT procurement and ultimately empowering end-users in corporate and educational settings.
Investment insights and high-potential areas for strategic allocation
Investors should target cloud-native platforms specializing in automated task breakdown and distraction-blocking focus aids, as these categories yield the highest employee retention and productivity metrics in hybrid environments.
Conclusion and key takeaways for stakeholders
Achieving a projected 2.45 Billion valuation by 2033 highlights that neurodiverse productivity solutions have transitioned from niche accommodations to essential enterprise infrastructure.
Research methodology used to triangulate baseline estimates
Our proprietary research model triangulates trade registry data, primary executive interviews with HR and D&I leaders, and macroeconomic labor statistics to ensure precise market sizing.
Scope of the report and coverage parameters
This report covers global deployment across corporate, educational, government, and healthcare end-user organization types, excluding consumer-only wellness apps lacking workplace integration features.
Recent developments in product launches and strategic partnerships
Recent market activity features strategic acquisitions and feature rollouts by innovators like Speechify Inc. and Notion Labs Inc., aiming to bridge cognitive accessibility gaps across enterprise collaboration suites.