Market overview and scope of the Specimen Sorting Systems Market
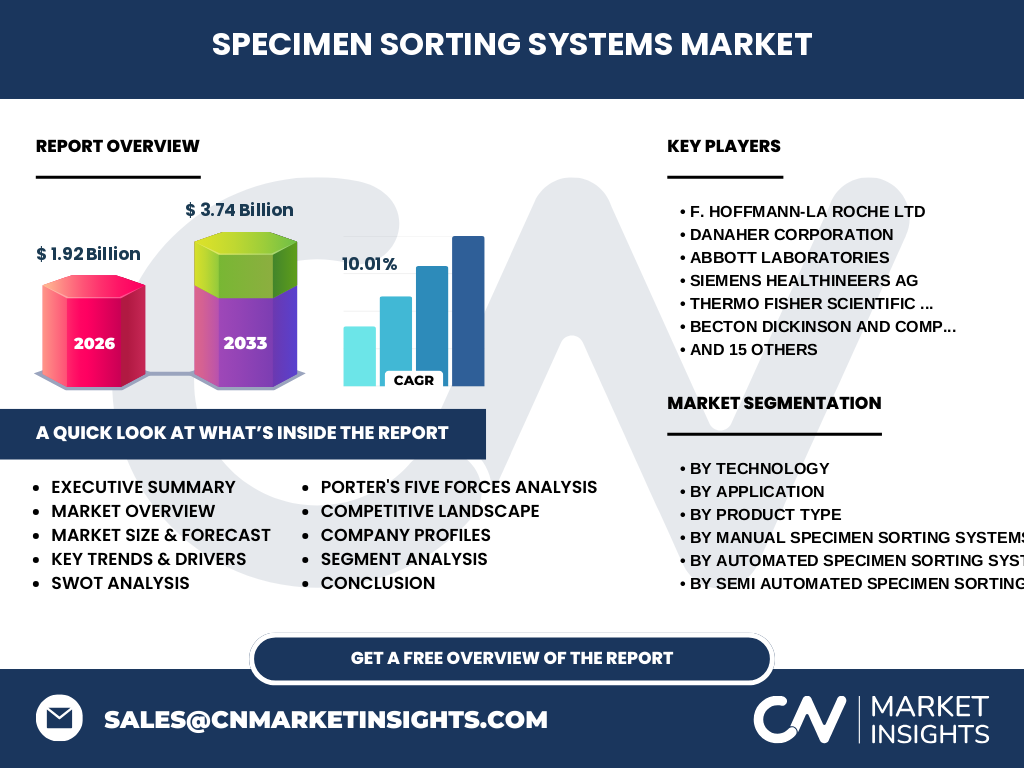
Our analysis indicates the Specimen Sorting Systems Market size reached $1.92 Billion in 2026. This sector encompasses automated, semi-automated, and manual instruments designed to streamline clinical and research laboratory workflows, ensuring high-integrity sample routing for diagnostics.
Structural Growth Drivers and Market Restraints
The market is propelled by a CAGR of 10.01%, driven by rising diagnostic test volumes and strict regulatory frameworks imposed by bodies like the FDA and EMA. However, high capital expenditures for automated platforms remain a primary market restraint.
The Shift Toward AI and Robotic Integration
Emerging trends highlight a rapid migration toward Artificial Intelligence Based Sorting Systems and Robotic Sorting Systems. These advanced technologies reduce human error and handle complex sample matrices with unprecedented precision in high-throughput environments.
COVID-19 Impact Analysis and Pandemic Recovery
The pandemic severely strained laboratory operations, causing massive supply chain bottlenecks for raw materials. Consequently, laboratories accelerated investments in resilient automation to manage sudden surges in diagnostic testing demand without compromising turnaround times.
Competitive Benchmarking and Industry Concentration
The competitive landscape features industry titans such as F. Hoffmann-La Roche Ltd, Danaher Corporation, and Abbott Laboratories. These players maintain dominance through integrated modular automation and expansive global distribution networks.
Executive Summary of the Specimen Sorting Systems Market
Valued at $1.92 Billion in 2026, the market is on a robust trajectory to hit $3.74 Billion by 2033. Strategic partnerships and proprietary AI integrations are redefining operational benchmarks across major commercial laboratories worldwide.
Market Forecast and Valuation Trajectory from 2027 to 2033
Our research forecasts the market will expand from its 2026 baseline to reach $3.74 Billion by 2033. This expansion is sustained by continuous technological refreshes and expanding healthcare access in emerging economies.
Comprehensive Segmentation Analysis
The market segments by technology into barcode, RFID, AI, and robotics. Application categories cover Clinical Laboratories, Research Laboratories, Blood Banks, and Hospitals, while product types include automated, semi-automated, and manual systems.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America leading due to advanced healthcare infrastructure, followed closely by Europe. Asia-Pacific exhibits the fastest growth due to expanding hospital modernization initiatives and rising diagnostic outsourcing.
In-Depth Regional Review of Key Markets
North American laboratories prioritize seamless IT integration and high throughput. Meanwhile, European facilities navigate stringent CE-IVDR regulations, favoring certified modular systems from established regional vendors like Tecan Group Ltd. and Sarstedt AG & Co. KG.
Strategic Company Profiles and Market Positioning
Companies like Siemens Healthineers AG and Sysmex Corporation focus on scalable track-based automation. Meanwhile, specialized innovators like Inpeco SA and Copan Diagnostics Inc. carve out niches with proprietary pre-analytical middleware and specimen management solutions.
Porter's Five Forces Competitive Assessment
Bargaining power of buyers is moderate to high due to consolidated hospital network purchasing. Threat of new entrants remains low given high switching costs, strict regulatory compliance, and proprietary intellectual property held by incumbents.
SWOT Analysis of the Industry Ecosystem
Key strengths include high throughput and minimal manual contamination risks. However, vulnerabilities persist regarding cyber-vulnerabilities in networked lab software, alongside untapped opportunities in decentralized point-of-care sorting applications.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing specialized polymers and micro-electronics, flowing through original equipment manufacturers, and culminating in clinical laboratories and hospitals utilizing automated sorting units for patient diagnostics.
Investment Insights and Strategic Recommendations
Stakeholders should direct capital toward artificial intelligence integration and flexible robotic arms. These capabilities yield higher operating margins and better position vendors to serve high-volume reference laboratories.
Conclusion and Critical Industry Takeaways
The Specimen Sorting Systems Market represents a high-growth sector set to achieve $3.74 Billion by 2033. Automation and AI will remain the definitive catalysts for future competitive differentiation.
Robust Research Methodology and Data Triangulation
Baseline estimates are triangulated by combining proprietary trade registry data, extensive primary interviews with C-suite laboratory executives, and secondary macroeconomic indicators from global health organizations.
Scope of the Report and Analytical Parameters
This report covers global revenue performance, segment sizing, and regional trends from 2026 to 2033. Exclusions apply to custom bespoke laboratory prototypes not commercially deployed in clinical or research settings.
Recent Developments and Strategic Industry Moves
Recent market activity is characterized by major product launches combining AI-driven sorting with automated nucleic acid extraction. Strategic acquisitions by conglomerates like Thermo Fisher Scientific Inc. underscore a race to consolidate lab automation portfolios.