What is the Single-Aisle Aircraft Market scope and industry significance?
Our analysis indicates that the Single-Aisle Aircraft Market market size anchors commercial aviation, projected to reach $93.42 Billion by 2026. This sector encompasses narrow-body platforms crucial for short-to-medium-haul networks managed by regulatory bodies like the FAA and EASA, driving global connectivity.
Structural Growth Drivers and Restraints in the Single-Aisle Aircraft Market
The Single-Aisle Aircraft Market industry trends reveal robust expansion fueled by low-cost carrier fleet modernization and passenger demand. However, supply chain bottlenecks for raw materials like carbon fiber composites and titanium constrain output, alongside stringent environmental certifications by aviation authorities.
Emerging Trends and Growth Patterns Shaping the Sector
Industry dynamics show an accelerated shift toward sustainable aviation fuels (SAF) compatibility and ultra-efficient turbofan engines. Innovators like GE Aerospace Technologies and Safran Aircraft Engines are leading developments to drastically reduce carbon footprints across high-density routes.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
The pandemic severely disrupted baseline operations, yet the Single-Aisle Aircraft Market demonstrated exceptional resilience. Domestic travel recovery outpaced long-haul routes, pushing carriers to prioritize agile narrow-body models over wide-body assets to mitigate financial exposure.
Competitive Benchmarking and Strategic Dynamics
A duopoly dominated by Airbus SE and The Boeing Company characterizes the landscape, complemented by tier-one suppliers like Honeywell International Inc. and Spirit AeroSystems Inc. Market concentration remains high, forcing competitors to leverage advanced digital manufacturing and lightweight component innovations.
Executive Summary of the Single-Aisle Aircraft Market Analysis
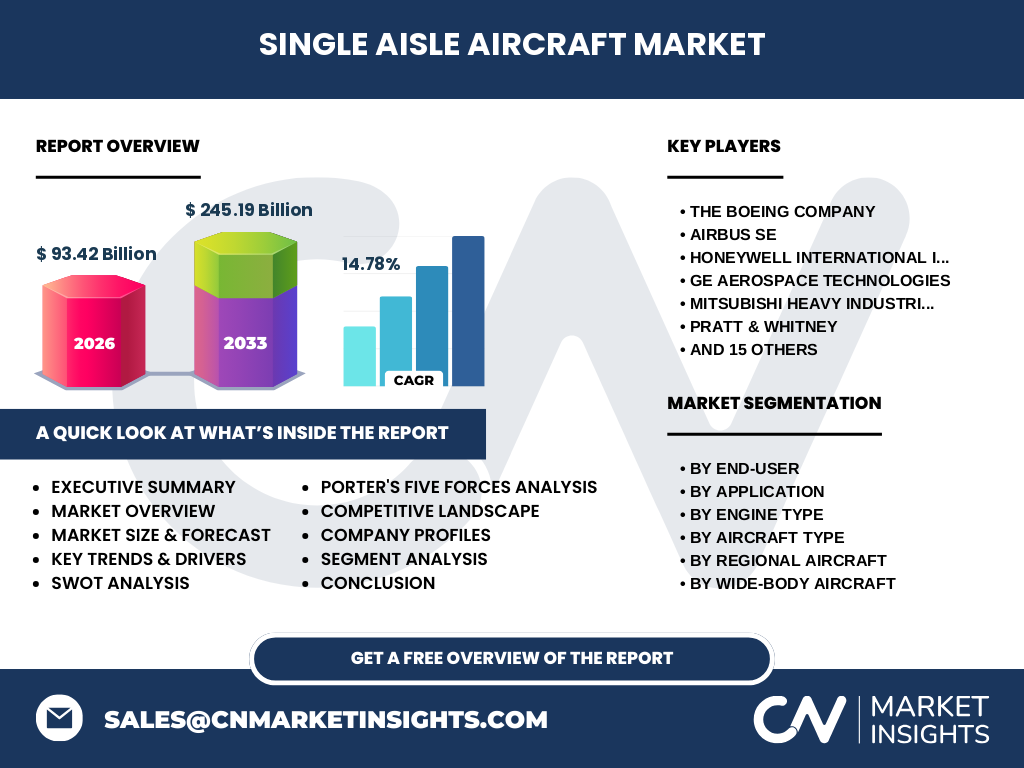
Our research establishes a commanding valuation trajectory, forecasting the market to surge from $93.42 Billion in 2026 to $245.19 Billion by 2033 at a CAGR of 14.78%. This expansion is heavily anchored by low-cost carrier network demands and continuous technological enhancements.
Long-Term Market Forecast from 2027 to 2033
Driven by aggressive fleet expansion across emerging economies, our proprietary models project the Single-Aisle Aircraft Market to achieve remarkable acceleration through 2033, reaching $245.19 Billion. The sustained 14.78% CAGR underscores strong investor confidence in narrow-body efficiency.
Comprehensive Segmentation Analysis
The sector breaks down across multiple vectors: By End-User (Full-Service Carriers, Low-Cost Carriers, Aircraft Leasing Companies), By Application (Passenger Transport, Cargo Conversion, Charter Operations), By Engine Type (Turbofan Engine Aircraft, Turboprop Engine Aircraft), and By Aircraft Type (Narrow-Body, Wide-Body, Regional), featuring specialized classes like Short Haul Narrow Body and Long Haul Wide Body.
Regional Market Distribution and Performance Overview
Geographic analysis highlights Asia-Pacific and North America as primary demand hubs, driven by massive urbanization and sprawling domestic flight corridors. Localized infrastructure constraints at major cargo hubs continue to influence regional fleet deployment strategies significantly.
In-Depth Regional Review of High-Growth Geographies
Asia-Pacific leads volume expansion due to swelling middle-class populations and aggressive low-cost carrier proliferation, while North American airlines focus heavily on fleet renewal and cabin interior retrofits to meet strict environmental compliance mandates.
Company Profiles and Strategic Positioning
Industry leaders such as Embraer S.A., Commercial Aircraft Corporation of China Ltd. (COMAC), and Bombardier-linked suppliers maintain distinct competitive edges. Their strategic investments in aerodynamic efficiency and digital avionics position them to capture substantial market share amidst shifting global trade routes.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate-to-high given the dominant duopoly, while supplier power is constrained by specialized aerospace manufacturing requirements. The threat of new entrants is remarkably low due to prohibitive capital expenditure, strict certification hurdles, and complex IP barriers.
SWOT Analysis of the Single-Aisle Aircraft Industry
Strengths include unmatched operational flexibility and fuel economy; weaknesses involve acute vulnerability to raw material price volatility. Opportunities lie in aggressive fleet upgrades across developing markets, whereas threats encompass geopolitical trade friction and tightening emissions regulations.
Value Chain Analysis from Raw Materials to End-Users
The value stream initiates with specialty metallurgy and composite material suppliers, transitioning to aerostructures manufacturers like FACC AG and Aernnova Aerospace S.A., culminating in final assembly by OEMs and delivery to leasing firms and commercial airlines.
Investment Insights and High-Potential Areas
Investors should target aftermarket maintenance providers, digital predictive maintenance platforms, and next-generation hybrid-electric propulsion developers. These high-margin niches offer optimal exposure to the sector's 14.78% CAGR expansion without direct exposure to primary assembly bottleneck risks.
Conclusion and Strategic Takeaways
The Single-Aisle Aircraft Market market analysis proves that narrow-body dominance will only intensify. Stakeholders must align their capital allocation with sustainability initiatives, advanced composite fabrication, and digital supply chain visibility to secure long-term profitability.
Research Methodology and Baseline Triangulation
Our estimates are triangulated by synthesizing proprietary trade registry data, primary executive interviews with C-suite leaders at Pratt & Whitney and Thales S.A., and secondary macroeconomic indicators, ensuring a high fidelity market sizing foundation.
Scope of the Report and Operational Limitations
This report covers global commercial narrow-body, regional, and wide-body platforms within passenger, cargo, and charter configurations from 2026 through 2033. Excluded from this specific analysis are military transport fleets and general aviation private jets under four seats.
Recent Developments, Partnerships, and Strategic Moves
Recent industry milestones include major engine delivery contracts secured by MTU Aero Engines AG, modernization partnerships involving Hong Kong Aircraft Engineering Company Limited, and aggressive production ramp-ups by PJSC Irkut Corporation, signaling robust ongoing industrial momentum.