What is the market overview and industry significance of the Programmable Ammunition Market?
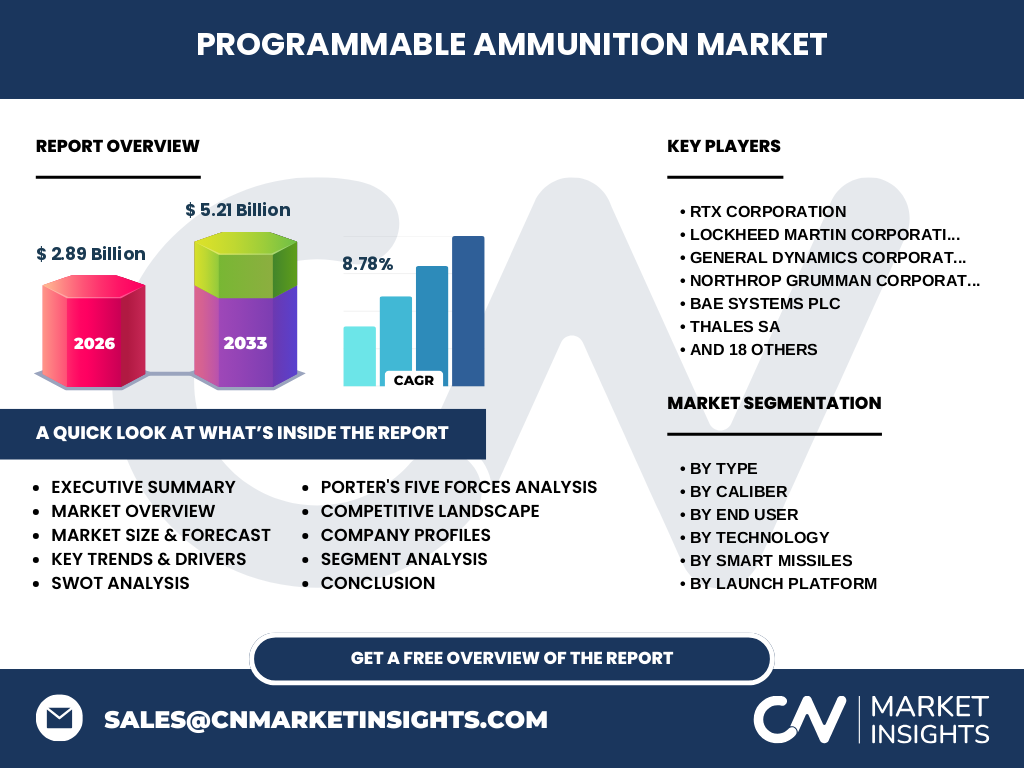
Our analysis indicates that the Programmable Ammunition Market reaches a valuation of 2.89 Billion in 2026. This sector encompasses advanced guided munitions, smart missiles, and intelligent shells designed for modern net-centric warfare. Industry significance lies in minimizing collateral damage while maximizing lethality through precision guidance technologies like electronic fuzes.
Key market drivers, restraints, challenges, and opportunities shaping the Programmable Ammunition Market
The market is driven by rising defense budgets and the tactical need for urban warfare precision. Restraints include strict ITAR export controls and high R&D costs for rocket motors and tungsten heavy alloys. Opportunities abound in miniaturizing inductive programming modules for infantry deployment.
Emerging trends and growth patterns in the Programmable Ammunition Market
Emerging trends highlight a major pivot toward multi-option programmable mortar rounds and AI-enabled course-correcting artillery shells. Defense agencies are heavily investing in radio frequency (RF) guidance to counter electronic jamming, reshaping acquisition priorities for prime contractors.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted global defense supply chains, delaying rare earth mineral shipments and testing propellant manufacturing facilities. Recovery trajectories accelerated rapidly post-2021, fueled by emergency defense supplemental fundings and national stockpiling mandates across NATO allies.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, dominated by prime contractors such as RTX Corporation, Lockheed Martin Corporation, and Northrop Grumman Corporation. Strategic dynamics involve aggressive vertical integration, particularly in acquiring micro-electronics and sensor-fuzed sub-assembly manufacturers to secure proprietary missile pathways.
Executive summary of the Programmable Ammunition Market report
This comprehensive executive review projects the Programmable Ammunition Market to surge from 2.89 Billion in 2026 to 5.21 Billion by 2033, achieving a robust CAGR of 8.78%. Growth is heavily anchored in the adoption of smart missiles and electronic fuzes by special operations forces.
Market forecast from 2027 to 2033
Our predictive models indicate sustained expansion, forecasting the market to reach 5.21 Billion by 2033 at a CAGR of 8.78%. This trajectory is sustained by multi-year procurement contracts for surface-to-air and anti-tank guided missiles across Eastern European and Indo-Pacific theaters.
Segmentation analysis across product types, calibers, and end-users
Segmentation is categorized by Type (Guided Munitions, Smart Missiles, Intelligent Shells, Programmable Mortars), Caliber (Small, Medium, Large), Technology (Electronic Fuze, Inductive Programming, RF), and End User (Defense, Special Operations, Border Security). Intelligent shells represent a critical high-margin segment for artillery modernization.
Regional market analysis and geographic performance
Geographic distribution heavily favors North America due to large-scale Pentagon modernization initiatives. Meanwhile, the Asia-Pacific region exhibits the fastest regional growth, propelled by maritime territorial disputes and surging ammunition stockpiling by India, South Korea, and Taiwan.
In-depth regional review of key operational theaters
In Europe, cross-border defense cooperation via MBDA and Rheinmetall AG drives joint procurement of dual-mode guided bombs. In the Middle East, high operational tempos sustain continuous demand for point-detonation mortar rounds and tactical missile systems.
Company profiles and strategic positioning of leading market players
Industry leaders like BAE Systems plc, Thales SA, and Leonardo SpA focus on sovereign technological capabilities. Specialized players such as Elbit Systems Ltd. and Rheinmetall AG leverage localized manufacturing to secure regional artillery and mortar modernization contracts.
Porter's Five Forces analysis of the competitive landscape
The threat of new entrants is exceptionally low due to stringent defense qualification hurdles, heavy capital expenditure requirements, and IP barriers. Bargaining power of buyers is moderate to high, dominated by national ministries of defense exercising strict budgetary oversight.
SWOT analysis of the Programmable Ammunition Market
Strengths include unmatched battlefield precision and lethality. Weaknesses involve lengthy compliance cycles. Opportunities lie in counter-drone electronic fuze applications. Threats stem from geopolitical supply chain bottlenecks for energetic materials and microcontrollers.
Value chain analysis from raw materials to end-users
The value chain starts with raw material suppliers providing energetic compounds, titanium, and rare earths. Mid-stream Tier-1 contractors handle guidance kit integration and rocket motor casting, while final distribution flows through government depots to front-line defense forces.
Investment insights and high-potential areas
High-potential investment areas center on anti-jamming RF guidance components and low-cost course-correcting artillery kits. Venture capital and private equity are increasingly targeting defense-tech startups specializing in inductive programming architectures.
Conclusion and key strategic takeaways
The Programmable Ammunition Market represents a vital pillar of modern military transformation. With a projected value of 5.21 Billion by 2033, stakeholders must prioritize software-defined fuzing and scalable manufacturing partnerships to capture long-term defense procurement value.
Research methodology and baseline estimation techniques
Our baseline estimates are rigorously triangulated by combining defense trade registry data, primary stakeholder interviews with procurement directors, and secondary macroeconomic indicators such as national defense budget allocations and export licensing data.
Scope of the report, coverage parameters, and limitations
This report covers global deployment trends across ground, naval, and aerial launch platforms from 2026 to 2033. Limitations include restricted access to classified black-budget defense programs and proprietary cost structures of state-owned munitions enterprises.
Recent developments, company announcements, and strategic moves
Recent milestones include joint ventures between Kongsberg Gruppen and local defense primes for missile integration, alongside significant production facility expansions by Nammo AS and Poongsan Corporation to meet surging European and Asian artillery demand.