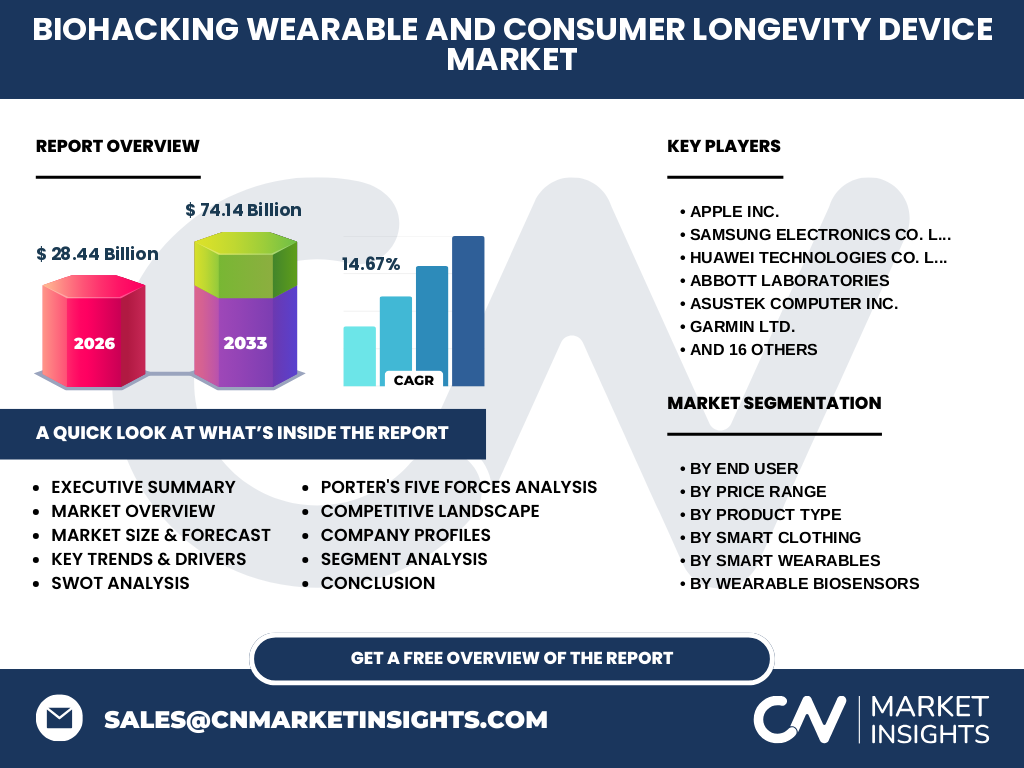
Market overview of the Biohacking Wearable And Consumer Longevity Device Market
Our analysis indicates that the Biohacking Wearable And Consumer Longevity Device Market stands at $28.44 Billion in 2026. This dynamic sector encompasses advanced hardware and software designed to optimize human biological performance, cellular health, and lifespan extension through continuous physiological monitoring.
What are the primary drivers and restraints shaping the Biohacking Wearable And Consumer Longevity Device Market?
Growth is propelled by rising consumer demand for preventative healthcare and proactive biological optimization. However, strict medical device regulations from agencies like the FDA and complex raw material supply chains for medical-grade silicones and rare-earth metals act as primary market restraints.
Emerging trends and growth patterns in the Biohacking Wearable And Consumer Longevity Device Market
The shift toward continuous biomarker tracking is accelerating. Innovations in non-invasive optical sensors and continuous glucose monitoring are transforming standard fitness trackers into sophisticated longevity tools, favoring agile innovators over legacy hardware manufacturers.
How did the COVID-19 pandemic impact the Biohacking Wearable And Consumer Longevity Device Market?
The pandemic dramatically shifted consumer mindsets toward decentralized health monitoring and proactive immune defense. Remote health tracking adoption surged, establishing a permanent baseline for at-home biological assessment that continues to drive post-pandemic market recovery.
Competitive benchmarking and strategic dynamics
The market features intense competition between tech giants like Apple Inc. and specialized longevity disruptors like Oura Health Oy and WHOOP Inc. Market concentration is high in smart wearables, forcing smaller entrants to carve out niches in neurostimulation and metabolic monitoring.
Executive Summary of the Biohacking Wearable And Consumer Longevity Device Market
Driven by a robust 14.67% CAGR, the Biohacking Wearable And Consumer Longevity Device Market is projected to expand from $28.44 Billion in 2026 to $74.14 Billion by 2033. Strategic investments in algorithmic precision and proprietary bio-sensing materials will dictate future market leadership.
Market forecast from 2027 to 2033
Based on our research, the sector will experience exponential valuation expansion, scaling from 2027 through 2033 to reach $74.14 Billion. This trajectory reflects widespread mainstream adoption of longevity interventions and institutional integration via corporate wellness programs.
Segmentation analysis by product type, end user, and distribution channel
The ecosystem breaks down across end users like Fitness Enthusiasts and Healthcare And Wellness Centers, price tiers ranging from Premium to Economy, and diverse product categories including Smart Wearables, Wearable Biosensors, and Neurostimulation Devices distributed via direct-to-consumer online channels and specialty longevity clinics.
Regional market analysis and geographic performance
North America currently dominates the revenue share due to high disposable incomes and early adopter density. Meanwhile, the Asia-Pacific region exhibits the fastest regional growth rate, propelled by expanding digital infrastructure and manufacturing hubs in South Korea and China.
In-depth regional review of key geographic territories
North America remains anchored by stringent FDA compliance requirements and a mature venture capital ecosystem backing startups like Levels Health Inc. Conversely, European markets face stricter GDPR compliance regarding biometric data privacy, shaping localized product deployment.
Company profiles and strategic positioning of leading market participants
Industry leaders deploy distinct playbooks: Apple Inc. leverages ecosystem lock-in, whereas specialized players like Abbott Laboratories, DexCom Inc., and Withings focus on medical-grade precision and clinical-tier metabolic health tracking for dedicated longevity seekers.
Porter's Five Forces analysis of the competitive environment
Competitive rivalry is intense, yet supplier power remains moderate due to specialized component manufacturing for optical sensors. High switching costs driven by proprietary health data algorithms effectively protect established brand ecosystems against new market entrants.
SWOT analysis highlighting strategic strengths and vulnerabilities
Key strengths lie in advanced biometric sensor accuracy and expanding lifestyle integration. However, data privacy vulnerabilities and high hardware price points represent notable weaknesses, while emerging integration with AI diagnostics offers massive strategic opportunities.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material sourcing—including piezoelectric crystals and medical-grade polymers—proceeds through precision microchip fabrication, and culminates in software-as-a-service (SaaS) subscription models delivered directly to consumers and longevity clinics.
Investment insights and high-potential areas for capital deployment
High-potential capital deployment areas include advanced Wearable Biosensors capable of real-time sweat analysis and non-invasive blood oxygen monitoring. Investors should prioritize firms with proprietary biometric algorithms over pure commodity hardware manufacturers.
Conclusion and key strategic takeaways for industry stakeholders
The path to market dominance requires balancing consumer-grade aesthetic appeal with clinical-grade accuracy. Organizations that successfully bridge lifestyle biohacking with validated health outcomes will capture disproportionate value as the sector approaches $74.14 Billion.
Research methodology for baseline estimations and triangulation
Our research methodology triangulates data by synthesizing proprietary trade registry metrics, primary stakeholder interviews with key executives at WHOOP Inc. and Oura Health Oy, and secondary macroeconomic indicators regarding global healthcare expenditure.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market sizing, granular segmentations across nine product categories, and regional analyses through 2033. Limitations include inherent regulatory shifts across international borders and rapid technological obsolescence cycles typical of consumer electronics.
Recent developments, strategic partnerships, and product launches
Recent market velocity is underscored by strategic partnerships between consumer device makers and clinical research organizations. Innovations from players like Neurable Inc. and Apollo Neuroscience Inc. highlight a decisive industry pivot toward cognitive enhancement and stress-relief wearables.