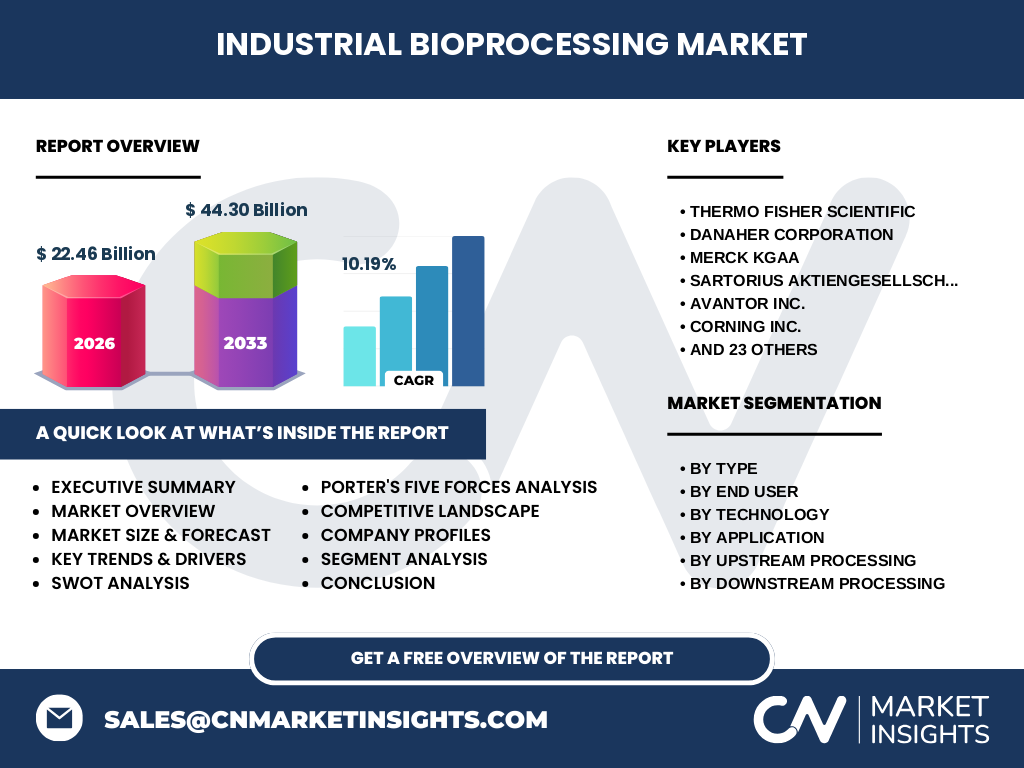
Market overview of the Industrial Bioprocessing Market
Our analysis indicates that the Industrial Bioprocessing Market encompasses critical technological frameworks utilizing biological systems for commercial manufacturing. Valued at 22.46 Billion in 2026, the sector drives innovations across upstream and downstream workflows, heavily influencing global pharmaceutical, enzymatic, and biofuel output under stringent regulatory standards enforced by bodies like the US FDA and EMA.
Structural Growth Drivers and Market Restraints
The market is propelled by a 10.19% CAGR, fueled by rising demand for biologic therapeutics and sustainable industrial enzymes. However, high capital expenditures for advanced bioreactors and complex supply chain bottlenecks for single-use consumables and filtration membranes present notable operational restraints for emerging manufacturers globally.
Emerging Trends and Paradigm Shifts
The industry is witnessing an aggressive pivot toward single-use technologies and automated process analytical technologies. Companies are rapidly adopting advanced biomass monitoring systems and continuous manufacturing architectures to reduce cross-contamination risks, enhance batch consistency, and accelerate time-to-market for complex therapeutic modalities.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted global supply chains for critical cell culture media and chromatography resins, yet it ultimately acted as a major catalyst for the Industrial Bioprocessing Market. Accelerated vaccine development programs forced rapid scaling of flexible single-use assemblies, permanently reshaping the sector's operational resilience.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, anchored by industry powerhouses such as Thermo Fisher Scientific, Danaher Corporation, and Merck KGaA. These tier-one players leverage expansive portfolios spanning bioreactors and purification resins to secure dominant positions, continuously executing strategic acquisitions to absorb niche filtration and single-use innovation.
Executive Summary of Key Findings
Our comprehensive research projects the Industrial Bioprocessing Market to reach 44.30 Billion by 2033, expanding at a robust 10.19% CAGR. Upstream processing and fermentation technologies remain the primary value pockets, heavily driven by surging biopharmaceutical production and stringent purity mandates across North American and European facilities.
Market Forecast from 2027 to 2033
The data projects consistent expansion from a baseline of 22.46 Billion in 2026 to 44.30 Billion by 2033. This trajectory is underpinned by massive capital investments in advanced cell culture infrastructure, continuous downstream purification technologies, and escalating commercial demand for sustainable bio-based industrial enzymes and agricultural biotechnology solutions.
Segmentation Analysis Across Core Categories
The market is systematically segmented by type, end user, technology, and application. Type encompasses Upstream Processing, Downstream Processing, Process Analytical Technologies, and Bioprocess Consumables. Technology covers Fermentation, Biocatalysis, and Cell Culture. End Users span Industrial, Commercial, and Residential sectors utilizing specialized equipment like bioreactors and chromatography systems.
Geographic Distribution and Regional Performance
Regional performance highlights distinct adoption curves, with North America leading due to concentrated biopharmaceutical hubs and robust venture funding. Meanwhile, the Asia-Pacific region exhibits the highest growth velocity, driven by expanding contract manufacturing organizations in India and China requiring advanced fermentation and single-use filtration systems.
In-Depth Regional Review
North America dominates the landscape, supported by stringent USP and FDA guidelines that mandate cutting-edge process analytical technologies and high-purity buffer solutions. Concurrently, European markets focus heavily on sustainable bio-manufacturing and green energy initiatives, fostering rapid adoption of advanced wastewater treatment and biofuel bioprocessing frameworks.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct competitive advantages through specialized product ecosystems. Sartorius Aktiengesellschaft and Corning Inc. specialize in high-durability single-use bags and filtration membranes, while Repligen Corporation excels in advanced filtration and protein concentration systems, enabling seamless scalability for biopharmaceutical developers worldwide.
Porter's Five Forces Analysis
Industry rivalry is intense among established conglomerates like GEA Group and Eppendorf SE, though high switching costs for validated bioprocess consumables mitigate supplier and buyer power. The threat of new entrants remains moderate due to steep regulatory approval hurdles and proprietary intellectual property in cell culture media formulations.
SWOT Analysis of the Industrial Bioprocessing Sector
Strengths include robust technological innovation in single-use systems and high-yield fermentation. Weaknesses involve high equipment downtime costs. Opportunities lie in emerging personalized medicine applications, while threats stem from volatile raw material costs and complex cross-border regulatory compliance requirements.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with chemical and biochemical raw material suppliers providing high-purity reagents and polymers. Equipment manufacturers transform these inputs into bioreactors and chromatography systems, which are subsequently utilized by biopharmaceutical and industrial enzyme producers to deliver final therapeutic and commercial formulations to global end-users.
Investment Insights and High-Potential Areas
Investors should prioritize companies developing automated process analytical technologies and sustainable single-use consumables. Our analysis suggests that firms focusing on continuous bioprocessing and advanced biomass monitoring systems will capture outsized market share as facilities transition away from traditional stainless-steel infrastructure.
Conclusion and Key Takeaways
The Industrial Bioprocessing Market represents a high-growth sector set to achieve 44.30 Billion by 2033. Success hinges on mastering single-use integration, regulatory compliance, and scalable continuous manufacturing, favoring agile innovators and established market leaders alike.
Research Methodology for Baseline Estimates
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with key executives at firms like Codexis Inc. and Abec Inc., exhaustive trade registry data, secondary macroeconomic indicators, and proprietary bottom-up market sizing algorithms tailored to bioprocess equipment shipments.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for the Industrial Bioprocessing Market from 2027 to 2033, evaluating four primary segment categories across major geographic regions. Limitations include unforeseen geopolitical trade restrictions and macroeconomic currency fluctuations affecting equipment import-export tariffs.
Recent Developments and Strategic Industry Moves
Recent market activity is characterized by aggressive capacity expansions and strategic partnerships. Notable moves include Meissner Filtration Products scaling up single-use manufacturing facilities and collaborative ventures between tech innovators like OmniBRx Biotechnologies to deploy automated perfusion bioreactor systems globally.