Market overview of the Radiofrequency (RF) Needles Market
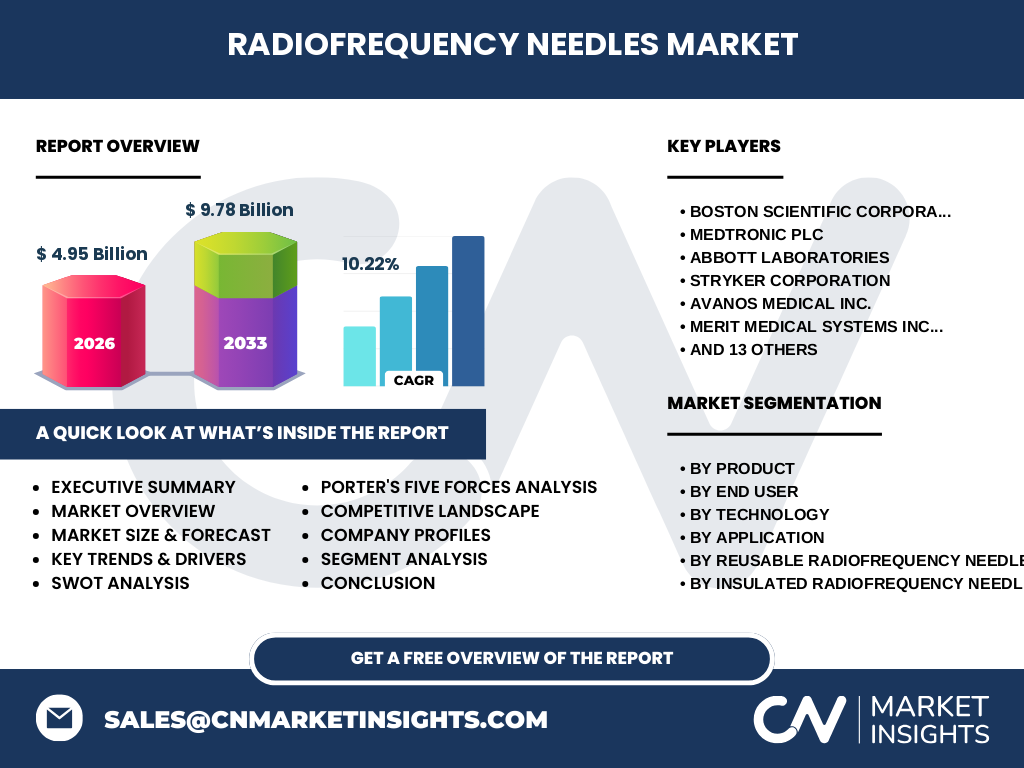
Our analysis indicates that the Radiofrequency (RF) Needles Market size stands at $4.95 Billion in 2026. This specialized medical device sector encompasses precision consumables used across pain management, oncology, and aesthetic dermatology, serving as the critical conductive interface for minimally invasive thermal ablation and neuromodulation procedures.
What are the core drivers, restraints, and opportunities shaping industry trajectory?
The market is propelled by a rising geriatric demographic suffering from chronic lower back pain and oncological lesions. However, strict FDA and CE mark regulatory hurdles for medical-grade stainless steel and tungsten raw materials act as growth restraints, while expansion into outpatient ambulatory surgical centers presents major untapped commercial opportunities.
Emerging trends and growth patterns in the sector
A definitive shift toward minimally invasive outpatient procedures is reshaping demand patterns. Clinicians increasingly favor advanced insulated and microneedle variants that protect non-target cutaneous and neural tissues, directly driving higher utilization rates across specialized clinics and urban aesthetic centers globally.
COVID-19 impact analysis and pandemic recovery trajectory
Elective pain management and aesthetic treatments plummeted during peak pandemic lockdowns, severely impacting short-term revenues. The subsequent recovery trajectory has been robust, driven by elective procedure backlogs and heightened hospital capital allocation toward specialized disposable procedural trays to minimize infection risks.
Competitive Benchmarking
The competitive landscape features a mix of medtech giants and specialized innovators. Industry stalwarts like Boston Scientific Corporation, Medtronic plc, and Abbott Laboratories leverage extensive global distribution networks, while specialized innovators like STARmed Co. Ltd. and Cosman Medical Inc. compete via proprietary probe designs.
Executive summary of key findings
Driven by technological advancements and surging clinical demand, the Radiofrequency (RF) Needles Market industry trends point toward sustained expansion. Strategic mergers, localized manufacturing shifts, and continuous product iterations in bipolar and pulsed RF modalities remain the primary cornerstones for maintaining competitive advantage.
Market forecast from 2027 to 2033
Based on our research, the market is projected to expand from $9.78 Billion by 2033, exhibiting a robust CAGR of 10.22% from 2027. This acceleration is underpinned by expanding reimbursement codes for chronic pain treatments and surging adoption of radiofrequency microneedling in dermatology.
Segmentation analysis across product, end-user, and technology verticals
Segmentation is categorized by product (Disposable, Reusable, Insulated, Non-Insulated), end-user (Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Dermatology Clinics), technology (Ablation, Pulsed, Microneedling, Bipolar, Monopolar), and application (Pain Management, Aesthetics, Oncology, Cardiology, Gynecology), offering targeted entry points for device manufacturers.
Regional market analysis and geographic performance distribution
North America dominates global consumption due to advanced healthcare infrastructure and favorable reimbursement frameworks. Meanwhile, Asia-Pacific represents the fastest-growing regional market, catalyzed by expanding healthcare expenditures in medical tourism hubs across Southeast Asia and rising domestic device manufacturing in East Asia.
In-depth regional review of high-growth territories
In North America, strict FDA compliance requirements favor well-established multinational players. Conversely, the Asia-Pacific region demonstrates high volume uptake of cost-effective disposable and reusable needles, though stringent customs checks at major cargo ports occasionally create localized supply chain bottlenecks for raw medical plastics.
Strategic positioning of leading enterprise profiles
Companies such as Stryker Corporation and CONMED Corporation focus on broad hospital portfolio bundling, whereas niche players like Pajunk GmbH and Inomed Medizintechnik GmbH emphasize precision neurosurgery instruments, tailoring their commercial strategies to distinct clinical buyer personas.
Porter's Five Forces analysis of competitive intensity
The threat of new entrants is moderate-to-low due to prohibitive regulatory clearance costs and complex ISO manufacturing standards. Supplier power over high-grade medical steel is balanced by high buyer switching costs, though intense rivalry among established tier-one suppliers keeps pricing pressure elevated.
SWOT analysis of the Radiofrequency Needles sector
Strengths include high procedural efficacy and established clinical acceptance. Weaknesses involve high per-unit consumable costs. Opportunities lie in emerging oncology ablation uses, while threats stem from stringent regulatory audits by agencies like the European Medicines Agency and FDA.
Value chain analysis from raw materials to end-users
The value chain originates with raw material suppliers providing medical-grade alloys and polymers. Component fabricators then assemble sterile needles before distributors route them through regional logistics hubs to end-users like hospitals, ambulatory surgical centers, and cosmetic clinics.
Investment insights and high-potential strategic areas
Investors should target niche innovators specializing in precision-insulated and depth-controlled microneedle technologies. These segments offer higher gross margins and protect manufacturers from commoditization pressures facing basic non-insulated bare tip alternatives in saturated hospital tenders.
Conclusion and key takeaways for industry stakeholders
The Radiofrequency (RF) Needles Market analysis confirms a lucrative, fast-growing sector underpinned by a 10.22% CAGR. Success requires navigating complex regulatory landscapes while investing aggressively in advanced insulated and pulsed radiofrequency technological capabilities to capture high-margin clinical segments.
Research methodology and baseline triangulation framework
Our baseline estimates are triangulated by cross-referencing global trade registry data, primary stakeholder interviews with practicing pain physicians and procurement directors, and secondary macroeconomic indicators such as regional healthcare expenditure growth and hospital bed capacity reports.
Scope of the report and analytical coverage parameters
This report covers global consumption trends, regulatory frameworks, and competitive dynamics across North America, Europe, Asia-Pacific, and Rest of World. Limitations include exclusion of unregistered grey-market surgical imports and non-medical aesthetic devices operating outside clinical oversight.
Recent developments, strategic partnerships, and product launches
Recent industry moves feature strategic acquisitions by giants like Boston Scientific Corporation alongside FDA clearances for advanced depth-controlled insulated needles by specialized firms. These initiatives aim to expand procedural safety profiles and consolidate market share in lucrative pain management sectors.