What is the market overview for the Predictive Artificial intelligence (AI) In Supply Chain Market?
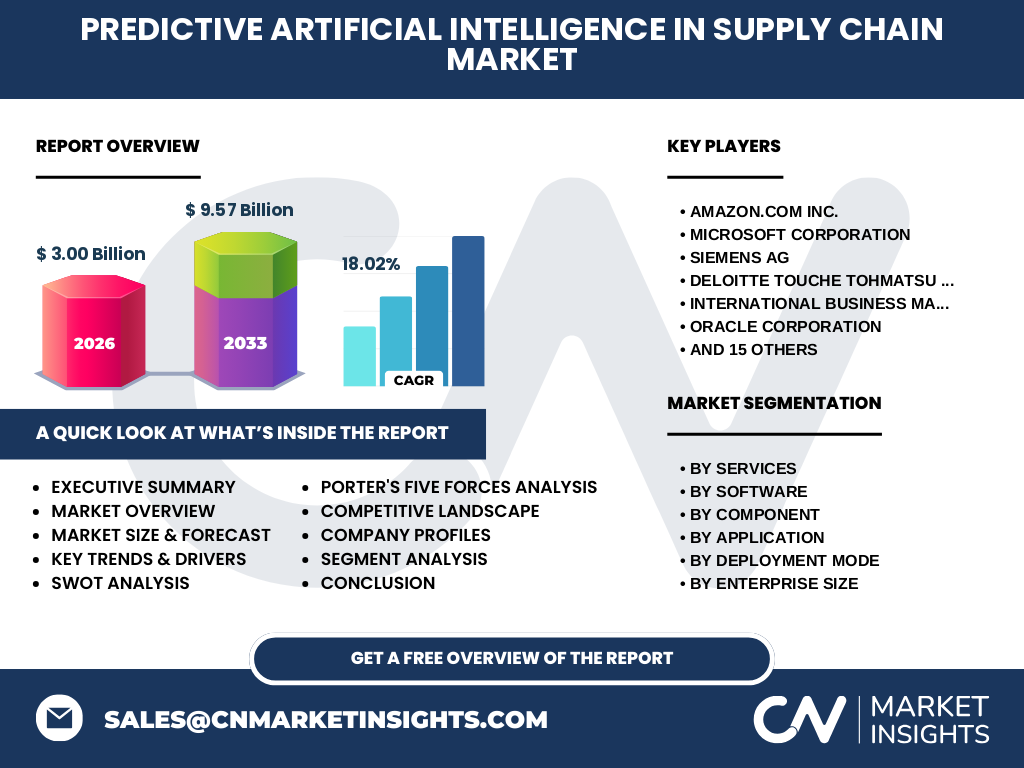
Our analysis indicates that the Predictive Artificial intelligence (AI) In Supply Chain Market is valued at $3.00 Billion in 2026. This sector encompasses advanced machine learning models deployed across global logistics networks, helping enterprises mitigate bottlenecks near critical nodes like the Port of Los Angeles and the Port of Rotterdam while adhering to stringent EU AI Act compliance standards.
What are the key market drivers, restraints, challenges, and opportunities shaping the Predictive Artificial intelligence (AI) In Supply Chain Market industry trends?
The primary growth catalysts include surging e-commerce volumes and complex semiconductor supply chain vulnerabilities involving raw silicon and rare earth elements. High implementation costs and legacy ERP integration hurdles remain notable restraints. However, massive opportunities lie in automated customs clearance and predictive logistics routing across volatile geopolitical corridors.
Emerging trends and growth patterns in Predictive Artificial intelligence (AI) In Supply Chain Market
The industry is witnessing an accelerated shift toward autonomous Inventory Optimization Software and edge-computing models. Enterprises are moving away from reactive spreadsheets toward real-time predictive demand sensing, heavily influenced by decarbonization mandates from the International Maritime Organization targeting ocean freight emissions.
How did the COVID-19 pandemic affect the Predictive Artificial intelligence (AI) In Supply Chain Market analysis and its recovery trajectory?
The pandemic exposed profound vulnerabilities in global sourcing, forcing manufacturers to adopt cloud-based Supply Chain Planning Software to survive sudden port closures and container shortages. Recovery has been spearheaded by C-suite executives prioritizing supply chain resilience over pure cost-efficiency, triggering massive post-pandemic tech investments.
Competitive Benchmarking and Market Concentration
Market concentration is moderately high, dominated by enterprise software giants and specialized AI innovators. Companies like Amazon.com Inc., Microsoft Corporation, and SAP SE leverage vast cloud ecosystems, while specialized players like Kinaxis Inc. and o9 Solutions Inc. carve out distinct advantages in concurrency planning.
Executive Summary of the Predictive Artificial Intelligence (AI) in Supply Chain Report
Our comprehensive evaluation confirms that the Predictive Artificial intelligence (AI) In Supply Chain Market is poised for explosive expansion. Driven by an impressive 18.02% CAGR, the market is projected to skyrocket from $3.00 Billion in 2026 to $9.57 Billion by 2033, fundamentally transforming global trade.
Market Forecast and Growth Trajectory from 2027 to 2033
The data projects a stellar expansion path, scaling from $3.00 Billion in 2026 to reach $9.57 Billion by 2033 at an 18.02% CAGR. This rapid acceleration is fueled by escalating demand for real-time visibility platforms in the automotive and pharmaceutical cold-chain sectors.
Segmentation Analysis of Software, Services, and Application Categories
The market breaks down by Software (covering Transportation Management Software and Predictive Maintenance Software), Services (including System Integration Services), Deployment Modes (On-Premise, Cloud-Based, Hybrid), Enterprise Size, and End Use Industries like Retail, Automotive, and Manufacturing, each driving targeted operational efficiencies.
Regional market analysis across North America, Europe, Asia-Pacific, and emerging economies
North America currently commands the largest market share due to early adoption by tech-forward logistics providers, while Asia-Pacific represents the fastest-growing region. This is driven by massive manufacturing hubs in China and Vietnam demanding automated Warehouse Management Software to counter rising labor costs.
In-depth regional review of localized logistical hurdles and regulatory frameworks
In Europe, strict GDPR regulations and carbon-tracking mandates enforced by the European Commission shape how predictive models ingest transport data. Meanwhile, North American operations focus heavily on driver shortage mitigations and rail freight optimization across transcontinental freight corridors.
Company profiles and strategic positioning of leading innovators
Industry leaders employ distinct strategies to capture market share. NVIDIA Corporation provides foundational hardware acceleration, Oracle Corporation and Honeywell International Inc. integrate AI deeply into industrial IoT, and specialized supply chain wizards like RELEX Solutions and ToolsGroup dominate retail inventory orchestration.
Porter's Five Forces analysis of the Predictive Artificial intelligence (AI) In Supply Chain Market
Bargaining power of buyers is moderate to high due to enterprise software alternatives, while supplier power over specialized GPU hardware remains elevated. The threat of new entrants is mitigated by high R&D barriers, though agile startups frequently disrupt legacy incumbents through niche Logistics Analytics Platforms.
SWOT analysis highlighting core competencies and market vulnerabilities
Strengths include unmatched data processing capabilities and superior demand forecasting accuracy. Weaknesses involve high initial deployment expenditures. Opportunities abound in sustainable logistics routing, whereas threats stem from escalating cybersecurity threats targeting critical port infrastructure and proprietary supplier databases.
Value chain analysis from raw material procurement to end-user delivery
The value chain flows from raw data generation via IoT sensors on cargo containers through cloud analytics engines provided by firms like Google LLC and IBM Corporation, ultimately delivering actionable insights to procurement officers managing lithium, steel, and agricultural commodities.
Investment insights and high-potential areas for venture capital and enterprise spending
High-potential investment pockets center around Artificial Intelligence Model Development Services and real-time risk management software. Investors should target B2B SaaS providers specializing in multi-enterprise workflow orchestration that can seamlessly connect disparate ERP systems across global manufacturing tiers.
Conclusion and key takeaways for executive decision-makers
Reaching $9.57 Billion by 2033 at an 18.02% CAGR underscores that predictive AI is no longer optional for modern logistics. Organizations failing to adopt cloud-based Supply Chain Planning Software risk severe margin compression amid escalating geopolitical trade frictions and volatile commodity pricing.
Research methodology used to triangulate market size and growth forecasts
Our proprietary research methodology triangulates bottom-up enterprise revenue disclosures with top-down macroeconomic indicators, cross-referenced against primary qualitative interviews with chief supply chain officers across major automotive, retail, and pharmaceutical conglomerates.
Scope of the report, coverage parameters, and analytical limitations
This report covers global deployment models from 2026 through 2033, evaluating software, services, and end-use sectors. Limitations include unforeseen macroeconomic shocks, sudden trade tariff shifts, and proprietary data restrictions enforced by privately held logistics technology vendors.
Recent developments, strategic partnerships, and product launches in the ecosystem
Recent milestones include strategic acquisitions and cloud integrations by firms like Manhattan Associates Inc. and C3.ai Inc., alongside joint ventures aimed at embedding generative AI into automated port management and container tracking to counteract global supply chain disruptions.