Market overview — definition, scope, and industry significance of Cash In Transit Services Market
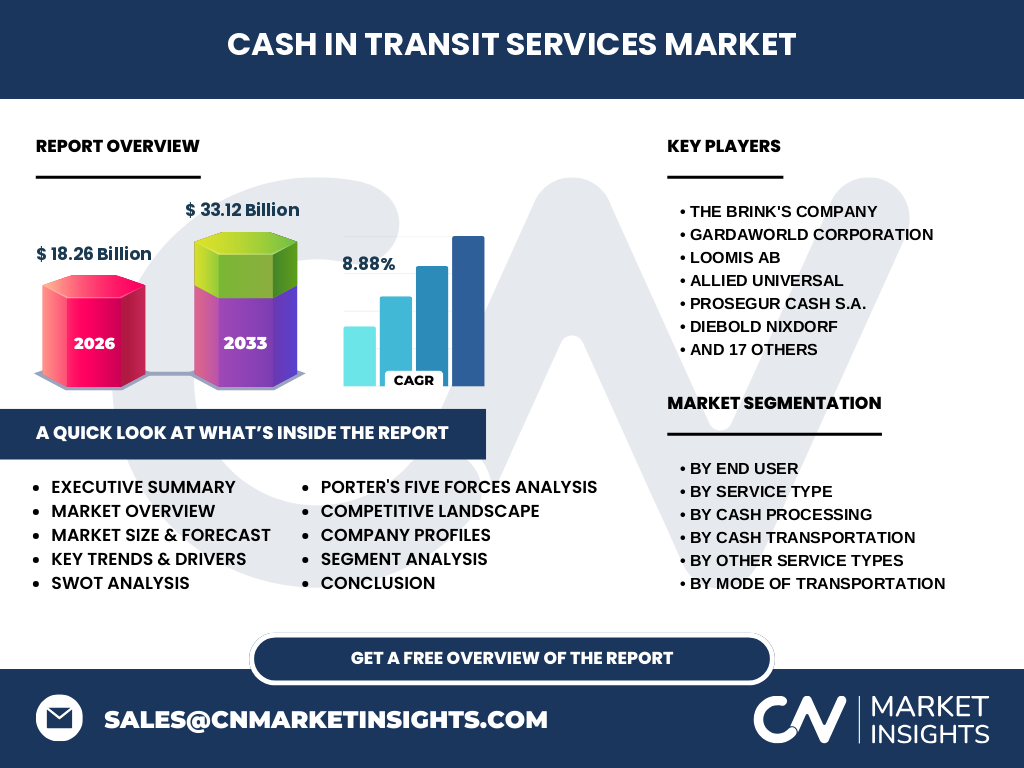
Our analysis indicates that the Cash In Transit Services Market encompasses the secure physical transport, processing, and management of banknotes, coins, and high-value assets. With a baseline valuation of 18.26 Billion in 2026, this sector forms the critical logistical backbone bridging central banks, commercial institutions, and retail merchants, mitigating severe counterparty and physical security vulnerabilities.
Key market drivers, restraints, challenges, and opportunities shaping Cash In Transit Services Market
Structural growth is propelled by persistent cash reliance in emerging economies, alongside strict regulatory mandates from bodies like the Federal Reserve and ECB. However, margin pressures from fuel price volatility and rising insurance premiums act as severe restraints. High-potential opportunities lie in outsourcing non-core bank operations to specialized logistics providers.
Emerging trends and growth patterns in Cash In Transit Services Market
The industry is experiencing a profound pivot toward smart cash recycling and predictive replenishment algorithms. Major operators are increasingly integrating IoT-enabled armored fleets with real-time telematics, optimizing route planning to counteract urban congestion and high carbon taxes across densely populated metropolitan hubs.
COVID-19 impact analysis — how the pandemic affected Cash In Transit Services Market and the recovery trajectory
Pandemic-era lockdowns accelerated digital payment adoption, causing temporary volume contractions for physical cash. However, our research confirms a resilient post-pandemic rebound as consumers and central banks re-established physical cash reserves as a vital emergency safeguard against systemic cyber vulnerabilities and grid outages.
Competitive landscape — major players, market concentration, and strategic dynamics
The market is heavily consolidated among global heavyweights like The Brink's Company, GardaWorld Corporation, and Loomis AB. These tier-one players leverage expansive proprietary networks and advanced cash management software to capture enterprise contracts, forcing regional competitors to pursue aggressive local niche differentiation or cross-border acquisitions.
Executive summary — high-level synthesis of key findings about Cash In Transit Services Market
Driven by compounding technological upgrades and secure outsourcing trends, the Cash In Transit Services Market analysis projects an expansion from 18.26 Billion in 2026 to 33.12 Billion by 2033. This represents a robust compound annual growth rate of 8.88%, signaling significant profit pools for tech-enabled logistics operators.
Market forecast — projected growth from 2027 to 2033
Based on our econometric modeling, the Cash In Transit Services Market market size will scale rapidly through the forecast window. Sustained by automated teller machine outsourcing and multi-vendor cash center consolidations, the sector is set to achieve a total valuation of 33.12 Billion by the conclusion of 2033.
Segmentation analysis — break down each segment category, explain what it covers and its market role
The sector bifurcates across end users, service types, and transportation modes. Key categories include Banks And Financial Institutions and Retail end users, deploying specialized services like Cash Transportation, Cash Processing, and Automated Teller Machine Services. Armored vehicles remain the dominant transit mode alongside emerging air and rail solutions.
Regional market analysis — geographic distribution and performance across regions
Geographic performance varies significantly based on banking density and regulatory frameworks. North America and Europe exhibit mature, high-value demand focused on automation and managed services, whereas Asia-Pacific and Latin America showcase accelerated volume growth driven by unbanked populations entering the formal financial architecture.
In-depth regional review — detailed examination of key regional markets
North American operations emphasize high-speed vaulting and retail cash management integrations managed by firms like Brink's. Conversely, European markets must navigate stringent cross-border transit regulations set by the European Union, while developing economies rely heavily on localized security providers to service vast, under-banked rural expanses.
Company profiles — strategic positioning of leading companies in Cash In Transit Services Market
Industry leaders utilize distinct competitive moats. Prosegur Cash S.A. and Giesecke+Devrient (G+D) blend secure physical transport with state-of-the-art software for end-to-end cash cycle optimization. Meanwhile, regional players like CMS Info Systems Ltd. and Transguard Group dominate their respective domestic territories through hyper-localized operational efficiency.
Porter's Five Forces analysis — competitive forces assessment
Supplier power remains moderate, constrained by specialized vehicle and vault infrastructure requirements. However, buyer power is high among major multinational banking conglomerates demanding aggressive pricing, while the threat of substitution is anchored by digital banking initiatives, though mitigated by mandatory emergency cash reserve laws.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Core strengths include deep institutional trust and proprietary armored fleets. Weaknesses feature high labor and insurance overheads. Opportunities emerge in advanced Managed Cash Services and counterfeit detection tech. Threats encompass escalating cyber-physical security breaches and aggressive central bank digital currency pilots.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with raw substrate and ink procurement by central banks, flowing downstream into secure printing facilities. Cash In Transit Services Market industry trends show logistics firms intercepting the currency at mint distribution points, executing secure transit, processing, and automated ATM replenishment for end consumers.
Investment insights — strategic recommendations and high-potential areas
Investors should direct capital toward firms scaling proprietary Automated Teller Machine Services and coin processing automation. Companies that successfully integrate AI-driven cash forecasting software into legacy transport frameworks will command superior operating margins and capture outsized enterprise market share.
Conclusion and key takeaways
The Cash In Transit Services Market is transitioning from a low-margin physical hauling sector into a high-tech, data-driven financial logistics ecosystem. Maintaining an 8.88% CAGR trajectory toward 33.12 Billion by 2033 proves that physical cash logistics remains an indispensable pillar of modern economic stability.
Research methodology — detail how baseline estimates are triangulated
Our findings synthesize exhaustive primary stakeholder interviews with central bankers, logistics executives, and retail CFOs. This qualitative intelligence is cross-referenced against secondary macroeconomic indicators, trade registry data, and historical industry databases to establish bulletproof baseline valuations for the Cash In Transit Services Market analysis.
Scope of the report — coverage parameters and limitations
This report covers global revenue streams generated by outsourced cash transportation, vaulting, and processing entities from 2026 through 2033. Excluded from this scope are internal, bank-owned captive courier networks and informal grey-market cash couriers operating outside formal regulatory compliance frameworks.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent strategic activity highlights aggressive technological convergence. Major market participants have rolled out advanced smart-safe ecosystems and cross-border logistics partnerships designed to streamline retail cash deposits, directly reducing manual handling risks and optimizing end-to-end cash visibility for commercial bank clients.