What defines the scope and industry significance of the Supply Chain Visibility Artificial Intelligence Market?
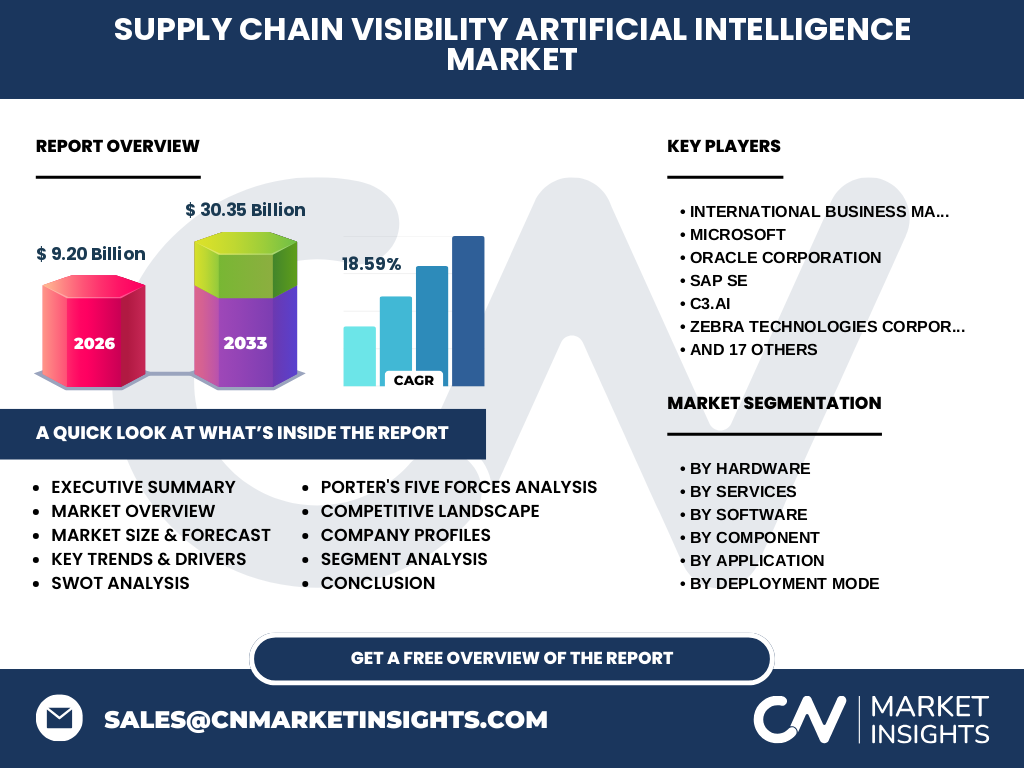
Our analysis indicates the Supply Chain Visibility Artificial Intelligence Market is valued at $9.20 Billion in 2026. This sector encompasses advanced machine learning models, IoT telemetry, and predictive algorithms designed to eradicate blind spots across complex logistics networks, safeguarding critical industrial components and raw materials from unexpected disruption.
Structural Growth Drivers, Restraints, and Opportunities
Market expansion is heavily propelled by stringent regulatory mandates from bodies like the FDA and European Union regarding cold-chain compliance for pharmaceuticals. However, persistent cybersecurity vulnerabilities in legacy telematics devices create adoption friction. High-potential opportunities lie in automated risk mitigation for volatile maritime routes through major ports.
Emerging Technological Trends and Evolving Growth Patterns
The shift toward generative AI for natural language exception handling is reshaping enterprise operations. Logistics leaders increasingly utilize real-time routing engines to bypass port congestion. This trend favors platform providers with advanced predictive analytics software capabilities capable of autonomously rerouting container shipments without human intervention.
COVID-19 Impact Analysis and Post-Pandemic Industry Recovery
The pandemic exposed catastrophic vulnerabilities in global sourcing models, forcing enterprises to abandon rigid just-in-time logistics. Post-pandemic recovery trajectories show massive capital reallocation toward cloud-based visibility suites. Companies now prioritize supply chain resilience over pure cost minimization, driving accelerated enterprise software adoption.
Competitive Benchmarking and Market Concentration Dynamics
The Supply Chain Visibility Artificial Intelligence Market exhibits a fragmented yet consolidating landscape dominated by specialized innovators and enterprise software giants. Industry leaders like SAP SE, Oracle Corporation, and Microsoft compete aggressively with specialized visibility platforms such as FourKites Inc. and Project44 Inc. to capture market share.
Executive Summary of Key Market Findings
Our comprehensive evaluation projects the market to surge from $9.20 Billion in 2026 to $30.35 Billion by 2033, expanding at a robust CAGR of 18.59%. Enterprise buyers are shifting from reactive tracking to prescriptive AI orchestration, fundamentally altering how multimodal freight and inventory are managed globally.
Long-Term Market Forecast from 2027 to 2033
Driven by compounding industrial digitization and autonomous logistics demands, the market will achieve an impressive 18.59% CAGR, culminating in a valuation of $30.35 Billion by 2033. Accelerated deployment among automotive and retail sectors serves as the primary catalyst for this sustained multi-year expansion trajectory.
Comprehensive Segmentation Analysis of Core Offerings
The market breaks down by component into Software, Hardware, and Services. Software categories include Supply Chain Visibility Software and Demand Forecasting Software. Hardware encompasses Radio Frequency Identification Devices and Sensors And Internet Of Things Devices, while Services cover crucial implementation and managed optimization offerings.
Geographic Distribution and Regional Market Performance
North America maintains a dominant revenue share due to early adoption by major e-commerce fulfillment networks. Meanwhile, Asia-Pacific represents the fastest-growing geographic segment, propelled by rapid manufacturing expansion across Southeast Asia and heavy investments in smart port infrastructure throughout maritime trade hubs.
In-Depth Regional Review and Localized Market Constraints
In Europe, strict carbon accounting regulations compel firms to integrate sustainability metrics into their routing software. Conversely, North American adoption is bottlenecked by driver shortages, elevating the strategic necessity of autonomous telematics devices and predictive transit visibility frameworks.
Strategic Positioning of Leading Enterprise Players
Industry stalwarts like International Business Machines Corporation and enterprise resource planning leaders like Infor Inc. and Blue Yonder Group Inc. embed proprietary neural networks into legacy frameworks. Meanwhile, specialized pure-play innovators like Tive Inc., Roambee Corporation, and Shippeo SAS focus intensely on hyper-granular, real-time shipment condition monitoring.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate-to-high, as enterprises demand interoperable software that integrates smoothly with existing enterprise resource planning architectures. Threat of new entrants is mitigated by high R&D costs required to build robust, secure IoT ingestion pipelines capable of handling millions of concurrent data streams.
SWOT Analysis of the Supply Chain Visibility AI Sector
Key strengths include unprecedented predictive accuracy and granular modal visibility. Weaknesses involve high initial deployment costs for small and medium enterprises. Opportunities abound in cold-chain pharmaceutical monitoring, while threats stem from escalating data privacy regulations and cross-border cybersecurity vulnerabilities.
Value Chain Analysis from Raw Materials to End-Users
The value flow originates with raw component manufacturers supplying semiconductors for telematics hardware and barcode scanners. It progresses through software developers writing algorithmic optimization models, culminating in systems integrators delivering customized dashboards to end-user verticals such as automotive and consumer goods.
Strategic Investment Insights and High-Potential Opportunity Areas
Venture capital and private equity deployment should focus on niche solutions bridging multimodal transport gaps, particularly predictive analytics software targeting Scope 3 carbon emissions tracking. Mergers and acquisitions activity will likely concentrate on hardware-software convergence innovators.
Conclusion and Strategic Takeaways for Industry Stakeholders
The trajectory from 2026 to 2033 proves that artificial intelligence is no longer optional for global logistics. Organizations failing to adopt predictive visibility tools face severe operational penalties, margin compression, and inability to meet evolving consumer expectations for delivery transparency.
Rigorous Research Methodology and Data Triangulation
Baseline market estimates are synthesized by cross-referencing primary qualitative interviews with Chief Supply Chain Officers, secondary trade registry data from international shipping bodies, and macroeconomic indicators from global logistics indices, ensuring high-fidelity market sizing.
Scope of the Report and Analytical Parameters
This report covers global deployment models across cloud and on-premises environments, evaluating large enterprises alongside small and medium enterprises. Limitations include the exclusion of hyper-local intracity courier services and unregulated informal supply chain networks in developing economies.
Recent Industry Developments, Partnerships, and Strategic Announcements
Recent market dynamism features strategic acquisitions of telematics providers by enterprise software vendors, alongside major partnership announcements between cloud providers and IoT device manufacturers aimed at streamlining sensor-to-cloud data ingestion protocols for automated warehouse management.