Market overview and structural significance of the Nutrient Autoanalyzer Market
Our analysis indicates that the Nutrient Autoanalyzer Market is valued at 1.42 Billion in 2026. This sector encompasses advanced laboratory and field instrumentation designed for automated chemical analysis of water, soil, and food matrices. Key systems include Continuous Flow Analyzers and Discrete Analyzers, vital for monitoring nitrogen, phosphorus, and silicates under stringent environmental regulations enforced by bodies like the USEPA.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating water quality mandates and agricultural optimization needs. Stringent wastewater discharge limits compel municipal and industrial laboratories to adopt High Throughput Colorimetric Continuous Flow Analyzers. Conversely, high capital expenditure requirements for Benchtop Multi Parameter Nutrient Analyzers and technical bottlenecks in processing high-turbidity samples act as notable market restraints for smaller facilities.
Emerging Industry Trends and Technology Shifts
There is a pronounced industry migration toward field-deployable testing solutions, notably Handheld Portable Nutrient Analyzers and Field Based Portable Photometric Analyzers. Laboratories increasingly demand automation to minimize human error in wet chemistry workflows. Innovators like SubCtech GmbH and NT Sensors B.V. are capitalizing on this by introducing IoT-enabled sensors that stream real-time nutrient data directly to regulatory databases.
COVID-19 Impact Analysis and Market Recovery
The pandemic initially disrupted supply chains for specialized optical components and fluidic manifolds, delaying shipments for firms like Skalar Analytical B.V. and SEAL Analytical Limited. However, post-COVID recovery has accelerated sharply due to heightened institutional focus on biosecurity, wastewater epidemiology, and remote monitoring capabilities. Laboratories rapidly pivoted toward automated discrete systems to maintain testing continuity during labor shortages.
Competitive Benchmarking and Industry Concentration
The Nutrient Autoanalyzer Market exhibits moderate concentration, anchored by global heavyweights such as Thermo Fisher Scientific Inc., Xylem Inc., and Shimadzu Corporation. These market leaders maintain dominance through robust distribution networks and comprehensive product portfolios spanning Air Segmented Flow Analyzers to Microplate Based Discrete Photometric Analyzers. Smaller specialists compete effectively by offering modular, niche-specific benchtop instruments.
Executive Summary: Core Findings and Strategic Outlook
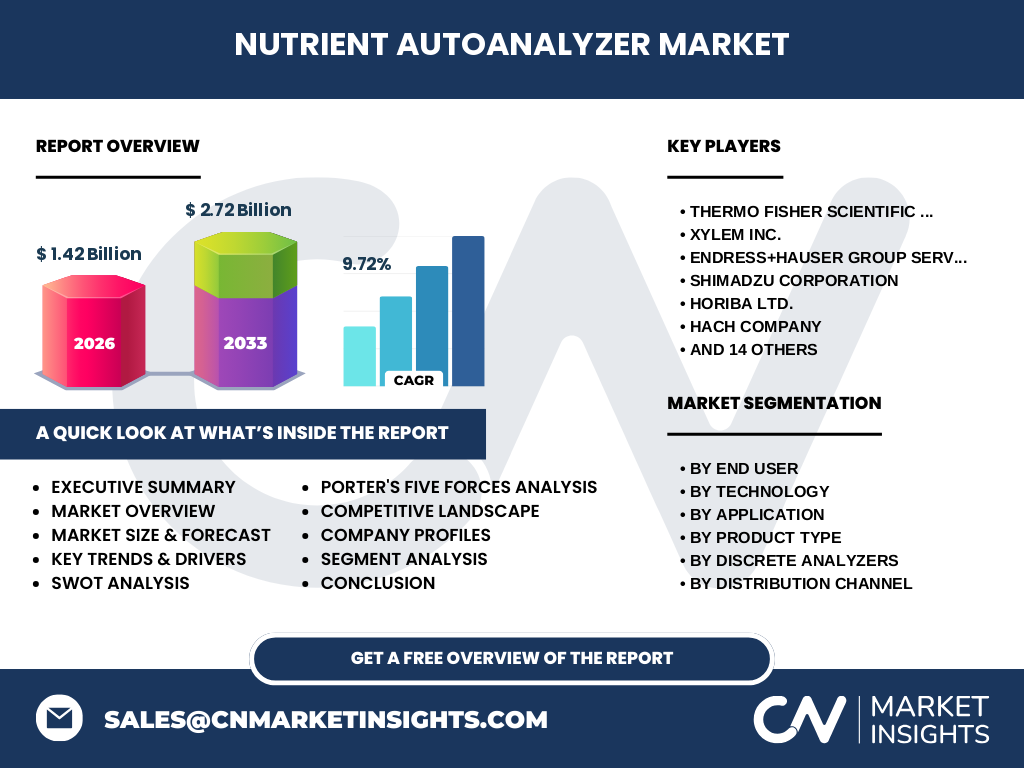
Our comprehensive research confirms that the Nutrient Autoanalyzer Market is entering a high-growth phase. Driven by environmental monitoring mandates and industrial automation, the sector is projected to expand from 1.42 Billion in 2026 to 2.72 Billion by 2033, representing a robust CAGR of 9.72%. Strategic investments in portable and discrete analyzers will yield the highest returns.
Long-Term Market Forecast through 2033
Based on our econometric modeling, the market trajectory projects stellar expansion, surging from 1.42 Billion in 2026 to reach 2.72 Billion by 2033. This growth trajectory, underpinned by a 9.72% CAGR, reflects accelerated adoption across emerging economies upgrading their municipal wastewater infrastructure and tightening agricultural runoff standards monitored by regional environmental protection agencies.
Segmentation Analysis across Technologies and Applications
Market segmentation covers End Users, Technologies, Applications, Product Types, and Distribution Channels. Notable sub-segments include Colorimetric Analysis and Flow Injection Analysis within technology, alongside Environmental Testing and Agriculture within applications. Discrete Analyzers and Continuous Flow Analyzers dominate hardware sales, catering to high-volume commercial laboratories and research institutes requiring precision.
Geographic Distribution and Regional Market Performance
Regional performance varies significantly based on local environmental legislation and industrial density. North America leads in market adoption due to stringent EPA wastewater mandates, closely followed by Europe, where strict EU Nitrates Directives drive continuous monitoring investments. Asia-Pacific represents the fastest-growing regional market, fueled by rapid industrialization and governmental clean-water initiatives in China and India.
In-Depth Regional Review of Key Markets
European laboratories heavily favor Air Segmented Flow Analyzers and high-sensitivity automated photometric systems to comply with the EU Water Framework Directive. In contrast, the North American market demonstrates strong demand for Random Access Discrete Analyzers in commercial testing labs prioritizing sample throughput. Meanwhile, Asia-Pacific investments focus on portable field units for real-time agricultural runoff monitoring.
Strategic Positioning of Leading Industry Players
Industry leaders employ distinct strategies to capture market share. Hach Company and Endress+Hauser Group Services AG leverage extensive global service networks for continuous flow systems. Meanwhile, specialized innovators like Metrohm AG and HORIBA Ltd. focus on proprietary ion-selective and spectrophotometric technologies to secure high-value contracts within pharmaceutical and academic research laboratories.
Porter's Five Forces Analysis of the Sector
Competitive rivalry is high, driven by established players constantly innovating in assay speed and reagent reduction. Supplier power remains moderate due to specialized optical and fluidic component requirements. Threat of substitution is low because standardized wet chemistry protocols strictly mandate certified autoanalyzer equipment for official regulatory reporting in environmental and food safety applications.
SWOT Analysis: Strategic Strengths, Weaknesses, Opportunities, and Threats
Key strengths include high analytical precision and rapid throughput. Weaknesses involve high initial capital outlays and ongoing reagent maintenance costs. Opportunities lie in expanding IoT-enabled field-portable analyzers for remote agricultural testing. Primary threats stem from stringent international trade tariffs affecting sensitive analytical component imports and supply chain vulnerabilities for specialized glass manifolds.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing high-purity optical glass, specialized valves, and microfluidic pumps. Instrument manufacturers such as Skalar Analytical B.V. and Systea S.p.A. assemble these into complex benchtop and portable analyzers. Distribution occurs via direct sales or specialized channel partners, ultimately supplying municipal water plants, agricultural testing facilities, and industrial research laboratories.
Investment Insights and High-Potential Growth Areas
Our analysis highlights Battery Operated Portable Chemical Analyzers and Random Access Discrete Analyzers as prime areas for strategic investment. Investors should target companies integrating IoT and AI-driven data analysis into their software platforms, as laboratories increasingly demand automated quality control and cloud-based compliance reporting to reduce operational overhead.
Conclusion and Strategic Takeaways
The Nutrient Autoanalyzer Market presents compelling growth opportunities, backed by a projected climb to 2.72 Billion by 2033 at a 9.72% CAGR. Stakeholders must prioritize technological agility, particularly developing field-portable and IoT-connected analyzers, to capture shifting demand from centralized laboratories toward decentralized, real-time environmental monitoring applications.
Research Methodology and Baseline Estimation
Our baseline estimates are triangulated using a rigorous methodology combining primary stakeholder interviews with C-level executives at firms like FOSS Analytical A/S and Astoria-Pacific International Inc. This is cross-referenced with secondary trade registry data, customs import-export logs for optical instruments, and macroeconomic indicators concerning global environmental infrastructure spending.
Scope of the Report and Coverage Parameters
This report covers the global Nutrient Autoanalyzer Market across five core product segments, four application verticals, and major geographic regions from 2026 to 2033. Limitations include the exclusion of non-automated manual titration kits and standard laboratory glassware not integrated into proprietary analyzer workflows, focusing strictly on dedicated automated nutrient testing hardware.
Recent Industry Developments and Strategic Partnerships
Recent months have seen aggressive strategic maneuvers, including AMS Alliance launching compact discrete analyzers tailored for winery and dairy testing. Furthermore, partnerships between sensor manufacturers like SubCtech GmbH and municipal water authorities have accelerated the deployment of unattended, continuous nutrient monitoring stations across major European river basins.