Market overview and structural scope of the Robotsystem 70 New Generation (RBS 70 NG) Air Defense System Market
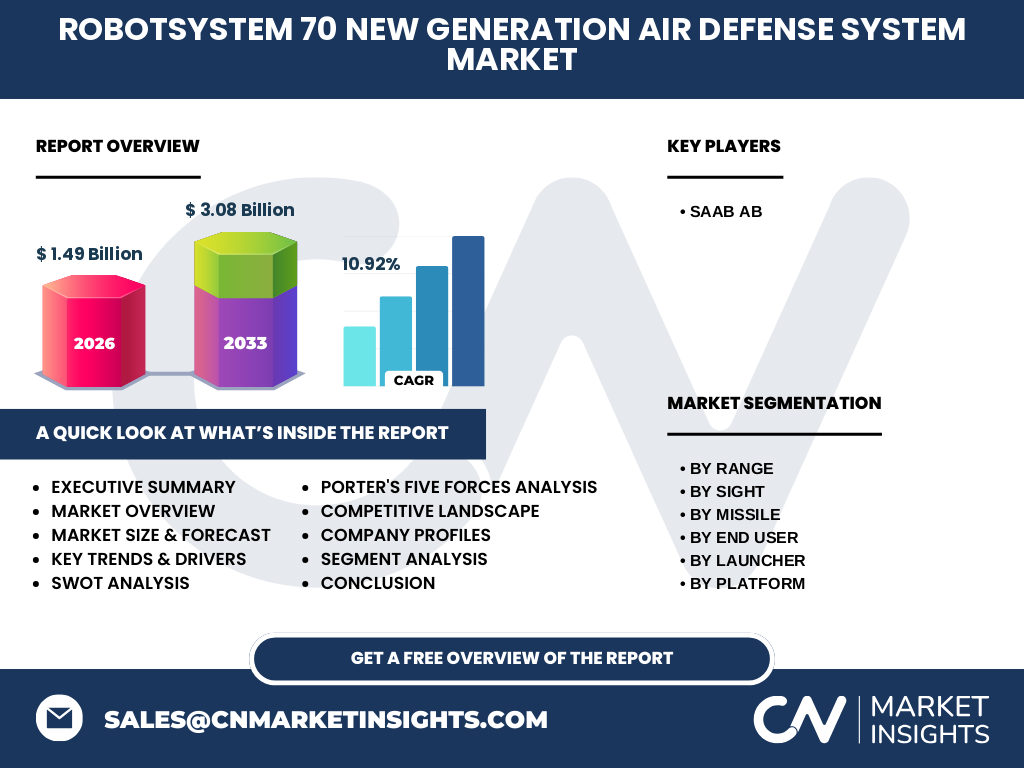
Our analysis indicates that the Robotsystem 70 New Generation (RBS 70 NG) Air Defense System Market represents a highly specialized defense sector valued at $1.49 Billion in 2026. This proprietary technology framework encompasses advanced very short-range air defense (VSHORAD) solutions, integrating state-of-the-art laser guidance and thermal imaging to protect high-value military assets against low-flying aircraft and unmanned aerial vehicles.
Key market drivers, restraints, challenges, and opportunities shaping the industry
The primary growth catalyst is escalating geopolitical instability, driving defense ministries to modernize VSHORAD infrastructure. However, supply chain bottlenecks for rare earth raw materials used in Thermal Imaging Sight components act as a constraint. Opportunities lie in upgrading legacy platforms with advanced Target Tracking Sight units to counter swarm drone tactics.
Emerging trends and growth patterns in the sector
The market is shifting decisively toward modular interoperability and high-precision digital sighting architectures. Based on our research, defense contractors are heavily investing in Laser Guidance Sight upgrades and vehicle-mounted configurations to maximize tactical mobility across diverse terrain, significantly reducing deployment times for front-line army units.
COVID-19 impact analysis and pandemic recovery trajectory
The pandemic severely disrupted global defense supply chains, particularly regarding critical semi-conductors and high-grade optical glass necessary for Night Vision Sight manufacturing. Recovery has been robustly accelerated by emergency defense budget supplementals, allowing manufacturers to clear backlogs and streamline production lines for Surface To Air Missile inventories.
Competitive landscape, major players, and strategic market concentration
Market concentration remains intensely high, dominated by specialized prime defense contractors like Saab AB. Strategic dynamics revolve around proprietary laser-beam riding technology and comprehensive lifecycle support packages, creating significant entry barriers for new defense technology entrants attempting to replicate integrated Launcher and Sight units.
Executive summary of the Robotsystem 70 New Generation (RBS 70 NG) Air Defense System Market analysis
Our comprehensive findings show the sector positioned for exceptional expansion, driven by modernized tactical defense requirements. The market achieves a projected 10.92% CAGR from 2027 to 2033, fueled by escalating demand for highly mobile, precision-guided short-range air defense solutions across international military procurement programs.
Market forecast and projected growth trajectory from 2027 to 2033
The data suggests a stellar valuation surge, scaling from the 2026 baseline to reach $3.08 Billion by 2033. This sustained trajectory reflects multi-year defense procurement cycles, institutional spending commitments, and widespread military adoption of advanced Guided Interceptor Missile and support equipment packages.
Segmentation analysis across range, sight, missile, end user, and platform categories
Segmentation reveals critical purchasing priorities across military branches. Key categories include range tiers (Short, Medium, Long), specialized optics such as the Daylight Optical Sight, missile types including the Extended Range Missile, and platform deployments ranging from ground-based setups to Vehicle Mounted configurations.
Regional market analysis and geographic distribution performance
Geographic performance highlights strong procurement concentrations in regions facing acute territorial security challenges. European and Asia-Pacific defense budgets lead deployment rates, heavily prioritizing portable launcher units and robust Identification Friend Or Foe System integrations to ensure rapid identification and engagement capabilities.
In-depth regional review of key high-performing markets
A closer examination of frontline territories shows defense modernization initiatives heavily centered on upgrading legacy VSHORAD architectures. Strict regulatory export controls from bodies like the EU Council shape supply flows, while local defense procurement mandates favor domestic integration of Support Equipment and maintenance tools.
Company profiles and strategic positioning of leading market participants
Industry leadership is anchored by innovators like Saab AB, whose strategic positioning relies on continuous product evolution, superior laser-guidance accuracy, and deep integration with NATO-standard tactical networks. Their proprietary approach to the Launcher Stabilization Unit cements their dominant tier-one supplier status.
Porter's Five Forces analysis of competitive industry pressures
Supplier power is moderate due to specialized aerospace-grade materials, while buyer power is heavily concentrated among sovereign defense ministries. The threat of substitutes remains remarkably low given the strict technological supremacy required of modern Surface To Air Missile systems and advanced Thermal Imaging Sight arrays.
SWOT analysis covering strategic strengths, weaknesses, opportunities, and threats
Key strengths include unmatched hit probability and zero-signature laser guidance. Weaknesses involve long R&D lead times. Opportunities abound in joint-nation defense technology partnerships, whereas external threats include strict defense budget fluctuations and geopolitical trade restrictions on critical missile propulsion raw materials.
Value chain analysis from raw materials to end-user deployment
The value chain initiates with advanced alloy and semiconductor raw material sourcing, progressing through precision optical manufacturing for the Sight component, final assembly of the Missile Launch Tube, and concluding with tactical deployment by army and air force end-users supported by comprehensive training equipment.
Investment insights, strategic recommendations, and high-potential areas
Investors should target technological innovators specializing in Cooling Unit optimization and advanced Operator Training Equipment. These sub-segments offer high margins and essential recurring revenue streams as militaries increasingly demand simulation-based readiness training alongside physical hardware deployments.
Conclusion and strategic takeaways for industry stakeholders
The sector offers compelling long-term fundamentals backed by a robust 10.92% CAGR. Stakeholders must prioritize software-defined upgrade paths for existing Portable Launcher Unit inventories and forge strategic alliances with established prime contractors to capture expanding global procurement budgets.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by cross-referencing official defense trade registries, primary stakeholder interviews with procurement directors, and secondary macroeconomic indicators such as national defense budget allocations, export licensing data, and tier-one manufacturer financial disclosures.
Scope of the report, coverage parameters, and analytical limitations
This report covers global deployment metrics, technological segmentations, and competitive positioning from 2026 through 2033. Limitations include restricted access to classified black-budget military procurement programs and rapidly evolving export control legislation overseen by international regulatory bodies.
Recent developments, product launches, and strategic industry moves
Recent milestones feature advanced software upgrades for the Target Tracking Sight and strategic export contracts secured by key industry players like Saab AB. These moves underscore a broader market shift toward digital integration, enhanced jamming resistance, and rapid deployment capabilities across allied nations.