Executive Summary of the Defense Cloud Market
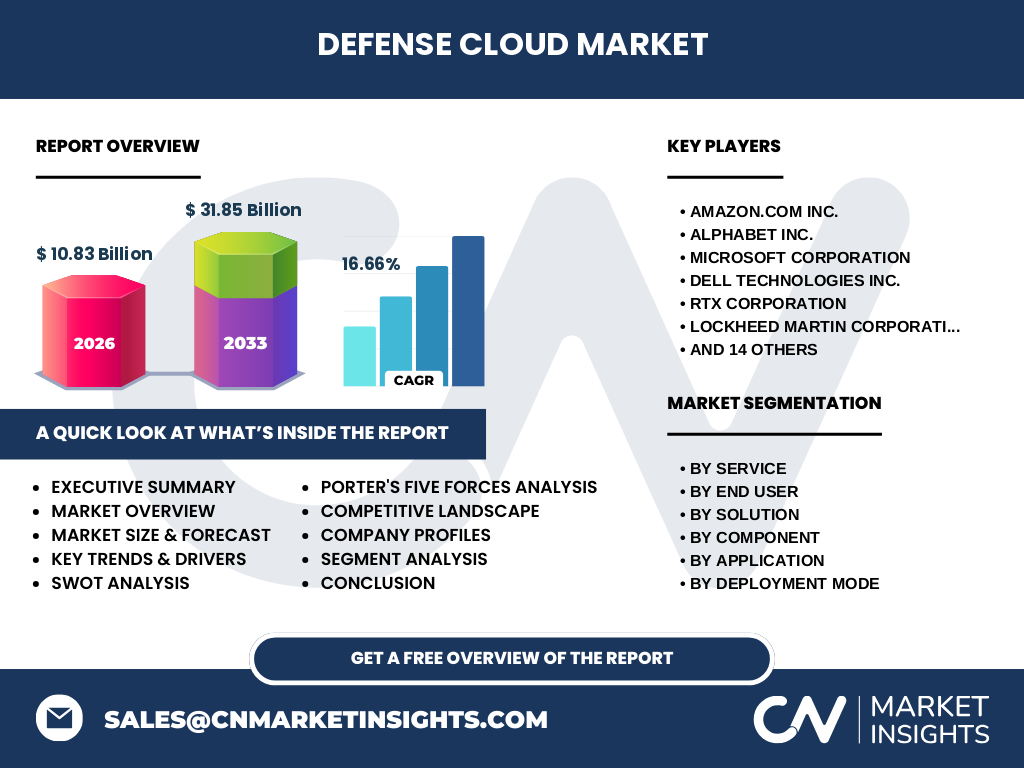
Our analysis indicates that the Defense Cloud Market size stands at 10.83 Billion in 2026, driven by aggressive digital transformation initiatives across global military apparatuses. Driven by rapid technological modernization, the sector is projected to surge to 31.85 Billion by 2033, expanding at a robust 16.66% CAGR. Industry titans like Microsoft Corporation and Amazon.com Inc. are capturing significant market share by delivering hyper-scale edge solutions tailored for classified combat operations.
What is the scope and definition of the Defense Cloud Market?
The Defense Cloud Market encompasses secure, mission-critical cloud computing ecosystems, including Infrastructure as a Service (IaaS) and Cloud Security Solutions, engineered specifically for military, homeland security, and defense agencies. Based on our research, this specialized market provides resilient data management infrastructure necessary to support tactical edge computing, classified intelligence sharing, and secure multi-domain operations across global defense networks.
Structural Growth Drivers and Market Restraints
Growth is primarily propelled by the urgent need for real-time Intelligence, Surveillance, and Reconnaissance (ISR) data processing and interoperability across allied forces. Conversely, stringent data sovereignty regulations and vulnerabilities to advanced cyber-attacks act as primary restraints. Defense agencies must balance rapid migration with uncompromised operational security, favoring vendors capable of strict compliance certification.
Emerging Trends and Strategic Shift Toward Multi-Cloud Architectures
The data suggests a decisive pivot toward decentralized tactical edge nodes and hybrid-cloud frameworks to prevent single points of failure during combat operations. Innovators such as Palantir and Oracle are embedding advanced AI analytics directly into cloud environments, enabling commanders to process petabytes of battlefield data instantaneously and maintain tactical superiority.
COVID-19 Impact Analysis and Pandemic Recovery Trajectory
The pandemic accelerated digital modernization roadmaps as remote command-and-control operations became an operational imperative for global defense bodies. Supply chain disruptions for foundational server hardware initially hindered deployment timelines, but recovery has been marked by surging investments in resilient, decentralized cloud architecture designed to withstand future geopolitical and biological shocks.
Competitive Benchmarking and Market Concentration
The competitive landscape is characterized by intense rivalry among hyper-scale technology giants and legacy defense prime contractors. Companies like Microsoft Corporation and Amazon.com Inc. dominate cloud infrastructure provisioning, while defense contractors such as RTX Corporation and Lockheed Martin integrate these cloud environments into proprietary weapon systems and command networks.
Market Forecast Analysis from 2027 to 2033
Projected to scale dramatically from 10.83 Billion to 31.85 Billion at a 16.66% CAGR, the market forecast reflects sustained budget allocations for secure digital infrastructure. Our analysis shows that increasing adoption of AI-driven combat operations and automated threat detection will exponentially accelerate spending through the early 2030s.
Segmentation Analysis Across Solutions, Services, and End Users
The ecosystem is segmented by solution, service, deployment mode, application, and end user. Infrastructure as a Service (IaaS) and Managed Services form the bedrock of adoption. Military and defense agencies demand specialized deployment modes—ranging from Public Cloud to classified Private and Hybrid clouds—to handle sensitive intelligence workloads securely.
Geographic Distribution and Regional Market Analysis
North America commands the largest share of the defense cloud ecosystem, anchored by massive Department of Defense modernization budgets and domestic tech giants. Meanwhile, the Asia-Pacific region exhibits the fastest growth trajectory, driven by rising defense expenditures in nations modernizing their naval and aerospace intelligence networks.
In-Depth Regional Review of Key Defense Markets
In North America, strict compliance frameworks like FedRAMP dictate vendor qualification, favoring established primes like General Dynamics and Leidos. In contrast, European markets are prioritizing sovereign cloud initiatives to ensure regional data control, directly shaping how international firms deploy localized data centers and secure communication pipelines.
Company Profiles and Strategic Positioning
Leading players utilize distinct value propositions; for instance, Booz Allen Hamilton and SAIC provide high-end integration and consulting, whereas Cisco Systems Inc. and Dell Technologies deliver the underlying hardware and secure networking fabric necessary for seamless cloud migration in contested tactical environments.
Porter's Five Forces Assessment of the Defense Cloud Ecosystem
Bargaining power of buyers is moderate to high, as major government entities dictate strict pricing and security mandates. Threat of new entrants remains low due to formidable barriers to entry, including stringent security clearances, high capital requirements, and complex regulatory compliance unique to military contracting.
SWOT Analysis of the Defense Cloud Sector
Key strengths include unmatched scalability and real-time data integration for combat operations. Weaknesses involve complex legacy system integration hurdles. Opportunities lie in expanding hybrid-cloud adoption for tactical edge computing, while severe threats stem from sophisticated state-sponsored cyber espionage targeting cloud repositories.
Value Chain Analysis from Silicon to Combat Operations
The value chain originates with raw silicon and semiconductor manufacturers, flowing through hardware infrastructure providers and cloud software architects, culminating in systems integrators who deliver bespoke platforms to end-users like homeland security and military branches for tactical execution.
Investment Insights and High-Potential Growth Areas
Strategic investment should prioritize Cloud Security Solutions, Identity and Access Management, and Disaster Recovery solutions. As cyber threats escalate, niche firms specializing in zero-trust architecture and encrypted data storage present exceptional acquisition targets for major defense primes.
Conclusion and Strategic Takeaways for Industry Stakeholders
Sustaining a competitive edge requires defense contractors and tech providers to master secure, multi-cloud interoperability. With the market scaling toward 31.85 Billion by 2033, early investments in edge-compatible cloud solutions will determine market leadership in modern defense technology.
Research Methodology and Baseline Data Triangulation
Our baseline estimates are rigorously triangulated by combining secondary macroeconomic indicators, exhaustive trade registry data, and primary stakeholder interviews with chief technology officers across top defense firms, ensuring high-fidelity market sizing and predictive accuracy.
Scope of the Report and Coverage Parameters
This report evaluates the global Defense Cloud Market across all specified deployment models, solution types, and end-user categories from 2026 through 2033. Geographic limitations and classification constraints on strictly black-budget programs are accounted for through econometric modeling and expert validation.
Recent Developments, Partnerships, and Strategic Moves
Recent market momentum is highlighted by multi-billion dollar cloud contracts awarded to tech giants by defense ministries, alongside strategic joint ventures between traditional aerospace firms and SaaS providers to accelerate secure tactical software deployment and artificial intelligence integration.