What is the scope and industry significance of the Reusable Medical Devices Market?
Our analysis indicates that the Reusable Medical Devices Market encompasses durable clinical assets engineered for multi-patient use, ranging from surgical instruments to advanced monitoring equipment. Valued at 17.42 Billion in 2026, this sector forms the economic and operational backbone of modern healthcare systems. Regulatory oversight by bodies like the US FDA and EMA demands rigorous validation of reprocessing protocols, ensuring that titanium, stainless steel, and medical-grade plastic instruments maintain structural integrity across thousands of cycles without compromising patient safety or increasing nosocomial infection risks.
Structural Growth Drivers and Restraints in the Reusable Medical Devices Market
The Reusable Medical Devices Market is propelled by escalating surgical volumes and strict economic imperatives favoring durable asset amortization over single-use disposables. However, growth is constrained by high upfront capital outlays, complex sterilization validation requirements using steam or ethylene oxide, and stringent carbon footprint reduction mandates. Supply chain bottlenecks involving high-purity titanium and medical-grade silicone further challenge procurement officers across major hospital networks and ambulatory surgical centers striving to balance clinical efficacy with lifecycle cost management.
Emerging Trends and Growth Patterns Shaping the Industry
Recent Reusable Medical Devices Market industry trends highlight a definitive pivot toward smart asset tracking via RFID-embedded surgical trays and advanced robotic compatibility. Companies like Intuitive Surgical Inc. and Stryker Corporation are leading the charge by designing modular instrumentation specifically engineered for robotic-assisted surgery platforms. This shift minimizes wear during high-precision procedures while optimizing Central Sterile Services Department workflows, directly addressing hospital labor shortages through automated decontamination tracking and predictive maintenance analytics.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
The COVID-19 pandemic severely disrupted the Reusable Medical Devices Market as elective procedures halted globally, heavily impacting revenues for multinational manufacturers like Medtronic plc and Johnson & Johnson. Recovery trajectories surged post-pandemic as surgical backlogs forced healthcare providers to aggressively replenish depleted stocks of diagnostic equipment, surgical instruments, and endoscopes. This rebound accelerated institutional focus on robust sterilization validation methods, such as hydrogen peroxide plasma and advanced steam autoclaving, to future-proof facility operations against sudden infectious disease outbreaks.
Competitive Benchmarking and Strategic Dynamics
The Reusable Medical Devices Market analysis reveals a highly consolidated landscape dominated by tier-one conglomerates alongside specialized innovators like KARL STORZ SE & Co. KG and Olympus Corporation. Strategic dynamics center on aggressive portfolio diversification through mergers, acquisitions, and proprietary service contracts for reprocessing automation. Firms are increasingly bundling hardware with digital sterilization analytics, forcing regional competitors to adopt value-based pricing models to secure long-term purchasing agreements with large-scale hospital group purchasing organizations.
Executive Summary of the Reusable Medical Devices Market
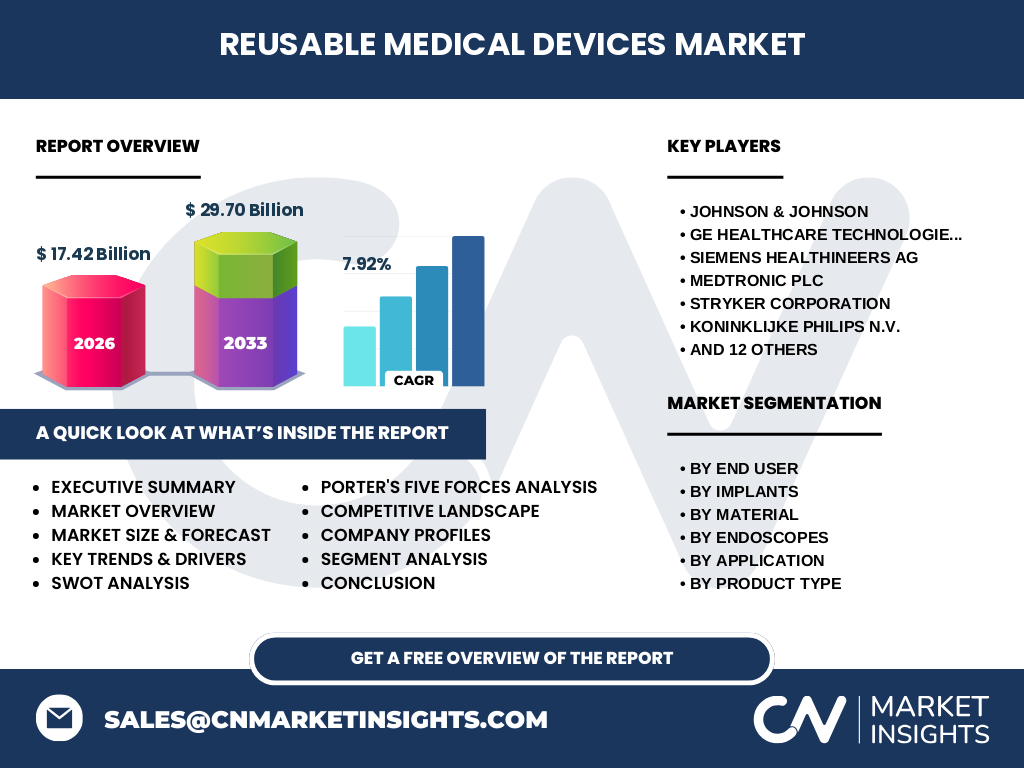
Our comprehensive evaluation confirms that the Reusable Medical Devices Market is poised for robust expansion, reaching a projected valuation of 29.70 Billion by 2033 from its 2026 baseline. Exhibiting a steady compound annual growth rate of 7.92%, the market is driven by rising chronic disease prevalence, technological advancements in rigid and flexible endoscopes, and strict hospital budgetary constraints favoring durability. Stakeholders must prioritize sustainable material sourcing and advanced reprocessing compliance to capture high-margin opportunities across global clinical settings.
Market Forecast and Valuation Trajectory (2027-2033)
Based on our research, the Reusable Medical Devices Market market size will scale rapidly from 17.42 Billion in 2026 to 29.70 Billion by 2033, achieving a solid 7.92% CAGR. This forecast is underpinned by accelerating capital equipment upgrades across ambulatory surgical centers and expanding healthcare infrastructure in emerging economies. Diagnostic and monitoring equipment segments will experience heightened demand as healthcare facilities prioritize early detection technologies integrated with reusable imaging and electrodiagnostic platforms.
Segmentation Analysis Across Applications, Materials, and End Users
Our Reusable Medical Devices Market segmentation breaks down across diverse clinical pillars: Product Type spans endoscopes, surgical instruments, implants, and diagnostic equipment; Material covers stainless steel, titanium, silicone, and medical-grade plastics; End User isolates hospitals, ambulatory surgical centers, and diagnostic laboratories. Furthermore, specialized categories include Orthopedic, Dental, and Cardiovascular Implants alongside advanced surgical sub-instruments like cutting, grasping, and retracting tools, ensuring tailored strategic targeting for device manufacturers.
Geographic Distribution and Regional Performance Overview
The Reusable Medical Devices Market exhibits pronounced regional variance, with North America maintaining dominant market share due to advanced healthcare infrastructure, high surgical volumes, and stringent hospital hygiene standards. Meanwhile, the Asia-Pacific region represents the fastest-growing frontier, propelled by medical tourism, government investments in hospital modernization across China and India, and rising disposable incomes. Europe maintains a steady trajectory, heavily influenced by stringent EU Medical Device Regulation (MDR) compliance and a cultural shift toward sustainable healthcare supply chains.
In-Depth Regional Review of Key Healthcare Hubs
A closer examination of the Reusable Medical Devices Market industry trends within North America underscores heavy reliance on centralized reprocessing facilities serving multi-site health systems. In contrast, European markets face intense pricing pressures from national health authorities, compelling manufacturers like B. Braun Melsungen AG and Siemens Healthineers AG to emphasize lifecycle durability and repair services. Emerging markets in Latin America and the Middle East focus heavily on expanding basic surgical and diagnostic equipment access through public-private healthcare partnerships.
Strategic Positioning of Leading Industry Participants
Key market participants in the Reusable Medical Devices Market leverage distinct competitive moats to defend their market share. Boston Scientific Corporation and CONMED Corporation focus on advanced visualization and minimally invasive surgical tools, while GE HealthCare Technologies Inc. and Koninklijke Philips N.V. anchor their strength in diagnostic and monitoring equipment ecosystems. STERIS plc and Richard Wolf GmbH dominate specialized sterilization and endoscopic precision engineering, securing deep customer loyalty through integrated maintenance and compliance support services.
Porter's Five Forces Assessment of Competitive Pressures
Evaluating the Reusable Medical Devices Market through Porter's framework reveals moderate-to-high competitive rivalry among established giants like Medtronic plc and Johnson & Johnson. Supplier power remains balanced due to the specialized nature of medical-grade titanium and high-purity polymers, while buyer power is elevated via powerful hospital group purchasing organizations. Threat of substitution is tempered by the high clinical reliability of stainless steel and titanium devices over nascent single-use alternatives, though regulatory hurdles maintain formidable barriers to entry.
SWOT Analysis of the Reusable Medical Devices Market
Our strategic SWOT assessment highlights core strengths in high material durability and robust clinical trust, contrasted with weaknesses involving complex, labor-intensive sterilization protocols. Significant opportunities emerge in smart surgical tray tracking and expansion within Asia-Pacific ambulatory surgical centers. Threats primarily involve stringent regulatory compliance costs under updated FDA and EU MDR frameworks, alongside potential material supply chain disruptions affecting medical-grade stainless steel and silicone procurement.
Value Chain Analysis from Raw Materials to End-Users
The value chain of the Reusable Medical Devices Market initiates with raw material extraction—securing medical-grade titanium, stainless steel, glass, and silicone. Midstream activities involve precision manufacturing, biocompatibility testing, and regulatory validation by bodies like the FDA. Downstream logistics encompass distribution through major maritime ports and localized medical supply chains directly to hospitals, diagnostic laboratories, and ambulatory surgical centers, culminating in rigorous post-market clinical surveillance and specialized hospital reprocessing operations.
Strategic Investment Insights and High-Potential Areas
Our analysis indicates that high-potential investment in the Reusable Medical Devices Market should target smart surgical instrumentation integrated with IoT tracking and advanced sterilization-compatible polymers. Venture capital and private equity firms are advised to back emerging innovators specializing in robotic-assisted surgical tools and eco-friendly reprocessing technologies. Facilities upgrading their cardiovascular, orthopedic, and spinal implant portfolios will yield superior returns as aging global demographics drive sustained demand for advanced surgical interventions.
Conclusion and Key Strategic Takeaways
In summary, the Reusable Medical Devices Market represents a resilient, high-value sector projected to expand from 17.42 Billion in 2026 to 29.70 Billion by 2033 at a 7.92% CAGR. Success for industry participants hinges on navigating complex regulatory pathways, embracing digital tracking innovations, and delivering superior lifecycle durability. Companies that proactively align their product lines with sustainable manufacturing and advanced sterilization standards will capture disproportionate market share in this evolving healthcare landscape.
Research Methodology for Baseline Estimates and Validation
Our research methodology for the Reusable Medical Devices Market analysis utilizes a rigorous triangulation model combining primary stakeholder interviews with C-suite executives, secondary macroeconomic data, and trade registry statistics. Baseline estimates for 2026 and forecasts up to 2033 (reaching 29.70 Billion) are cross-referenced with financial reports from key entities like Smith & Nephew plc, Hoya Corporation, and Integra LifeSciences Holdings Corporation. This multi-layered approach ensures high data fidelity across all product, material, and end-user segments.
Scope of the Report and Coverage Parameters
This comprehensive report scope covers the global Reusable Medical Devices Market across ten distinct product, material, and application segmentations, including surgical instruments, endoscopes, and monitoring equipment. Geographic evaluations encompass North America, Europe, Asia-Pacific, and Rest of World. While providing granular insights into market sizing through 2033, limitations include unpredictable macroeconomic trade policy shifts and localized healthcare budget volatility that may temporarily influence regional procurement cycles across hospital networks and diagnostic laboratories.
Recent Developments and Strategic Industry Moves
Recent developments in the Reusable Medical Devices Market industry trends feature strategic mergers, eco-friendly product launches, and digital health partnerships. Major industry leaders such as Stryker Corporation and Siemens Healthineers AG have recently unveiled advanced reprocessing validation initiatives and AI-enhanced diagnostic equipment platforms. These strategic maneuvers demonstrate an industry-wide commitment to enhancing asset longevity, reducing hospital operating costs, and complying with increasingly stringent global medical device regulations.