Market overview and structural scope of the Digital Therapeutics DTX For Mental Health Market
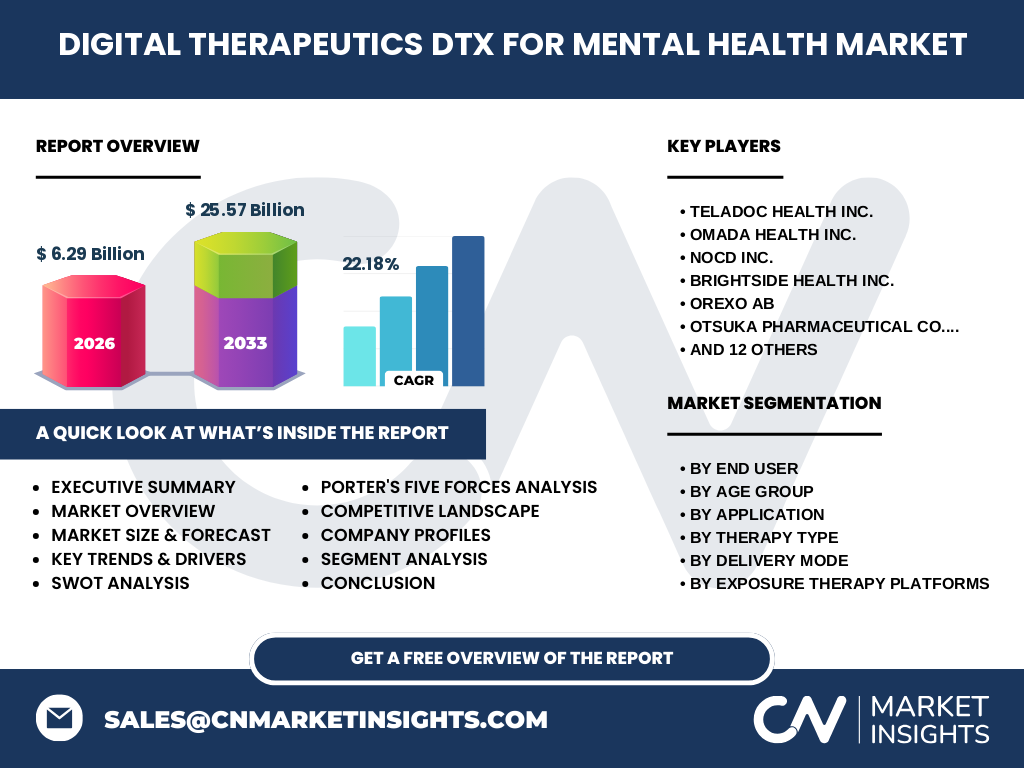
The Digital Therapeutics DTX For Mental Health Market represents a paradigm shift in psychiatric care, delivering evidence-based software interventions to prevent, manage, and treat behavioral conditions. Valued at $6.29 Billion in 2026, the sector bridges clinical gaps through platforms like Cognitive Behavioral Therapy Based Digital Therapeutics and Conversational Artificial Intelligence Or Chatbot Therapeutics, requiring rigorous validation by regulatory bodies such as the FDA.
Structural Growth Drivers and Market Restraints
Our analysis indicates that soaring demand for remote psychiatric monitoring drives expansion, while stringent reimbursement hurdles act as primary restraints. Key industry participants like Orexo AB and Otsuka Pharmaceutical Co. Ltd. navigate these barriers by leveraging clinical trial data. Meanwhile, data privacy mandates like HIPAA present logistical compliance challenges across corporate wellness programs.
Emerging Adoption Patterns and Industry Trends
The shift toward integrated virtual reality phobia treatment systems and wearable-enabled stress reduction applications is transforming clinical workflows. Based on our research, providers increasingly favor Software As A Service models that integrate seamlessly into hospital electronic health records, enhancing patient engagement and longitudinal symptom tracking.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic dramatically accelerated telehealth adoption, pushing digital mental health solutions from peripheral pilots into frontline care. COVID-19 created an unprecedented surge in depression and anxiety management applications. The post-pandemic recovery trajectory shows sustained institutional backing, steering the sector toward robust long-term monetization.
Competitive Benchmarking and Strategic Dynamics
Competitive intensity is escalating as specialized innovators challenge established pharmaceutical giants. Click Therapeutics Inc. and Big Health Ltd. utilize proprietary algorithms to capture market share, while Teladoc Health Inc. and Omada Health Inc. leverage expansive enterprise distribution networks to secure corporate wellness contracts.
Executive Summary of Key Analytical Findings
Our executive evaluation confirms explosive commercial momentum, projecting the market to surge from $6.29 Billion in 2026 to $25.57 Billion by 2033 at a 22.18% CAGR. Growth is heavily concentrated in pediatric and adult behavioral coaching segments, demanding agile product development strategies.
Market Forecast Projections from 2027 to 2033
The data suggests exceptional financial expansion ahead, with the market scaling from 2027 through 2033 to reach $25.57 Billion. Achieving this trajectory requires sustained venture investment and wider insurance reimbursement codes for conversational AI and neurocognitive training therapeutics.
Comprehensive Segmentation Breakdown
The ecosystem is segmented by end-users (Hospitals, Clinics, Corporate Wellness Programs, Individuals), age groups (Geriatric, Pediatric, Adolescent, Adult), and therapy types. Cognitive Behavioral Therapy Based Digital Therapeutics and mindfulness platforms lead adoption, catering to diverse clinical pathways and self-guided user preferences.
Geographic Distribution and Regional Performance
North America dominates revenue generation due to advanced healthcare IT infrastructure and favorable reimbursement frameworks. However, the Asia-Pacific region is emerging as a high-growth frontier, driven by smartphone penetration and government-backed mental health initiatives targeting urban corporate workforces.
In-Depth Regional Market Review
Regional analysis highlights North America as the primary revenue anchor, supported by early adopters among major US health plans. Concurrently, European markets like Germany enforce strict BfArM fast-track digital health application (DiGA) processes, favoring localized players such as GAIA AG and MindNet GmbH.
Strategic Positioning of Leading Companies
Industry leaders deploy distinct differentiation strategies. NOCD Inc. focuses on obsessive-compulsive disorder therapy platforms, whereas Woebot Health Inc. pioneers AI-driven relational coaching. Limbic AI Ltd. and Brightside Health Inc. optimize clinical triage pipelines, enhancing referral efficiencies for partner health systems.
Porter's Five Forces Industry Assessment
Rivalry is intense among established wellness apps, while the threat of substitution remains moderate given the clinical validation required for prescription DTx. Bargaining power of buyers is high among enterprise payers, whereas supplier power is low due to abundant software development talent pools.
SWOT Analysis of the Digital Therapeutics Landscape
Strengths include scalable delivery and continuous patient monitoring. Weaknesses involve high customer acquisition costs. Opportunities lie in pediatric behavioral crisis management and employer-sponsored wellness expansion. Threats center on cybersecurity vulnerabilities and evolving regulatory compliance mandates from agencies like the FDA.
Value Chain Analysis and Industry Structure
The value flow originates with academic psychiatric research and software engineering, passing through clinical validation trials and regulatory clearance. It culminates in distribution via hospitals, clinics, and direct-to-consumer mobile applications, with value captured primarily by platforms demonstrating proven clinical outcomes.
Strategic Investment Insights and High-Potential Areas
Investors should prioritize platforms offering neurocognitive training therapeutics and substance use recovery applications, as these address high-burden clinical needs. Companies integrating virtual reality phobia treatment systems represent lucrative targets for venture capital deployment.
Conclusion and Strategic Takeaways
The market offers transformative commercial opportunities for stakeholders who successfully bridge clinical rigor with consumer-grade software experiences. Achieving market leadership requires navigating regulatory pathways and securing robust enterprise partnerships across corporate wellness ecosystems.
Proprietary Research Methodology
Our baseline estimates are triangulated by synthesizing secondary macroeconomic indicators, trade registry databases, and primary stakeholder interviews with clinical psychiatrists, payers, and C-level executives from key firms like WellDoc Inc. and Meru Health Inc. to ensure absolute market accuracy.
Scope of the Report and Analytical Parameters
This report covers global revenue performance, segmentation dynamics, and competitive benchmarking for the Digital Therapeutics DTX For Mental Health Market from 2026 to 2033. Exclusions apply to unvalidated wellness apps lacking clinical trial data or regulatory classification.
Recent Industry Developments and Strategic Moves
Recent milestones include strategic acquisitions and pivotal clinical trial readouts by innovators like Freespira Inc. and CogniFit Inc. Partnerships between tech startups and traditional pharmaceutical distributors are increasingly common, aimed at expanding market access for prescription digital therapeutics.