What is the market overview of the Port Congestion Analytics Platforms Market?
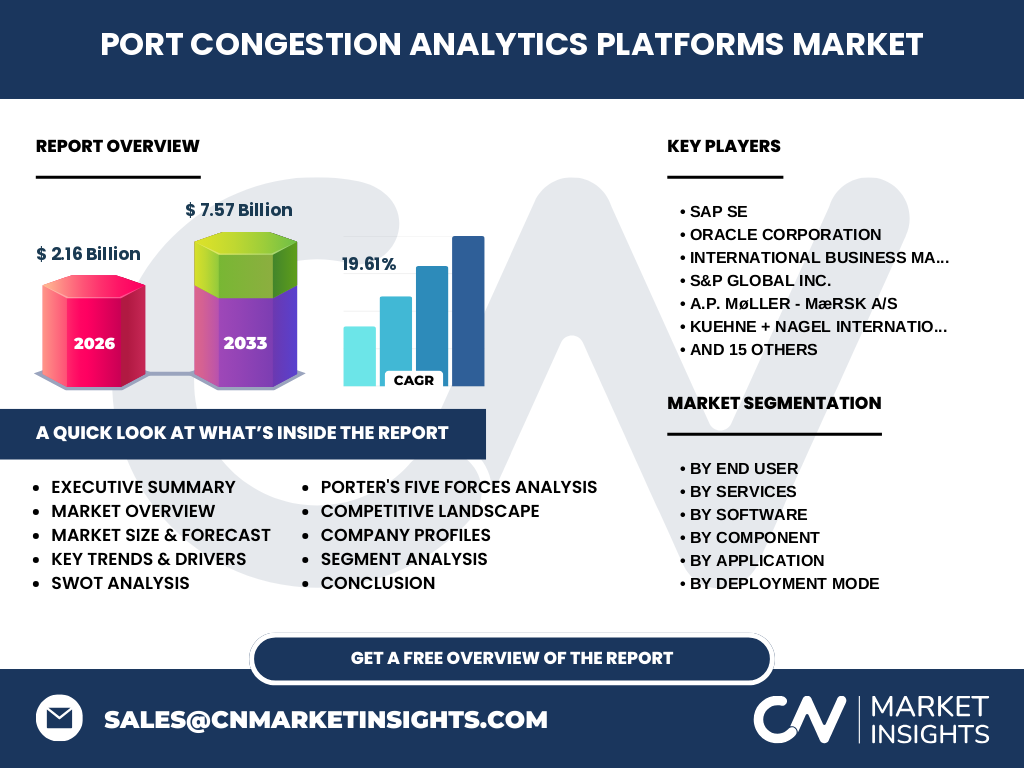
Our analysis indicates that the Port Congestion Analytics Platforms Market is valued at $2.16 Billion in 2026. This specialized ecosystem empowers terminal operators, port authorities, and ocean carriers to mitigate critical bottlenecks caused by surging container volumes, strict environmental regulations imposed by the International Maritime Organization (IMO), and labor disputes at major global gateways like the Port of Los Angeles and Port of Rotterdam.
Structural Growth Drivers and Market Restraints
The market is propelled by chronic supply chain volatility and the urgent need for real-time visibility software, yet restrained by legacy IT infrastructure at smaller regional ports. Digital transformation initiatives are heavily constrained by high upfront capital expenditure requirements for cloud-based and on-premises software integration across heterogeneous stakeholder systems.
Emerging Trends and Growth Patterns in Port Congestion Analytics Platforms
The shift toward predictive congestion analytics software and API-driven multimodal supply chain visibility is redefining operational benchmarks. Industry leaders are increasingly adopting machine learning algorithms to forecast berth availability weeks in advance, effectively reducing idle vessel times and minimizing bunker fuel consumption during unexpected anchorage delays.
How did COVID-19 impact the Port Congestion Analytics Platforms Market and recovery trajectory?
The pandemic exposed severe structural vulnerabilities in maritime logistics, creating historic vessel queue records outside major container hubs. This unprecedented disruption accelerated enterprise software adoption as stakeholders urgently required data visualization and reporting software to track stranded cargo, establishing a robust post-pandemic recovery trajectory centered on supply chain resilience.
Competitive Landscape and Strategic Dynamics
The competitive landscape features a mix of enterprise tech giants like SAP SE, IBM Corporation, and specialized logistics visibility innovators such as project44 Inc., FourKites Inc., and Portcast Pte. Ltd. Market concentration is moderate to high, with major ocean carriers like A.P. Møller - Mærsk A/S developing proprietary analytics while partnering with specialized software providers to secure competitive advantages.
Executive Summary: Key Findings
Our comprehensive research reveals that the Port Congestion Analytics Platforms Market is scaling rapidly, driven by digitalization imperatives across global supply chains. Key findings highlight that data analytics and insights services, alongside predictive congestion software, represent the highest-margin opportunities for technology vendors navigating complex port ecosystems.
What is the market forecast for the Port Congestion Analytics Platforms Market from 2027 to 2033?
Based on our econometric modeling, the market is projected to surge from $2.16 Billion in 2026 to reach $7.57 Billion by 2033. This remarkable expansion unfolds at a compound annual growth rate (CAGR) of 19.61%, fueled by escalating demand for real-time port monitoring software and automated terminal traffic management.
Segmentation Analysis of the Port Congestion Analytics Platforms Market
The market segments neatly across multiple dimensions. By component, it divides into Software and Services. Software deployments include Real Time Port Monitoring Software, Predictive Congestion Analytics Software, Vessel Traffic Optimization Software, Supply Chain Visibility Software, and Data Visualization And Reporting Software. End users range from Port Authorities and Shipping Companies to Logistics Providers and Terminal Operators.
Geographic Distribution and Regional Performance
Regional performance varies significantly, dictated by container throughput volumes and infrastructure modernization budgets. Asia-Pacific dominates due to massive cargo handling at mega-ports in Shanghai and Singapore, while North America and Europe exhibit strong demand driven by stringent environmental compliance and technological retrofitting at aging terminal facilities.
In-Depth Regional Review
In North America, congestion at the Ports of Los Angeles and Long Beach catalyzed early adoption of predictive analytics. Meanwhile, European markets focus heavily on green shipping corridors, integrating platforms from innovators like Xeneta AS and Veson Nautical LLC to optimize vessel speeds and reduce carbon emissions in alignment with European Union maritime regulations.
Company Profiles and Strategic Positioning
Industry participants deploy distinct strategies: Oracle Corporation and S&P Global Inc. leverage enterprise-grade macroeconomic data integration, whereas niche players like Windward Ltd. and MarineDigital GmbH focus on specialized maritime risk scoring and real-time berth optimization. Meanwhile, forwarders like Kuehne + Nagel International AG embed these platforms directly into customer-facing portals.
Porter's Five Forces Analysis
The bargaining power of buyers is moderate to high due to numerous competing visibility providers, while supplier power remains low given the abundance of cloud infrastructure and AIS satellite data streams. Threat of substitution is minimal, but competitive rivalry is intense among tech giants and specialized startups vying for maritime market share.
SWOT Analysis of the Industry
Strengths include high predictive accuracy powered by advanced IoT and AIS data feeds; weaknesses involve high integration friction with legacy port hardware. Opportunities lie in expanding managed analytics services for mid-tier ports, while threats include rising cybersecurity vulnerabilities targeting critical maritime operational technology networks.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw data generation—utilizing satellite AIS transponders, IoT sensors, and customs registries—through cloud software processing layers managed by vendors like Everstream Analytics Inc. and Vizion API Inc., ultimately delivering actionable congestion insights to terminal operators and beneficial cargo owners.
Investment Insights and High-Potential Areas
Investors should direct capital toward companies offering integrated platform implementation and consulting services, as ports struggle with internal technical expertise. High-potential areas include predictive congestion software that interfaces seamlessly with existing Terminal Operating Systems (TOS) to reduce demurrage and detention costs.
Conclusion and Key Takeaways
The Port Congestion Analytics Platforms Market represents a critical frontier in global logistics digitization. With a projected valuation of $7.57 Billion by 2033, stakeholders must prioritize scalable cloud deployments, predictive software adoption, and strategic API integrations to maintain competitive advantage in volatile maritime trade corridors.
Research Methodology
Our rigorous research methodology triangulates bottom-up port throughput metrics, top-down macroeconomic trade forecasts, and extensive primary interviews with C-level executives across major shipping lines, terminal operators, and port authorities. Baseline 2026 estimates are cross-referenced with maritime registry datasets and financial disclosures from key market participants.
Scope of the Report and Limitations
This report covers global deployment of port congestion analytics software and associated services across cloud-based and on-premises architectures. Limitations include potential data latency in developing regional ports with non-standardized electronic data interchange (EDI) protocols and private terminal operator confidentiality constraints.
Recent Industry Developments and Strategic Moves
Recent market activity is characterized by aggressive M&A and strategic partnerships. For instance, supply chain visibility providers like Shippeo and Descartes Systems Group Inc. have expanded their ocean tracking capabilities through targeted acquisitions and API integrations with real-time vessel finders, enhancing predictive accuracy for enterprise shippers worldwide.