What is the market overview of the Lutetium-177 Supply Market?
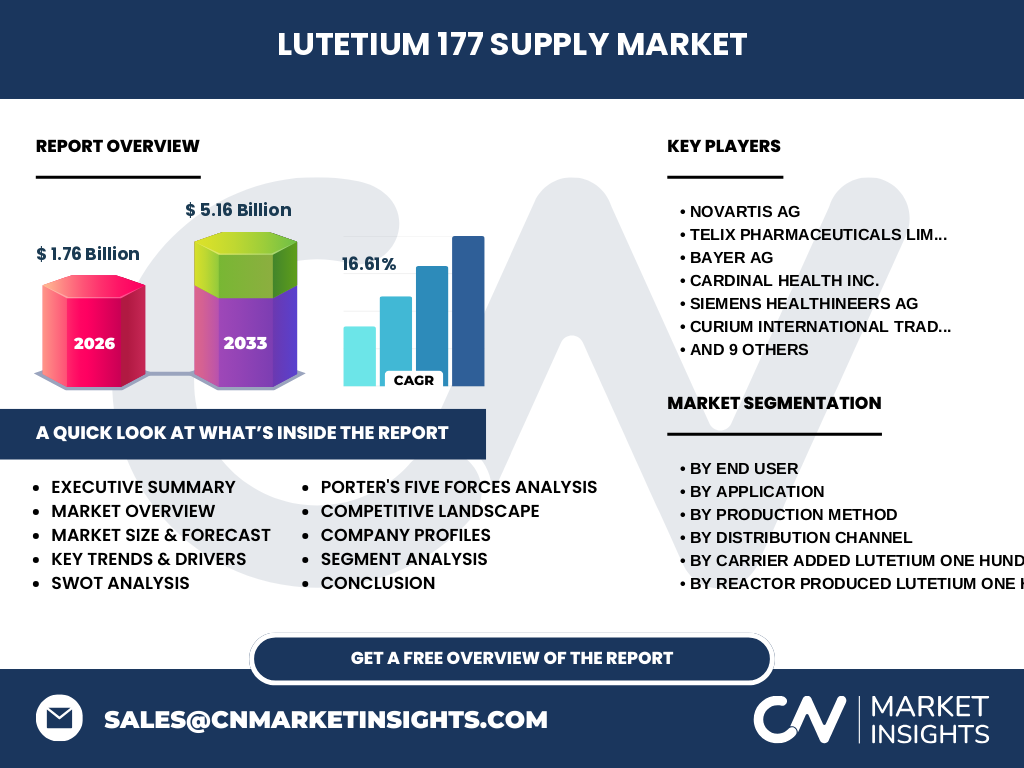
Our analysis indicates that the Lutetium-177 Supply Market is valued at 1.76 Billion in 2026. This sector encompasses the production, processing, and distribution of medical isotopes vital for targeted radionuclide therapy. Regulatory oversight by bodies like the IAEA and FDA tightly governs this high-precision supply chain.
Key market drivers, restraints, challenges, and opportunities shaping Lutetium-177 Supply Market
Growth is propelled by rising oncology cases and demand for precision theranostics. However, severe restraints involve short radioisotope half-lives and complex nuclear reactor logistics. Opportunities lie in scaling cyclotron production and expanding Direct Supply Agreements with global hospital networks.
Emerging trends and growth patterns in Lutetium-177 Supply Market
The shift toward Non Carrier Added Lutetium One Hundred Seventy-Seven is dominating industry trends due to its higher specific activity. ITM Isotope Technologies Munich SE and Novartis AG are leading this transition, optimizing clinical efficacy for neuroendocrine and prostate cancer treatments.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted transport logistics and reactor maintenance schedules. Our research shows the market rebounded strongly as nuclear medicine departments resumed clinical trials. Supply chain resilience improved through localized Research Supply Networks and diversified carrier-added processing.
Competitive Benchmarking and Market Concentration
The Lutetium-177 Supply Market features high concentration among vertically integrated radiopharmaceutical pioneers. Novartis AG, Bayer AG, and Curium International Trading B.V. dominate commercial distribution, leveraging strategic acquisitions and robust Radiopharmaceutical Distributors to secure global market share.
Executive Summary of the Lutetium-177 Supply Market
Driven by surging oncology applications, the Lutetium-177 Supply Market is projected to reach 5.16 Billion by 2033. Achieving a robust 16.61% CAGR from 2027 to 2033, the sector requires urgent capital investment in high-purity reactor infrastructure and accelerator technologies.
Market Forecast from 2027 to 2033
Our forecasting models project aggressive expansion from 2026 baseline figures of 1.76 Billion to 5.16 Billion by 2033. This expansion is underpinned by a stellar 16.61% CAGR, fueled by commercialization of novel prostate and bone metastasis radioligand therapies.
Segmentation Analysis across Applications and End Users
Segmentation spans end-users like Hospitals, Specialty Cancer Clinics, and Research Institutes. Applications are anchored by Neuroendocrine Tumor Treatment and Prostate Cancer Treatment. Production splits between Reactor Produced and Cyclotron Produced variants, satisfying diverse clinical and research demands globally.
Regional Market Analysis and Geographic Distribution
North America dominates the Lutetium-177 Supply Market analysis due to advanced healthcare infrastructure and rapid FDA approvals. Europe follows closely, anchored by prominent research reactors and institutional facilities like NRG PALLAS B.V. and POLATOM driving regional isotope availability.
In-Depth Regional Review of Supply Constraints
Logistical bottlenecks heavily dictate regional performance. European producers leverage localized nuclear infrastructure, while Asia-Pacific markets face cold-chain transit hurdles for short half-life isotopes. Regional players must forge strategic alliances with air cargo hubs to ensure timely delivery to clinical centers.
Company Profiles and Strategic Positioning
Industry leaders exhibit distinct competitive moats. Telix Pharmaceuticals Limited and Isotopia Molecular Imaging Ltd. focus on specialized radiotracers, while BWX Technologies Inc. and State Atomic Energy Corporation Rosatom secure upstream reactor production capabilities, ensuring feedstock stability.
Porter's Five Forces Analysis of the Sector
Threat of new entrants remains low due to stringent nuclear licensing and high capital expenditure. Bargaining power of suppliers is moderate, constrained by specialized reactor dependencies. Competitive rivalry is fierce among established pharma giants scaling theranostic pipelines.
SWOT Analysis of Lutetium-177 Supply Market
Strengths include high therapeutic efficacy in oncology. Weaknesses involve radioactive decay constraints during transport. Opportunities lie in emerging cyclotron technologies by innovators like Nusano Inc. Threats include regulatory delays and potential neutron flux disruptions at aging research reactors.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with enriched ytterbium-176 target procurement, followed by neutron irradiation in nuclear reactors or proton bombardment in cyclotrons. Post-processing refines medical-grade isotopes before passing through specialized Radiopharmaceutical Distributors to hospitals.
Investment Insights and High-Potential Areas
Investors should target non-carrier-added production technologies and localized cyclotron facilities. Companies investing in automated dispensing and supply chain redundancy will capture outsized margins as clinical demand accelerates through 2033.
Conclusion and Key Takeaways for Stakeholders
The Lutetium-177 Supply Market represents a high-growth frontier in nuclear medicine. With a projected valuation of 5.16 Billion by 2033, stakeholders must prioritize reliable irradiation partnerships and advanced logistics to mitigate decay-related supply risks.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with nuclear medicine executives, and secondary macroeconomic health expenditure indicators. This multi-tiered approach ensures high-fidelity market sizing.
Scope of the Report and Coverage Parameters
This report covers global supply dynamics, production methodologies, and regional performance from 2026 to 2033. Excluded from this scope are grey-market distribution channels and non-medical industrial applications of lutetium isotopes.
Recent Developments in the Industry Landscape
Recent milestones feature strategic supply agreements forged by Siemens Healthineers AG and Eckert & Ziegler SE. Furthermore, investments by Framatome SAS into medical isotope generation signal robust upstream confidence in long-term reactor capacity expansion.