What is the market overview and industry significance of the Virtual Care Platforms Market?
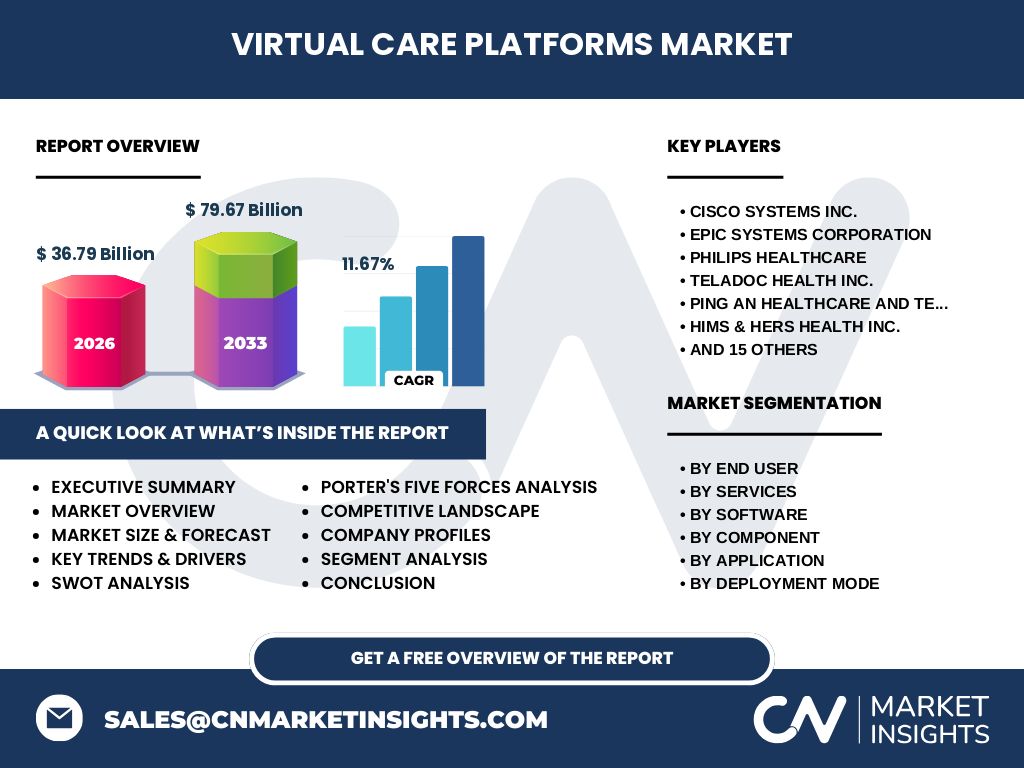
Our analysis indicates that the Virtual Care Platforms Market reaches a valuation of 36.79 Billion in 2026. This sector encompasses telehealth management, remote monitoring, and clinical software governed by strict compliance frameworks like HIPAA and GDPR, fundamentally reshaping global healthcare delivery models.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
The market is propelled by rising chronic disease burdens and physician shortages, though constrained by fragmented reimbursement policies across regions. Opportunities abound for innovators integrating AI-assisted consultation services and cloud-based telehealth platforms to scale virtual care securely.
Emerging trends and growth patterns in Virtual Care Platforms Market
The shift toward asynchronous care and ambient clinical intelligence is redefining industry standards. Cloud-based deployments and mobile health applications are gaining rapid traction, allowing providers to scale digital patient engagement efficiently without heavy on-premises hardware costs.
COVID-19 impact analysis and recovery trajectory
The pandemic acted as an unprecedented catalyst, forcing regulatory bodies to temporarily relax cross-state licensing and telehealth reimbursement restrictions. Post-COVID, the recovery trajectory has transitioned from emergency triage to permanent digital-first infrastructure integration.
Competitive Benchmarking and Strategic Dynamics
Industry leaders like Teladoc Health Inc., Amwell, and Epic Systems Corporation dominate through enterprise EHR integrations. Meanwhile, specialized players such as Omada Health Inc. and TytoCare Ltd. carve out niches in chronic management and hardware-enabled remote monitoring.
Executive Summary: High-Level Synthesis of Research Findings
Driven by robust clinical adoption, the Virtual Care Platforms Market industry trends highlight a critical pivot toward hybrid deployment models. Strategic investments are heavily skewed toward AI-assisted consultations and secure healthcare communication software to reduce clinician burnout.
Market forecast and growth projections from 2027 to 2033
Our research forecasts the market to surge from 36.79 Billion to 79.67 Billion by 2033, expanding at a robust CAGR of 11.67%. This accelerated expansion is underpinned by sustained patient demand for remote chronic disease management.
Segmentation analysis across end-users, services, software, and components
The market is segmented by end-users (Hospitals, Home Care, Payers), services, software (Teleconsultation, Patient Engagement, Workflow Management), and components. Software solutions command the highest share, driven by the necessity for secure healthcare communication.
Regional market analysis and geographic performance distribution
North America retains the dominant revenue share due to advanced digital infrastructure and favorable reimbursement codes. Meanwhile, the Asia-Pacific region exhibits the fastest growth, propelled by expanding smartphone penetration and government-backed digital health initiatives.
In-depth regional review of key markets
In North America, strict adherence to FDA and HIPAA regulations shapes platform architectures. Conversely, European markets navigate fragmented national health systems, favoring open-API cloud-based telehealth platforms that integrate easily with localized public health databases.
Company profiles and strategic positioning
Key ecosystem participants include Cisco Systems Inc. providing secure infrastructure, Zocdoc Inc. optimizing patient scheduling, and Hims & Hers Health Inc. targeting direct-to-consumer wellness. Each leverages distinct go-to-market strategies to capture specific demographic segments.
Porter's Five Forces analysis of the competitive landscape
Bargaining power of buyers remains moderate to high as large hospital networks demand custom integrations. Threat of new entrants is mitigated by high regulatory barriers, while rivalry among established telehealth giants drives continuous software feature innovation.
SWOT analysis of the Virtual Care Platforms Market
Strengths include scalability and improved patient access; weaknesses involve interoperability hurdles with legacy EHRs. Opportunities lie in artificial intelligence integration, while threats stem from complex cybersecurity vulnerabilities and evolving data privacy legislation.
Value chain analysis from technology developers to end-users
The value chain flows from cloud infrastructure and software developers to platform aggregators, healthcare providers, and ultimately end-users. Capturing maximum value requires robust integration capabilities that bridge clinical workflows with patient-facing mobile apps.
Investment insights and high-potential areas
High-potential investment pockets include virtual chronic disease management and AI-assisted consultation tools. Investors should prioritize platforms offering seamless hybrid deployment capabilities that cater to both institutional hospital networks and decentralized home care settings.
Conclusion and key takeaways for stakeholders
The data demonstrates that virtual care is no longer a temporary alternative but a permanent pillar of modern healthcare delivery. Organizations must invest in scalable, secure software ecosystems to maintain competitive advantage through 2033.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining proprietary trade registry data, primary stakeholder interviews with Chief Medical Information Officers, and secondary macroeconomic indicators from global health organizations to ensure absolute data integrity.
Scope of the report, coverage parameters, and limitations
This report covers global deployment models, software types, and service verticals from 2026 through 2033. Limitations include potential unforeseen regulatory shifts in emerging markets and localized reimbursement policy alterations affecting regional adoption speeds.
Recent developments, partnerships, and strategic moves
Recent industry momentum is defined by strategic partnerships between tech giants and healthcare providers, alongside product launches featuring generative AI medical scribes and advanced remote patient monitoring kits from innovators like TytoCare Ltd.