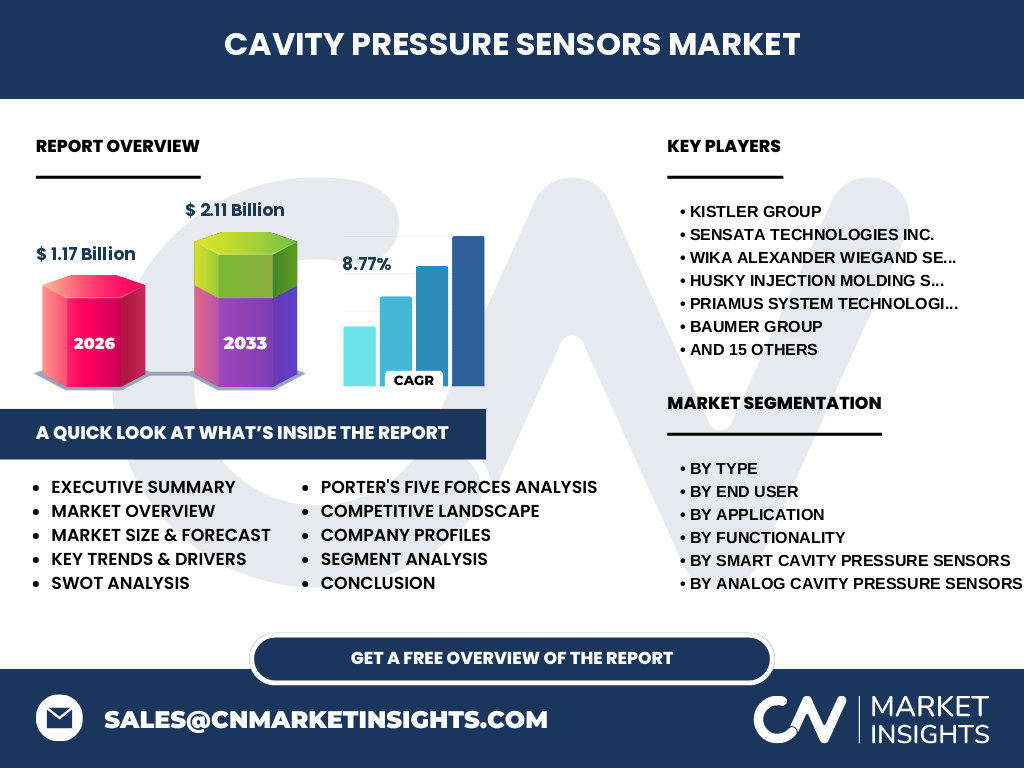
Market Overview of the Cavity Pressure Sensors Market
Our analysis indicates that the Cavity Pressure Sensors Market reaches a valuation of $1.17 Billion in 2026. This specialized sector underpins precision injection molding by monitoring mold pressures in real time. Vital for automotive and pharmaceutical manufacturing, these tools ensure structural integrity and dimensional stability.
Structural Growth Drivers and Market Restraints
The market thrives on strict ISO and ASTM quality standards, driving demand for real-time monitoring sensors. However, high initial calibration costs and complex integration into legacy machinery act as notable restraints, challenging Original Equipment Manufacturers across major industrial hubs.
The Shift Toward Smart Manufacturing Technologies
Industry adoption is rapidly pivoting toward Internet Of Things Integrated Sensors and wireless enabled sensors. This shift enables predictive maintenance, drastically reducing costly downtime in high-throughput injection molding facilities handling advanced polymers and engineering resins.
COVID-19 Impact Analysis and Market Recovery
The pandemic severely disrupted global supply chains for raw piezo crystals and semiconductor components. Despite initial contraction, accelerated digital transformation and automated factory mandates fueled a robust recovery, pushing the Cavity Pressure Sensors Market toward long-term expansion.
Competitive Benchmarking and Industry Concentration
The landscape features intense rivalry among technical heavyweights. Kistler Group and Sensata Technologies Inc. lead with proprietary piezoelectric innovations, while WIKA Alexander Wiegand SE & Co. KG and Dynisco Europe GmbH maintain strong footholds in industrial process monitoring.
Executive Summary of Key Findings
Our research confirms robust expansion, projecting the market to surge from $1.17 Billion in 2026 to $2.11 Billion by 2033 at a CAGR of 8.77%. Growth concentrates heavily in smart sensor integration and automated quality assurance.
Cavity Pressure Sensors Market Forecast (2027 to 2033)
Driven by rising automation demands, the market is projected to expand from $1.17 Billion in 2026 to reach $2.11 Billion by 2033. This trajectory reflects an impressive CAGR of 8.77%, fueled by smart manufacturing initiatives worldwide.
Comprehensive Segmentation Analysis
The market segments by type into analog, digital, and smart variants. End users span Original Equipment Manufacturers, aftermarket, research institutions, and industrial users. Applications cover oil and gas, automotive, aerospace, and medical manufacturing, utilizing specialized functionality like process monitoring and quality control.
Geographic Distribution and Regional Market Performance
Regional performance mirrors automotive and medical manufacturing density. North America and Europe dominate through stringent regulatory mandates, while Asia-Pacific exhibits the fastest growth due to expanding automotive production lines in regional manufacturing epicenters.
In-Depth Regional Review and Local Constraints
European markets prioritize high-precision piezoelectric based sensors to meet stringent EU machinery directives. Meanwhile, Asia-Pacific hubs face localized logistical hurdles regarding sensor calibration infrastructure, yet outpace western regions in raw volume deployment across electronics manufacturing.
Strategic Positioning of Leading Companies
Firms like Husky Injection Molding Systems Ltd. and Priamus System Technologies integrate sensors directly into mold design. Meanwhile, Baumer Group and Gefran S.p.A. focus on robust digital output systems tailored for harsh industrial operating environments.
Porter's Five Forces Analysis of the Industry
Supplier power remains moderate due to specialized raw material requirements for strain gauges. Buyer power is high, driven by major automotive OEMs demanding customization, while intense competitive rivalry pushes continuous R&D in wireless and self-calibrating sensors.
SWOT Analysis of the Cavity Pressure Sensors Sector
Key strengths include high measurement accuracy and vital integration with Industry 4.0 frameworks. Weaknesses involve high sensor replacement costs. Opportunities lie in IoT integration, while threats stem from low-cost counterfeit sensor imports violating ISO standards.
Value Chain Analysis from Raw Materials to End-Users
The value chain begins with raw silicon and piezoelectric crystal sourcing, followed by precision machining by component specialists like Meusburger Georg GmbH & Co KG. Assembly and calibration lead to integration by mold makers, ultimately serving automotive and medical end-users.
Investment Insights and High-Potential Growth Areas
Investors should target developers of wireless enabled sensors and Internet Of Things Integrated Sensors. These segments offer superior margins and align directly with global manufacturing trends favoring predictive maintenance and automated quality assurance.
Conclusion and Strategic Takeaways
The Cavity Pressure Sensors Market industry trends highlight a definitive shift toward smart, connected ecosystems. Sustained by an 8.77% CAGR through 2033, market participants must invest heavily in microprocessor integration and digital output capabilities to capture high-value contracts.
Robust Research Methodology
Our baseline estimates are rigorously triangulated. We combine official trade registry data, primary stakeholder interviews with chief engineers at firms like RJG Inc. and Futaba Corporation, and secondary macroeconomic indicators from global manufacturing associations.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for cavity pressure sensors from 2026 through 2033. Limitations include restricted primary data access in certain emerging economies, mitigated through econometric modeling and cross-validation with established industry benchmarks.
Recent Industry Developments and Strategic Partnerships
Recent strategic moves involve major sensor manufacturers partnering with cloud analytics providers to enhance real-time data monitoring. Companies like Micro Sensor Co. Ltd. and Holykell Technology Co. Ltd. have launched advanced digital output units targeting high-precision medical molding.