What is the scope and definition of the Surgical Imaging Robots Market?
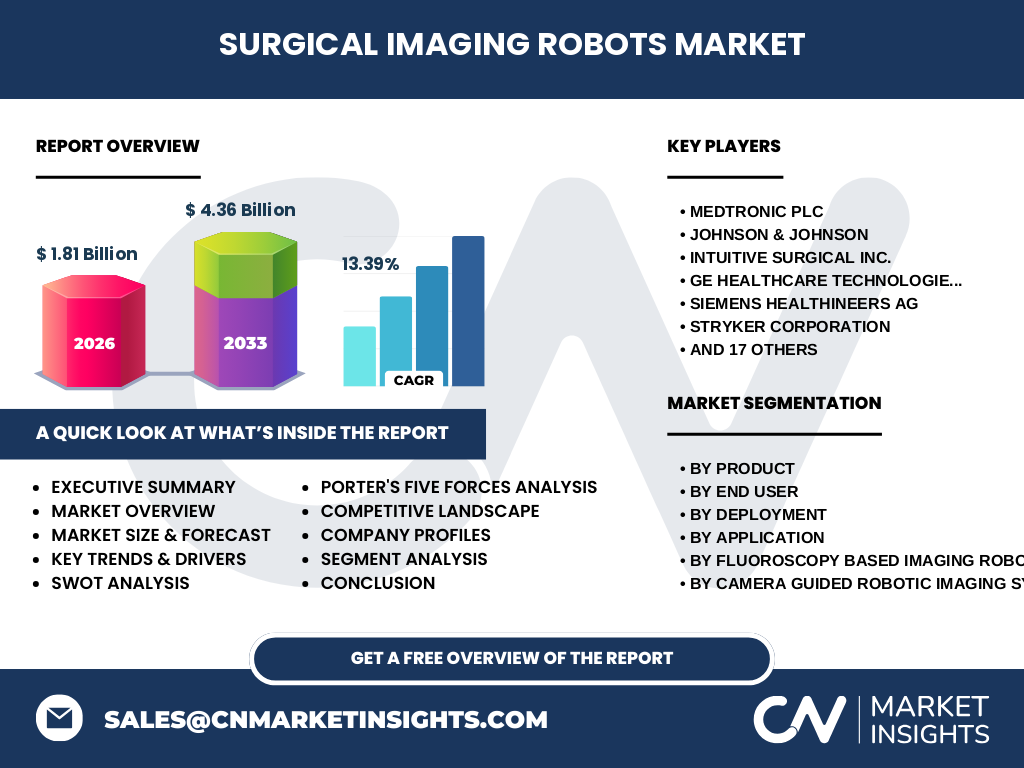
The Surgical Imaging Robots Market encompasses advanced intraoperative visualization platforms designed to enhance precision in complex procedures. Valued at 1.81 Billion in 2026, this sector integrates robotic automation with modalities like fluoroscopy, MRI, and CT, fundamentally transforming surgical navigation and patient outcomes across global healthcare infrastructures.
What are the primary structural growth drivers and market restraints?
Structural Growth Drivers include rising demand for minimally invasive interventions and surging adoption of AI-integrated systems. Conversely, market restraints feature prohibitive capital expenditure costs and stringent regulatory compliance hurdles enforced by agencies like the FDA, creating steep entry barriers for emerging manufacturers.
Which emerging trends are currently reshaping industry paradigms?
The industry is witnessing a rapid shift toward cloud connected systems and real-time navigation enabled by machine learning. Innovators are prioritizing low-dose imaging capabilities to minimize radiation exposure, heavily favoring technology leaders capable of embedding sophisticated software directly into legacy hospital workflows.
How did the COVID-19 pandemic impact market trajectories and recovery?
The pandemic severely disrupted elective procedures and delayed capital equipment procurement across hospitals globally. However, our analysis indicates a robust post-pandemic recovery, accelerated by urgent modernization demands and a renewed institutional focus on automated, remote-capable surgical environments.
Competitive Benchmarking: Who are the dominant market participants?
The market features intense competition among medtech titans like Medtronic plc, Intuitive Surgical Inc., and Stryker Corporation. These players leverage extensive distribution networks and robust R&D pipelines to maintain high market concentration, frequently acquiring specialized innovators to secure technological dominance.
Executive Summary of the Surgical Imaging Robots Market
Our comprehensive research reveals that the Surgical Imaging Robots Market is poised for extraordinary expansion, scaling from 1.81 Billion in 2026 to 4.36 Billion by 2033 at a remarkable CAGR of 13.39%, driven by technological convergence and rising clinical demand.
What is the projected financial trajectory from 2027 to 2033?
Driven by compounding adoption rates across specialty clinics and ambulatory surgical centers, the market will expand aggressively. The projected trajectory reaching 4.36 Billion by 2033 underscores a lucrative 13.39% CAGR, offering substantial upside for strategic investors targeting high-growth technological verticals.
How is the market structured across its core product and end-user segments?
Segmentation spans Artificial Intelligence Integrated, Camera Guided, and Fluoroscopy Based systems, deployed across hospitals and ambulatory surgical centers. Application-wise, the market covers orthopedic, neurological, and cardiovascular surgeries, with cloud-connected deployments driving modern scalability.
What geographic distribution patterns define the global landscape?
North America currently commands the largest revenue share due to advanced healthcare infrastructure and high reimbursement rates. Meanwhile, Asia-Pacific represents the fastest-growing region, fueled by expanding hospital modernization initiatives in emerging economies like China and India.
An In-Depth Regional Review of Adoption Constraints
Regional performance hinges on local reimbursement frameworks and regulatory clearance timelines. While Western markets rapidly absorb premium on premise systems and AI-driven navigation, developing regions face infrastructural bottlenecks, favoring cost-effective, portable fluoroscopy and computed tomography solutions.
Strategic Positioning of Leading Industry Companies
Industry giants such as Siemens Healthineers AG, GE HealthCare Technologies Inc., and Johnson & Johnson utilize targeted acquisitions to integrate proprietary robotics with advanced imaging. Smaller pure-play innovators like Stereotaxis Inc. and ClearPoint Neuro Inc. carve out niches via specialized neuro and vascular applications.
Porter's Five Forces Analysis of Competitive Intensity
Competitive rivalry is exceptionally high, dominated by established medtech multinationals. Supplier power remains moderate due to specialized optical and robotic components, while buyer power is constrained by high switching costs associated with integrated surgical ecosystems and extensive clinical training requirements.
SWOT Analysis of the Surgical Imaging Robots Sector
Key strengths include unprecedented surgical precision and workflow efficiency. Weaknesses involve high maintenance costs and complex integration. Opportunities lie in emerging cloud-connected platforms, while threats center on stringent cybersecurity regulations and protracted regulatory approval cycles.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from advanced rare-earth magnets and semiconductor sourcing through precision robotic manufacturing and software integration. Finished systems are distributed via specialized logistics channels to major hospitals and specialty clinics, demanding rigorous validation testing before clinical deployment.
High-Potential Investment Insights and Strategic Recommendations
Investors should direct capital toward firms specializing in AI-integrated motion tracking and machine learning-assisted navigation. Companies possessing scalable cloud-connected software architectures present prime acquisition targets for major medical device conglomerates seeking portfolio diversification.
Conclusion and Definitive Industry Takeaways
The Surgical Imaging Robots Market represents a high-growth frontier in medical technology. Achieving a 13.39% CAGR through 2033, the sector rewards stakeholders who successfully bridge advanced visualization modalities with intuitive robotic automation.
Research Methodology: Triangulating Baseline Estimates
Our baseline estimates are rigorously triangulated by combining proprietary primary stakeholder interviews with key opinion leaders, extensive trade registry data, and secondary macroeconomic indicators from global health organizations to ensure uncompromised analytical accuracy.
Scope of the Report and Analytical Parameters
This report covers global deployment metrics, product classifications, and regional forecasts from 2027 through 2033, establishing a baseline in 2026. Limitations include potential delays in regulatory approvals and localized healthcare budget fluctuations across developing markets.
Recent Developments in Strategic Partnerships and Product Launches
Recent market activity highlights aggressive R&D investments, with companies like Mendaera Inc. and CMR Surgical advancing handheld and modular robotic platforms. Strategic partnerships focusing on AI integration and real-time navigation continue to dominate corporate announcements.