Market overview and industry significance of the Airline Route Profitability Analytics Market
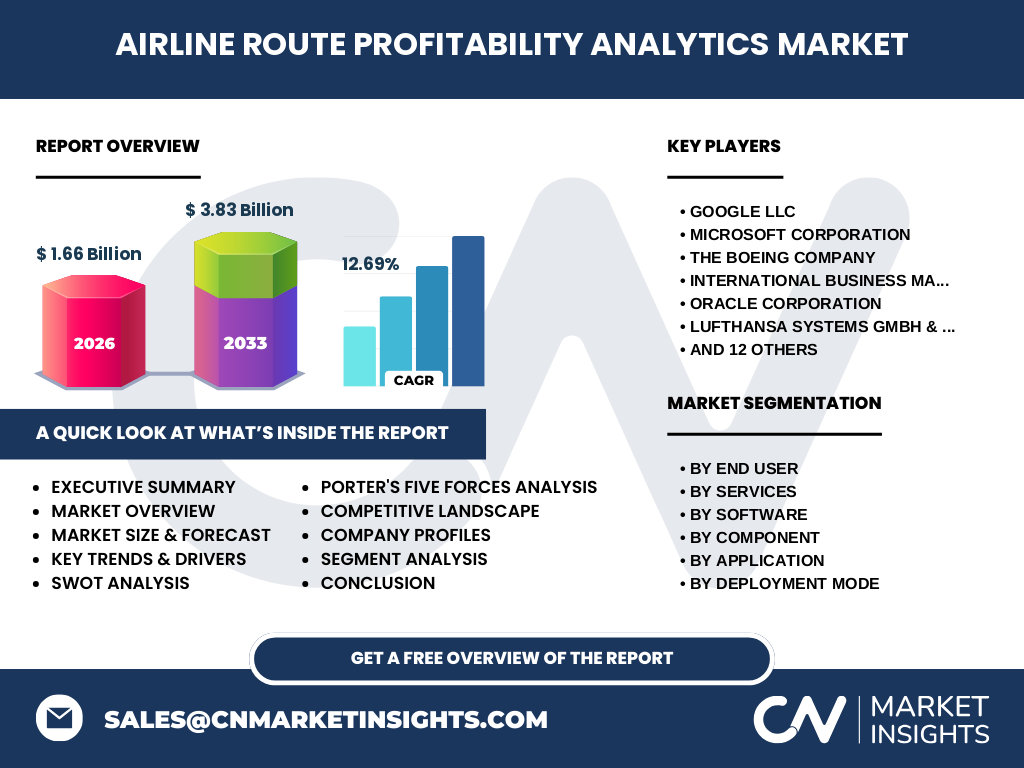
The Airline Route Profitability Analytics Market is valued at 1.66 Billion in 2026, serving as a critical financial nervous system for commercial carriers navigating fuel volatility and IATA regulatory pressures. This specialized market delivers granular insights into passenger yield management, ancillary revenue capture, and direct operating cost allocation across global hub-and-spoke networks.
What are the key market drivers, restraints, challenges, and opportunities shaping the industry?
Our analysis indicates that volatile jet fuel prices and strict carbon-offset mandates from bodies like the ICAO are primary drivers, compelling carriers to adopt advanced route analytics. However, integration friction with legacy Passenger Service Systems (PSS) acts as a major restraint. Opportunities abound in hyper-personalized ancillary pricing optimization.
Structural Growth Drivers in the Airline Route Profitability Analytics Market
Growth is heavily accelerated by the surging demand for real-time cloud data processing to counter unpredictable macroeconomic factors. Carriers are urgently abandoning static spreadsheets for dynamic modeling tools that factor in airport slot constraints, air navigation service charges, and fluctuating bilateral aviation agreements.
Pandemic Impact Analysis and Post-Crisis Recovery Trajectory
The COVID-19 pandemic permanently altered fleet deployment strategies, forcing airlines to prioritize point-to-point resilience over traditional hub dominance. This structural shift accelerated software adoption, as carriers needed sophisticated scenario planning modules to rapidly evaluate route viability under shifting international border restrictions and crew quarantine mandates.
Competitive Benchmarking and Market Concentration
The market features a mix of aviation-specific technology giants and enterprise software leaders. Firms like Amadeus IT Group S.A., Sabre Corporation, and PROS Holdings Inc. dominate through deep PSS integrations, while hyperscalers like Google LLC and Microsoft Corporation provide scalable cloud infrastructure.
Executive Summary of the Airline Route Profitability Analytics Market
The Airline Route Profitability Analytics Market is on an aggressive upward trajectory, projected to reach 3.83 Billion by 2033 at a CAGR of 12.69% from 2027. Digital transformation initiatives by major network carriers are cementing profitability software as an essential operational investment rather than an optional overhead.
Market Forecast and Valuation Trajectory from 2027 to 2033
Driven by a robust 12.69% CAGR, the sector expands from its 2026 baseline to hit 3.83 Billion by 2033. This expansion reflects accelerated airline digitization budgets aimed at squeezing operational efficiencies out of thin-margin international and domestic routes amid rising labor and maintenance expenses.
Segmentation Analysis Across Services, Software, and End Users
The market divides across several core pillars: By End User (Commercial Airlines, Cargo Airlines, Regional Airlines, Other End Users); By Services (Implementation, Consulting, Data Analytics, Maintenance, Training); By Software (Route Profitability, Revenue Management, Demand Forecasting, Pricing, Dashboard Reporting); By Component (Software, Services); By Application (Network Planning, Revenue Management, Cost Analysis, Performance Benchmarking); and By Deployment Mode (On Premises, Cloud).
Geographic Distribution and Regional Market Performance
Regional performance varies based on fleet modernization cycles and low-cost carrier proliferation. North America commands significant market share due to mature legacy carrier network hubs, whereas Asia-Pacific exhibits the fastest growth velocity, fueled by massive fleet expansions in emerging aviation hubs and rapid passenger traffic recovery.
In-Depth Regional Review of High-Growth Aviation Hubs
In Europe, stringent environmental taxes and slot controls at congested airports like Frankfurt and London Heathrow make route analytics indispensable for margin preservation. Meanwhile, carriers in the Middle East leverage these solutions to optimize sixth-freedom traffic flows through mega-connectors, balancing ultra-long-haul operational costs with competitive fare pricing.
Strategic Positioning of Leading Companies
Industry stalwarts deploy distinct value propositions: Lufthansa Systems GmbH & Co. KG and Hitit Bilgisayar Hizmetleri A.Ş. offer deeply contextualized operational insights, whereas IT service providers like Tata Consultancy Services Limited, Infosys Limited, and Wipro Limited deliver bespoke systems integration and cloud migration services.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers is moderate to high, as major airline alliances demand customized analytics integrations. Threat of new entrants remains low due to high switching costs and the necessity of deep domain expertise in aviation economics, slot management, and complex code-share revenue-sharing algorithms.
SWOT Analysis of the Industry Landscape
Key strengths include high predictive accuracy in volatile fuel markets. Weaknesses involve complex data silos between maintenance and commercial departments. Opportunities lie in artificial intelligence-driven predictive maintenance cost integration, while threats stem from potential cybersecurity vulnerabilities in centralized cloud reservation repositories.
Value Chain Analysis from Data Sources to End Users
The value chain originates with raw operational telemetry, reservation GDS feeds, and fuel price indices. Technology vendors process these inputs through sophisticated cloud architecture, delivering actionable intelligence to airline network planners, yield managers, and C-suite executives who execute strategic route adjustments.
Investment Insights and High-Potential Areas
Investors should target software providers specializing in real-time cloud-native demand forecasting and automated ancillary pricing integration. These niches offer superior recurring revenue models and address the acute airline need for rapid decision-making in volatile macroeconomic operating environments.
Conclusion and Strategic Takeaways
The path to margin recovery for modern carriers relies heavily on advanced data analytics. With market value scaling toward 3.83 Billion by 2033, stakeholders must prioritize cloud adoption and machine learning integration to maintain competitive advantages in a hyper-competitive global skies environment.
Research Methodology and Data Triangulation
Our findings are synthesized through a rigorous triangulation methodology, combining primary interviews with airline chief financial officers and network planning directors, secondary analysis of IATA and civil aviation authority filings, and econometric modeling of global macroeconomic indicators and jet fuel price curves.
Scope of the Report and Coverage Parameters
This report evaluates the global ecosystem across all specified software, service, deployment, and end-user segments from 2026 through 2033. Geographic scope encompasses North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, factoring in regional regulatory frameworks and bilateral air service agreements.
Recent Developments and Strategic Industry Moves
Recent market dynamism is highlighted by major technology partnerships between enterprise cloud giants like Oracle Corporation, SAP SE, and aviation specialists such as Ramco Systems Limited and Intelisys Aviation Systems, aimed at deploying modular, scalable route profitability engines for emerging regional carriers.