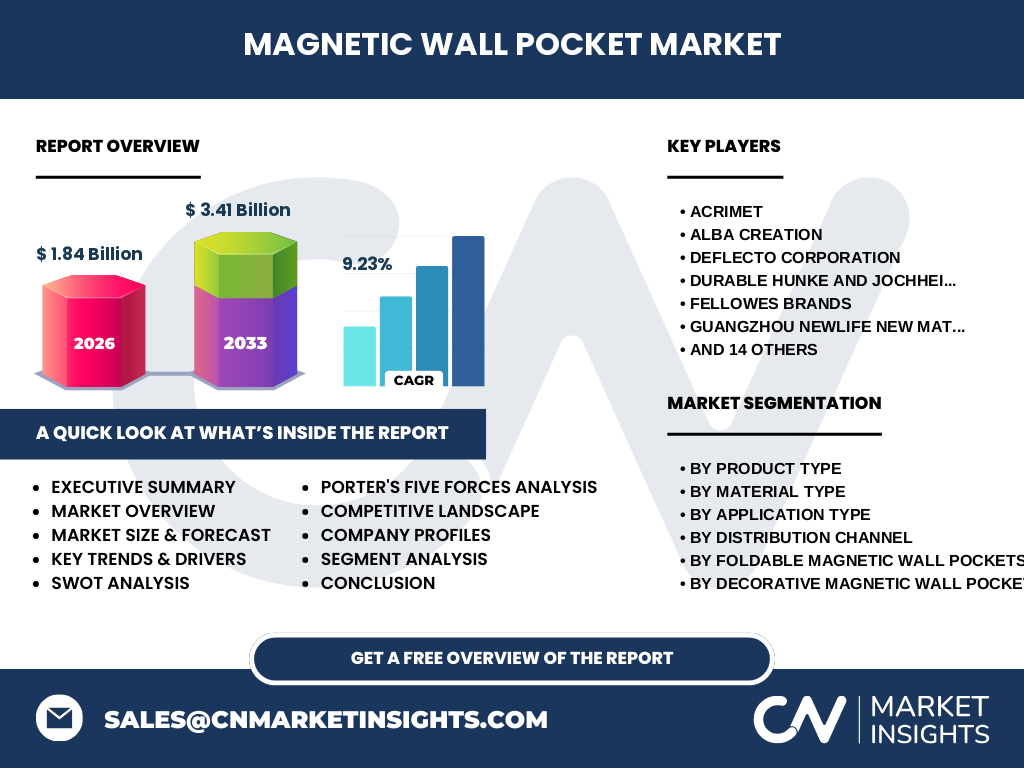
Market overview of the Magnetic Wall Pocket Market
Our analysis indicates that the Magnetic Wall Pocket Market reaches a valuation of $1.84 Billion in 2026. This sector encompasses organizational hardware utilizing neodymium and ferrite magnetic backings for vertical surface storage across commercial and residential spaces, driving vital supply chain flows.
What are the key market drivers, restraints, challenges, and opportunities?
Growth is accelerated by corporate real estate downsizing and workspace optimization, though volatile petrochemical resin costs present margin pressures. Opportunities abound for manufacturers developing high-load capacity variants meeting strict OSHA workplace safety guidelines.
Emerging trends and growth patterns in the industry
The market witnesses a distinct shift toward modular and sustainable office ecosystems. Consumers increasingly favor eco-friendly wood composites and recycled mesh designs, prompting innovators to revamp traditional manufacturing lines for enhanced environmental compliance.
COVID-19 impact analysis and recovery trajectory
The pandemic initially disrupted commercial distribution channels through major container ports, but catalyzed a robust secondary boom in home-office setups. Recovery has been propelled by hybrid work models requiring versatile, non-permanent document storage solutions.
Competitive benchmarking and strategic dynamics
Market concentration remains moderately fragmented, with industry titans like Deflecto Corporation and Fellowes Brands leveraging extensive distribution networks. Competitors constantly vie for shelf space through proprietary rust-resistant coatings and advanced magnetic shielding technologies.
Executive summary of the Magnetic Wall Pocket Market report
Synthesizing comprehensive metrics, our research projects the market to expand at a robust CAGR of 9.23%, surging from $1.84 Billion in 2026 to $3.41 Billion by 2033, driven by unrelenting corporate demand for ergonomic desk accessories.
Market forecast from 2027 to 2033
The forecast period highlights sustained upward momentum, translating to a near-doubling of sector valuation. Organizations prioritizing agile workspaces will consistently inject capital into heavy-duty and multi-pocket organizational hardware through 2033.
Segmentation analysis across product, material, and application
Categorized by Product Type (Single, Multi, Expandable, Foldable, Heavy Duty, Decorative), Material (Plastic, Metal, Fabric, Mesh, Acrylic, Wood), and Application (Home, Office, Education, Healthcare, Retail), the taxonomy reflects diverse end-user demands across B2B and B2C channels.
Regional market analysis and geographic distribution
Geographic performance shows North America leading consumption due to early adoption of agile office architecture, closely followed by Asia-Pacific manufacturing hubs where rapid urbanization fuels commercial infrastructure investments.
In-depth regional review of key markets
North America dominates through massive office supply retail penetration, while European markets enforce stringent REACH chemical regulations on plastic casings, compelling regional vendors to adopt certified non-toxic polymers.
Strategic company profiles in the sector
Industry leaders like Acrimet, Safco Products Company, and Winnable Enterprise focus on global logistics optimization. Meanwhile, design-forward brands like Poppin Inc. and Three by Three Seattle LLC capture premium retail segments.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to standardized ferrite material availability, whereas buyer power is high owing to extensive private-label alternatives available through mass-merchandise channels and dominant office supply aggregators.
SWOT analysis of the global landscape
Key strengths lie in product versatility and easy installation, countered by weaknesses in raw material price sensitivity. Market threats involve low-cost counterfeit imports challenging established compliance-verified brands.
Value chain analysis from raw materials to end-users
The value chain traces upstream polymer extraction and magnetic alloy production through precision injection molding, culminating in omnichannel distribution via office supply stores, e-commerce platforms, and direct B2B institutional contracts.
Investment insights and high-potential areas
High-potential capital allocation targets accordion-style expandable pockets and industrial-grade heavy-duty variants, offering superior margins and insulated demand from resilient healthcare and educational institutional buyers.
Conclusion and key takeaways for stakeholders
The sector presents compelling growth opportunities underpinned by a 9.23% CAGR. Success requires balancing cost-efficiency in plastic molding with design innovation in multi-pocket configurations.
Research methodology and data triangulation
Baseline estimates are triangulated by synthesizing customs trade registries, primary executive interviews with key stakeholders at Staples Inc. and Smead, and secondary macroeconomic indicators tracking commercial real estate completions.
Scope of the report and coverage parameters
This report covers global revenue performance, volume shipments, and strategic landscapes from 2026 to 2033, explicitly excluding custom architectural wall panel integrations lacking standalone magnetic pocket functionality.
Recent developments, partnerships, and product launches
Recent strategic moves feature Guangzhou Newlife New Material Co Ltd. launching eco-friendly magnetic sheeting, alongside DURABLE Hunke And Jochheim expanding automated logistics hubs across European distribution nodes.