Market overview of the Cocoa Beans Market
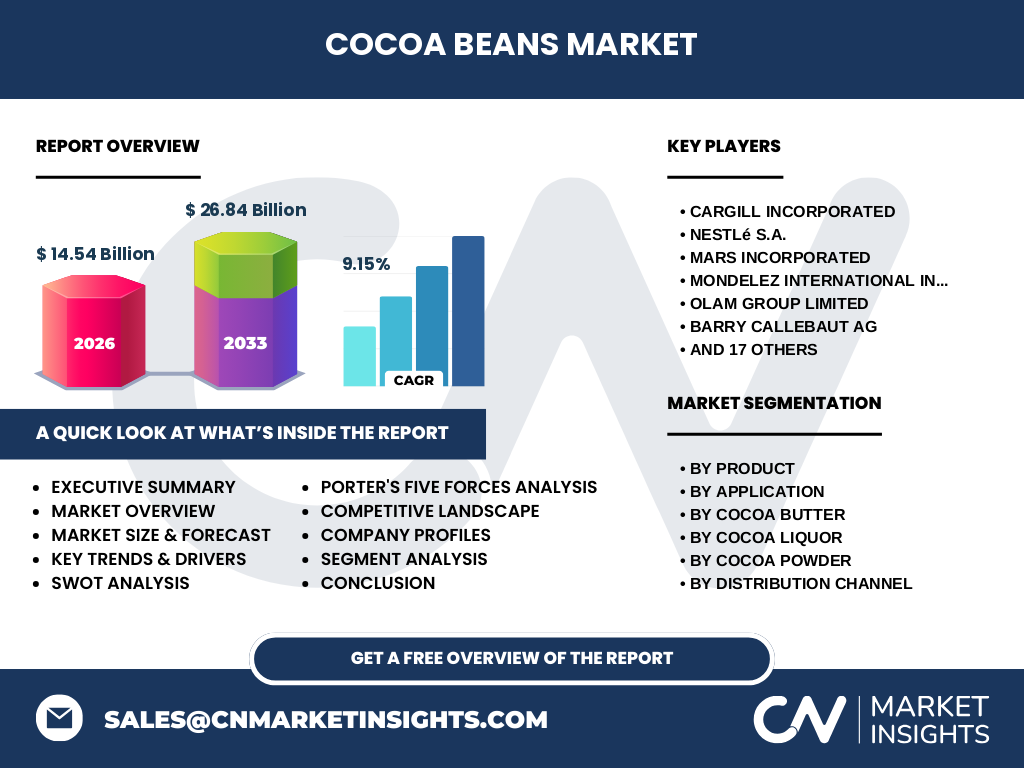
The Cocoa Beans Market encompasses the global supply chain, processing, and distribution of Theobroma cacao seeds, serving as the foundational raw material for chocolate and derivative confectionery goods. Our analysis indicates an industry valuation of 14.54 Billion in 2026, driven by rising global demand for chocolate confectionery, functional foods, and cosmetics.
Key market drivers, restraints, challenges, and opportunities shaping the Cocoa Beans Market
Structural growth in emerging economies propels the market forward, while climate change impacts and crop diseases like swollen shoot virus act as major supply constraints. Market participants face persistent price volatility on futures exchanges. However, rising demand for traceable, sustainable sourcing presents lucrative opportunities for premium players.
Emerging trends and growth patterns in the Cocoa Beans Market
The shift toward clean-label and ethically sourced ingredients is reshaping product formulation across the Cocoa Beans Market industry trends. Consumers increasingly demand organic and sustainably harvested beans, compelling processors to adopt blockchain-enabled supply chain transparency to verify origin and fair-trade compliance.
COVID-19 impact analysis on the Cocoa Beans Market
The pandemic caused severe logistical bottlenecks, port congestion at major African export hubs, and temporary retail closures that depressed short-term demand. Based on our research, the market demonstrated remarkable resilience, recovering swiftly as out-of-home consumption rebounded and e-commerce distribution channels expanded aggressively.
Competitive landscape and strategic dynamics in the Cocoa Beans Market
Industry concentration remains high among vertically integrated giants who control sourcing, grinding, and distribution. Companies like Cargill Incorporated, Barry Callebaut AG, and Olam Group Limited dominate global processing. Strategic dynamics focus on securing long-term supply agreements and investing in sustainable cocoa farming initiatives.
Executive summary of the Cocoa Beans Market
Our comprehensive evaluation projects the Cocoa Beans Market market size to expand significantly, reaching 26.84 Billion by 2033. Propelled by a robust CAGR of 9.15% from 2027 to 2033, the sector is transitioning toward value-added processing, sustainable agriculture, and premium product formulations across global supply chains.
Market forecast from 2027 to 2033
Driven by rising disposable incomes in developing regions and expanding applications in pharmaceuticals and cosmetics, the market is set for accelerated expansion. We project the valuation to climb from 14.54 Billion in 2026 to 26.84 Billion by 2033, achieving a stellar CAGR of 9.15%.
Segmentation analysis of the Cocoa Beans Market
The market is segmented by product into Cocoa Butter, Cocoa Powder, and Cocoa Liquor. Application sectors include Confectionery, Functional Foods And Beverages, Pharmaceuticals, and Cosmetics. Distribution channels span Online, Hypermarkets And Supermarkets, Convenience Stores, and Specialty Stores, catering to diverse industrial and retail consumer needs globally.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with West African nations dominating raw bean production, while Europe and North America lead in processing and consumption. Emerging economies in Asia-Pacific represent the fastest-growing regional pockets, fueled by expanding urban middle classes and Westernized dietary habits.
In-depth regional review of the Cocoa Beans Market
West Africa remains the epicenter of raw production, though regulatory shifts regarding living income differentials impact local farmer revenues. Meanwhile, European processing hubs navigate strict European Union Deforestation Regulation compliance, altering import strategies for key players like Barry Callebaut AG and Nestlé S.A.
Company profiles and strategic positioning
Key industry participants occupy distinct strategic niches. Mars Incorporated and Mondelez International Inc. focus on brand-driven confectionery dominance. Processing powerhouses such as Guan Chong Berhad and JB Foods Limited optimize industrial grinding efficiency, while specialized entities like Casa Luker S.A.S. champion single-origin fine flavor beans.
Porter's Five Forces analysis of the industry
Bargaining power of suppliers is moderate to high due to localized agricultural dependencies, while buyer power remains constrained by the necessity of proprietary formulations. Threat of substitutes is low in confectionery but moderate in functional foods. Competitive rivalry is intense among established global grinders and brand conglomerates.
SWOT analysis of the Cocoa Beans Market
Key strengths include deeply ingrained consumer demand for chocolate and robust global supply chains. Weaknesses involve vulnerability to weather anomalies and aging farmer demographics. Opportunities lie in functional health products and organic segments, whereas threats stem from stringent regulatory compliance and persistent price volatility.
Value chain analysis from raw materials to end-users
The value chain originates with smallholder farmers cultivating raw beans in tropical regions, moving through local buying agents, international traders like Touton S.A. and ECOM Agroindustrial Corp. Limited, industrial grinders, and finally to industrial manufacturers creating end-user confectionery and cosmetic products.
Investment insights and high-potential areas
Strategic investment should target agtech solutions for sustainable farming, blockchain traceability platforms, and value-added organic segments. Companies that successfully align with strict environmental regulations and consumer health trends will capture outsized market share and superior long-term profit margins.
Conclusion and key takeaways
The Cocoa Beans Market analysis demonstrates a high-growth sector projected to reach 26.84 Billion by 2033. Success in this evolving landscape requires rigorous supply chain transparency, strategic sustainability commitments, and agile adaptation to shifting consumer preferences favoring ethical and functional cocoa derivatives.
Research methodology for market estimation
Our baseline estimates are rigorously triangulated by combining official trade registry data from international cocoa organizations, primary stakeholder interviews with industry executives, and secondary macroeconomic indicators to ensure high-fidelity market sizing and accurate growth forecasting across all segments.
Scope of the report and coverage parameters
This research report covers global market dynamics, comprehensive segment breakdowns, regional performance evaluations, and competitive intelligence from 2026 through 2033. Limitations include unforeseen macroeconomic shocks, sudden regulatory policy shifts, and unpredicted extreme weather events affecting raw agricultural yields.
Recent developments and strategic moves in the sector
Recent strategic moves feature major processors expanding sustainability partnerships and launching certified organic product lines. Companies like The Hershey Company and Ferrero International S.A. have ramped up investments in direct farmer-support programs to secure compliant, deforestation-free supply chains ahead of tightening international trade regulations.