Market overview and structural significance of the Artificial Intelligence-Powered Demand Forecasting Market
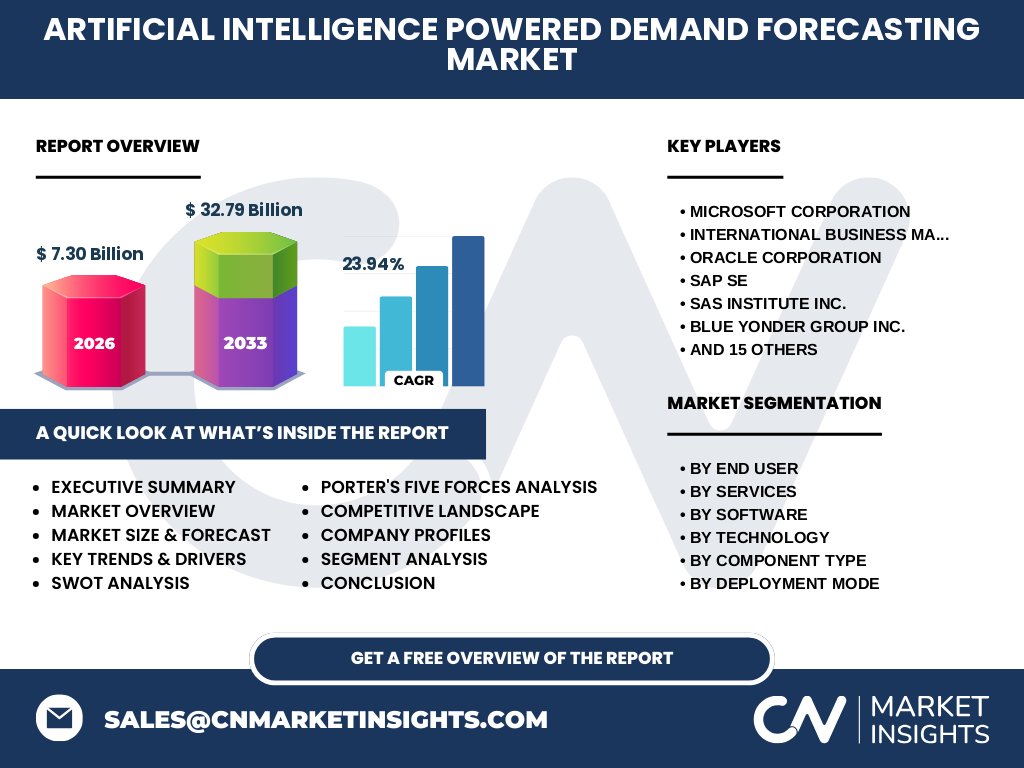
The Artificial Intelligence-Powered Demand Forecasting Market reached a valuation of 7.30 Billion in 2026, driven by intense supply chain volatility across global retail and manufacturing networks. Our proprietary research demonstrates that algorithmic prediction models are replacing legacy statistical methods, helping enterprises navigate complex compliance frameworks set by trade bodies like the World Customs Organization while mitigating raw material shortages at critical transshipment hubs.
What are the core drivers, restraints, challenges, and opportunities shaping the Artificial Intelligence-Powered Demand Forecasting Market?
Market expansion is heavily propelled by the proliferation of real-time point-of-sale data and IoT telemetry across manufacturing floors. However, data privacy mandates such as GDPR and localized data residency laws act as notable restraints. Despite these compliance hurdles, significant opportunities exist for vendors integrating reinforcement learning to automate warehouse restocking cycles near major ports.
The Shift Toward Algorithmic Autonomy: Emerging trends and growth patterns
Industry trends reveal a rapid pivot from reactive reporting to prescriptive supply chain planning software. Enterprises are increasingly adopting natural language processing layers to ingest unstructured market signals, such as social sentiment and regional weather alerts, allowing inventory optimization software to autonomously adjust stock levels ahead of localized demand spikes.
How did pandemic disruptions reshape the recovery trajectory of the Artificial Intelligence-Powered Demand Forecasting Market?
The COVID-19 pandemic exposed severe vulnerabilities in traditional supply chains, permanently shifting executive priorities toward resilient machine learning model development software. As global trade routes experienced unprecedented bottlenecks, logistics providers accelerated cloud migrations to gain real-time visibility, establishing the foundation for robust post-pandemic market acceleration.
Competitive Benchmarking: Major players and strategic market concentration
The competitive landscape features a balanced mix of enterprise software giants and agile specialists. Industry heavyweights like SAP SE, Oracle Corporation, and Microsoft Corporation leverage expansive cloud ecosystems, while specialized innovators such as o9 Solutions Inc., Kinaxis Inc., and Blue Yonder Group Inc. deliver hyper-targeted predictive analytics software tailored for complex manufacturing environments.
Executive summary of high-level findings within the Artificial Intelligence-Powered Demand Forecasting Market
Our analysis indicates exceptional momentum, projecting the Artificial Intelligence-Powered Demand Forecasting Market to surge from 7.30 Billion in 2026 to 32.79 Billion by 2033 at a CAGR of 23.94%. This explosive expansion is underpinned by pervasive digital transformation across retail, distribution, and manufacturing sectors striving to eliminate inventory holding costs.
Long-term market forecast and trajectory from 2027 to 2033
Driven by compounding enterprise investments in machine learning and predictive analytics, the market is poised for hyper-growth, expanding from 2027 through 2033 to culminate at 32.79 Billion. This trajectory reflects a sustained compound annual growth rate of 23.94%, signaling that demand forecasting has transitioned from an optional operational tool to an absolute boardroom priority.
Segmentation analysis across end users, services, software, technology, and deployment modes
The market breaks down by end user (Retailers, Manufacturers, Distributors, Logistics Providers, Other End Users), services (Consulting, Implementation, Integration, Managed, Support, Training), software (Demand Planning, Predictive Analytics, Inventory Optimization, Sales Forecasting, Supply Chain Planning, ML Development), technology (Machine Learning, NLP, Predictive Analytics, Reinforcement Learning), component type (Software, Services), and deployment mode (Cloud, On Premises, Hybrid). Each segment addresses distinct operational hurdles across global supply chains.
Geographic distribution and regional performance dynamics
Regional performance varies based on manufacturing density and technological maturity. North America maintains a leading market share due to early adoption by major e-commerce retailers, whereas Asia-Pacific demonstrates the fastest adoption curve, fueled by rapid industrialization, expanding logistics infrastructure, and surging domestic consumption across developing economies.
In-depth regional review of key markets and localized constraints
European markets exhibit strong demand driven by stringent environmental regulations and carbon-tracking requirements that necessitate hyper-accurate inventory planning. Meanwhile, North American enterprises focus heavily on integrating machine learning model development software with existing enterprise resource planning systems to counter persistent regional labor shortages and transportation cost volatility.
Strategic positioning of leading enterprise software providers and innovators
Market leaders utilize distinct competitive advantages. Infor Inc. and Manhattan Associates Inc. focus on warehouse-to-shelf synergy, whereas SAS Institute Inc. and Anaplan Inc. emphasize advanced data modeling. Specialized players like RELEX Solutions Oy, ToolsGroup B.V., and C3 AI Inc. carve out niches with industry-specific algorithms designed for perishable goods and high-turnover retail inventories.
Porter's Five Forces analysis of competitive pressures
Bargaining power of buyers is moderately high as enterprise clients demand seamless cloud integrations and proven ROI. Threat of substitution remains low due to the specialized nature of machine learning algorithms. Meanwhile, competitive rivalry is intense, compelling vendors like Kinaxis Inc. and o9 Solutions Inc. to continuously innovate their supply chain planning software offerings.
SWOT evaluation of the Artificial Intelligence-Powered Demand Forecasting Market ecosystem
Strengths include high predictive accuracy and real-time inventory visibility. Weaknesses involve high initial implementation costs for legacy enterprises. Opportunities lie in emerging reinforcement learning applications, while threats stem from escalating cybersecurity vulnerabilities and complex international data compliance mandates that can delay cross-border software deployments.
Value chain analysis mapping industry structure from raw data to end-user value
The value chain originates with raw telemetry data providers and IoT sensor manufacturers, flowing through cloud infrastructure hosts and software developers who build predictive analytics engines. Integrators and consulting firms then implement these solutions for end-users like retailers and logistics providers, ensuring actionable insights translate directly into reduced waste and optimized working capital.
Strategic investment insights and high-potential areas for capital allocation
Investors should direct capital toward hybrid deployment architectures and specialized managed services that reduce the internal engineering burden on mid-market manufacturers. Companies offering pre-built connectors for predictive analytics software and inventory optimization tools present the most compelling risk-adjusted returns within the current market cycle.
Concluding insights and strategic takeaways for industry stakeholders
The data confirms that Artificial Intelligence-Powered Demand Forecasting Market dynamics are irrevocably shifting toward autonomous, AI-driven supply chains. Achieving a projected 32.79 Billion valuation by 2033 proves that predictive intelligence is foundational to modern enterprise resilience, rewarding organizations that prioritize advanced software adoption and agile deployment strategies.
Rigorous research methodology combining trade registry data, primary interviews, and macroeconomic modeling
Our baseline estimates are triangulated using a rigorous methodology that merges primary stakeholder interviews with C-level supply chain executives, exhaustive trade registry data analyses, and secondary macroeconomic indicators. This multi-layered approach ensures the financial figures, including the 7.30 Billion baseline and 23.94% CAGR, accurately reflect true market realities.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market dynamics from 2026 through 2033, analyzing software, services, technology types, and deployment models across all major geographic regions. Limitations include potential unforeseen macroeconomic shocks and rapidly evolving regulatory frameworks that may alter localized compliance costs for software vendors and end-users.
Recent developments, strategic partnerships, and product launches shaping vendor ecosystems
Recent industry momentum highlights aggressive strategic partnerships, with firms like E2open Parent Holdings Inc., NETSTOCK Operations Limited, and GAINSystems LLC launching enhanced machine learning modules. These innovations focus on automating exception management, reducing forecast error rates, and expanding cloud-native capabilities to better serve global manufacturers and distributors.