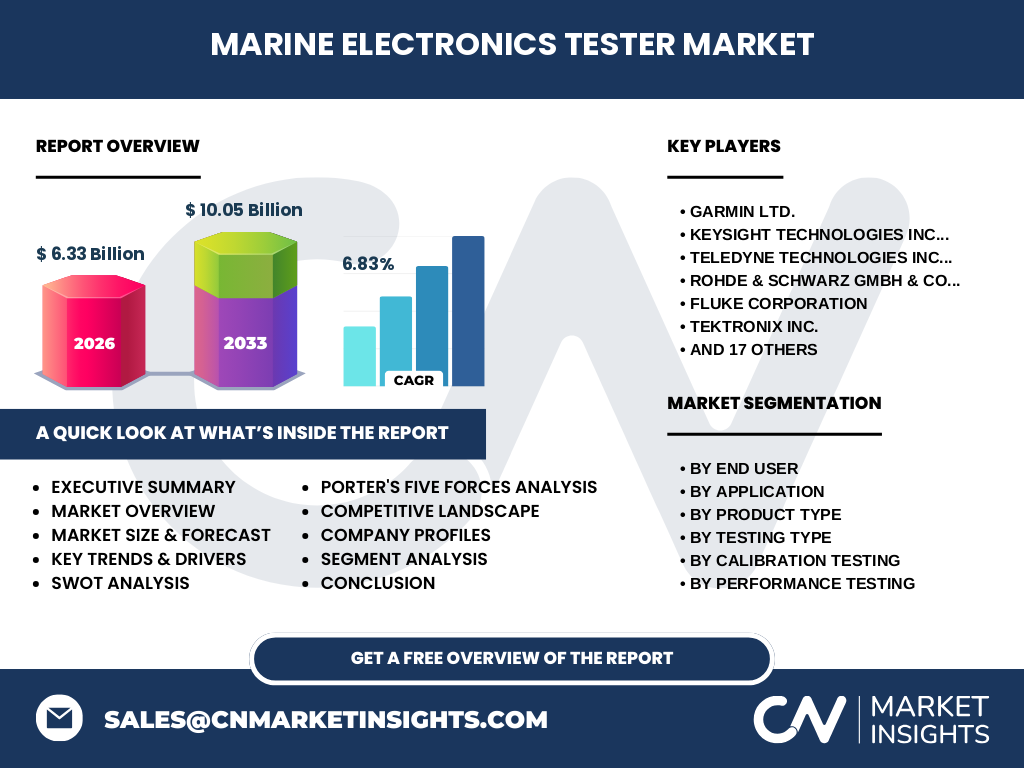
Market overview of the Marine Electronics Tester Market
Our analysis indicates that the Marine Electronics Tester Market encompasses specialized diagnostic tools valued at 6.33 Billion in 2026. These instruments ensure navigational safety, regulatory compliance, and system reliability across commercial and defense fleets globally.
Key market drivers, restraints, challenges, and opportunities
Growth is propelled by rising maritime trade and stringent International Maritime Organization mandates. However, supply chain bottlenecks for raw materials like high-grade copper and semiconductor chips present persistent restraints for equipment manufacturers.
The Shift Toward Advanced Diagnostic Automation
Emerging trends highlight a distinct pivot toward automated spectrum analyzers and wireless multimeters. This evolution allows marine engineers at major ports like Rotterdam and Singapore to conduct rapid, remote diagnostic assessments without dry-docking vessels.
Pandemic Recovery and Resilience
The COVID-19 pandemic caused severe supply chain disruptions and deferred shipyard maintenance schedules. Post-pandemic recovery has since accelerated, driven by extensive backlogs in commercial shipping fleet overhauls and naval modernization initiatives.
Competitive Benchmarking and Market Concentration
The competitive landscape features industry leaders like Keysight Technologies Inc., Rohde & Schwarz GmbH & Co. KG, and Fluke Corporation. These players dominate through advanced calibration technologies and robust global distribution networks.
Executive Summary of the Marine Electronics Tester Market industry trends
Our research confirms robust expansion, projecting the market to reach 10.05 Billion by 2033 from 6.33 Billion in 2026 at a 6.83% CAGR. Demand is heavily concentrated in commercial shipping and naval defense segments.
Long-Term Market Forecast through 2033
Based on our econometric models, the market is poised to scale from 6.33 Billion in 2026 to 10.05 Billion by 2033. This trajectory reflects a solid 6.83% CAGR, sustained by mandatory avionics and navigation system upgrades.
Segmentation Analysis by Product and End User
The sector segments across multimeters, oscilloscopes, spectrum analyzers, and network analyzers. End users span shipbuilders, maintenance repair companies, and naval defense agencies requiring rigorous compliance verification at major coastal shipyards.
Geographic Distribution and Performance
Regional performance mirrors global shipping density. Asia-Pacific leads due to heavy shipbuilding concentration in South Korea, China, and Japan, while Europe and North America emphasize rigorous electromagnetic compatibility testing for defense vessels.
In-Depth Regional Review
Asia-Pacific dominates the market share, supported by maritime hubs in Shanghai and Busan. Meanwhile, North American growth is anchored by Teledyne Technologies Incorporated and Tektronix Inc. supplying the U.S. Navy and regional commercial fleets.
Company Profiles and Strategic Positioning
Key innovators such as Anritsu Corporation, VIAVI Solutions Inc., and Furuno Electric Co. Ltd. focus on high-frequency RF testing solutions. Their strategic positioning emphasizes proprietary software integration and localized technical support near critical shipping lanes.
Porter's Five Forces Analysis
Supplier power remains moderate due to specialized semiconductor reliance, while buyer power is high among large shipyards. Threat of substitutes is low given strict classification society standards enforced by bodies like DNV and Lloyd's Register.
SWOT Analysis of the Marine Electronics Tester Market
Strengths lie in advanced diagnostic precision, whereas weaknesses involve high initial calibration costs. Opportunities abound in autonomous vessel electronics testing, while threats include counterfeit components infiltrating secondary distribution channels.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material sourcing—silicon, rare earths, and aluminum alloys—moving through component fabrication by firms like Hioki E.E. Corporation and Rigol Technologies, culminating in deployment across commercial shipyards.
Strategic Investment Insights
High-potential areas include portable environmental testing units and automated optical inspection tools. Investors should target firms integrating IoT capabilities to capture recurring service revenues from remote maritime maintenance contracts.
Conclusion and Key Takeaways for Stakeholders
The Marine Electronics Tester Market offers compelling growth, backed by a 6.83% CAGR toward 10.05 Billion by 2033. Stakeholders must prioritize technological integration and compliance with evolving maritime safety standards.
Research Methodology and Data Triangulation
Our estimates are triangulated by combining primary interviews with chief engineers and procurement officers, secondary trade registry data, and macroeconomic indicators from maritime transport authorities across key global shipping corridors.
Scope of the Report and Coverage Parameters
This report covers global revenue estimations from 2026 to 2033, segmented by product type, testing type, application, and distribution channel. Limitations exclude unverified grey-market equipment and unregistered localized workshops.
Recent Developments and Strategic Industry Moves
Recent milestones include strategic acquisitions and new product rollouts by Megger Group Limited and Siglent Technologies Co. Ltd., focusing on ruggedized field-testing units designed to withstand harsh marine environments and salt spray corrosion.