What is the scope and industry significance of the Wood Construction Market?
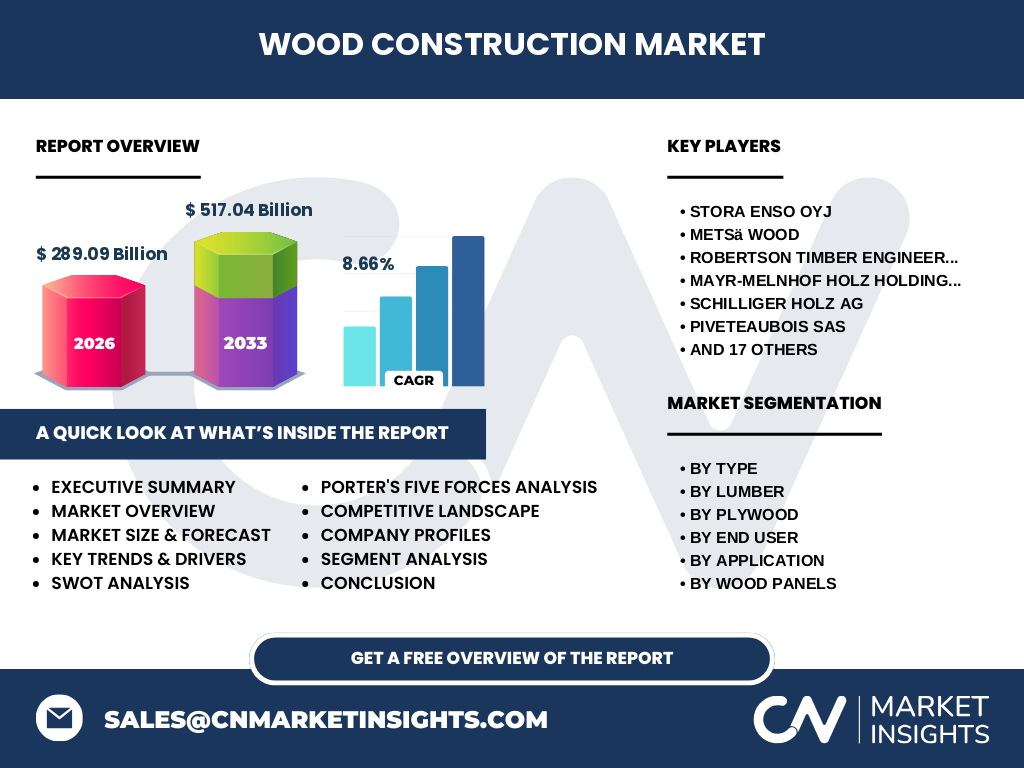
Our analysis indicates that the Wood Construction Market encompasses raw material processing, mass timber engineering, and structural framing applications. Valued at $289.09 Billion in 2026, this sector represents a critical pillar of sustainable infrastructure. The industry bridges traditional forestry with advanced architectural standards regulated by bodies like the International Code Council.
Structural Growth Drivers and Market Restraints
The market is propelled by strict carbon reduction mandates and innovations in mass timber. Key restraints involve supply chain bottlenecks for structural lumber and volatile tariffs on softwood imports. Opportunities abound in hybrid concrete-timber skyscrapers, pushing the sector toward a robust valuation.
Emerging Trends and Growth Patterns in Wood Construction
A profound shift toward prefabrication and modular construction is redefining site logistics. Architects increasingly specify Cross Laminated Timber and Glued Laminated Timber for high-rise commercial builds. This trend favors agile innovators capable of delivering precision-cut wall panels directly to dense urban centers.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
Pandemic-era supply chain disruptions caused severe volatility in softwood and oriented strand board pricing. However, post-pandemic recovery sparked accelerated investments in off-site manufacturing facilities. Government incentives for green building materials have cemented a resilient long-term recovery path for the entire industry.
Competitive Benchmarking and Industry Concentration
The competitive landscape features a mix of vertically integrated forestry giants and specialized engineering firms. Companies like Stora Enso Oyj and Metsä Wood dominate European supply, while regional specialists handle custom structural timber frames, driving high market consolidation across engineered wood segments.
Executive Summary of the Wood Construction Market
Driven by decarbonization goals, the Wood Construction Market is poised for unprecedented expansion. Reaching $517.04 Billion by 2033 at an impressive CAGR of 8.66%, the sector offers high-yield opportunities for investors prioritizing sustainable, low-carbon building methodologies.
Market Forecast Projections (2027 to 2033)
Our research forecasts accelerated expansion from 2027 to 2033, surging from the 2026 baseline of $289.09 Billion to $517.04 Billion. This trajectory is underpinned by an 8.66% CAGR, fueled by multi-story mass timber approvals and rising demand for renewable building stock.
Segmentation Analysis of Building Materials and End Users
The ecosystem breaks down across critical categories: By Type (Lumber, Engineered Wood, Wood Panels, Plywood, OSB), By End User (Builders, Contractors, Architects, Engineers, Homeowners), and By Application (Residential, Commercial, Industrial, Infrastructure). Each segment addresses specific structural demands from flooring to heavy building frames.
Geographic Distribution and Regional Market Performance
Regional performance varies based on local forestry supply and building codes. Europe leads in engineered timber adoption due to progressive municipal mandates, while North America experiences surging demand for structural lumber and oriented strand board in residential framing and multi-family complexes.
In-Depth Regional Review and Localized Constraints
Logistical hurdles such as rail car availability and regional forestry pest management directly impact regional output. Markets with robust port infrastructure facilitate smoother export of specialized plywood and glulam products, whereas landlocked zones face higher distribution costs managed primarily through direct sales channels.
Strategic Company Profiles and Market Positioning
Key industry participants occupy distinct niches: Mayr-Melnhof Holz Holding AG and HASSLACHER Holding GmbH lead in large-scale glulam production. Meanwhile, innovators like Intelligent City Inc. and StructureCraft Builders Inc. pioneer algorithmic design and proprietary mass timber structural systems for urban markets.
Porter's Five Forces Analysis
Supplier power remains moderate due to consolidated timber ownership. Threat of substitution from steel and concrete is diminishing thanks to favorable fire-safety code updates. Competitive rivalry is intense among engineered wood producers striving for proprietary product differentiation in roof trusses and wall panels.
SWOT Analysis of the Wood Construction Ecosystem
Strengths include superior carbon sequestration and high strength-to-weight ratios. Weaknesses involve moisture vulnerability requiring strict treatment. Opportunities lie in urban mid-rise mandates, while threats stem from inflationary raw material costs and stringent regional forestry harvesting regulations.
Value Chain Analysis from Raw Forestry to End-Users
The value flow originates with sustainable forestry harvesting, passing through sawmills and secondary processing plants producing medium density fiberboard, parallel strand lumber, and laminated veneer lumber. Distributors and wholesalers then supply contractors and builders for final assembly in residential and commercial projects.
Investment Insights and High-Potential Growth Areas
Investors should target manufacturers specializing in cross-laminated timber and moisture-resistant oriented strand board. High-potential areas include automated off-site prefabrication plants and digital supply chain platforms serving commercial contractors seeking rapid project turnaround times.
Conclusion and Strategic Takeaways
The Wood Construction Market represents a transformative shift in global architecture. With a projected valuation of $517.04 Billion by 2033, stakeholders must align capital expenditure with sustainable forestry compliance and advanced modular prefabrication technologies to capture maximum market share.
Research Methodology and Data Triangulation
Baseline estimates are triangulated using a rigorous multi-tier methodology. We combine trade registry data from forestry boards, primary stakeholder interviews with executives at firms like Bensonwood Homes Inc. and Huber Engineered Woods LLC, and secondary macroeconomic construction indicators.
Scope of the Report and Coverage Parameters
This report covers global production, distribution channels, and application verticals through 2033. Limitations include localized building code revisions and fluctuating timber stumpage prices, which are continuously monitored via our proprietary predictive modeling framework.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum is defined by strategic joint ventures in automated panelization and plant expansions by market leaders. Firms are heavily investing in digital fabrication software to seamlessly integrate architectural design parameters with heavy timber manufacturing lines.