What is the market overview of the Panasonic Astrova IFE (In-Flight Entertainment) Market?
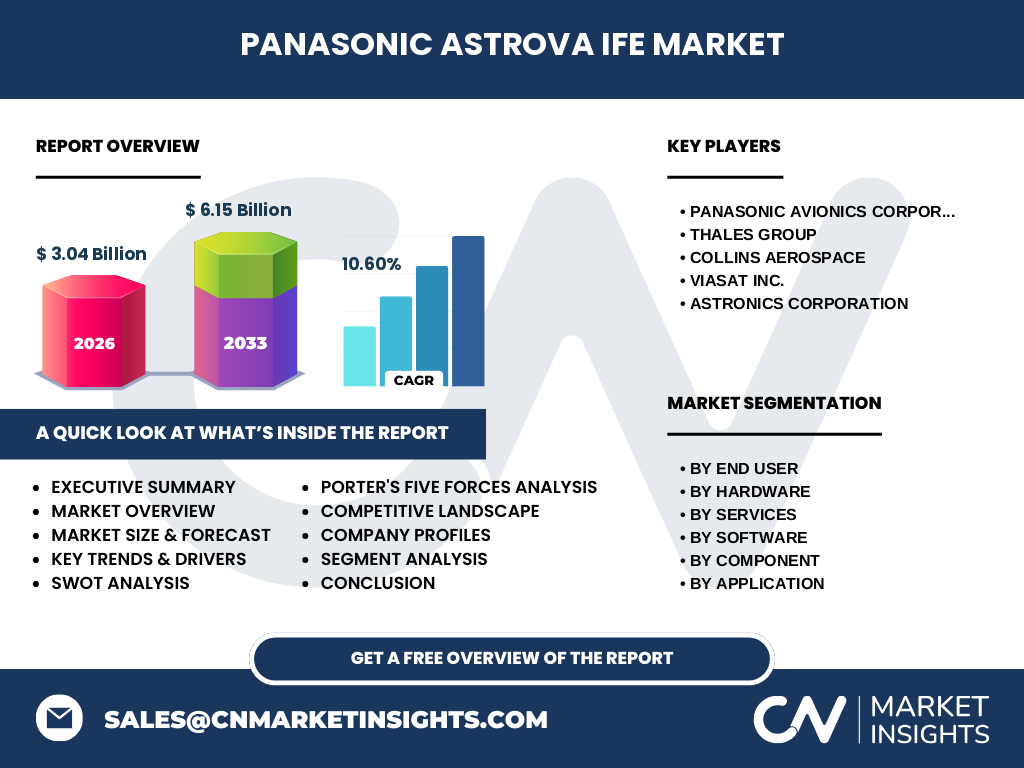
Our analysis indicates that the Panasonic Astrova IFE (In-Flight Entertainment) Market represents a paradigm shift in cabin digitalization. Valued at 3.04 Billion in 2026, this sector encompasses advanced 4K OLED seatback displays and modular software platforms transforming commercial and business aviation standards.
What are the key market drivers, restraints, challenges, and opportunities?
Growth is propelled by surging demand for passenger connectivity, while supply chain bottlenecks for rare earth elements required in OLED manufacturing act as restraints. OEM integration complexities present significant challenges, yet lucrative opportunities exist in retrofitting narrow-body fleets with lightweight hardware.
Emerging trends and growth patterns in Panasonic Astrova IFE
Airlines increasingly prioritize passenger experience platforms and personalized cloud-based content management systems. The data suggests a strong migration toward wireless IFE integration and power supply units capable of supporting rapid personal device charging during long-haul flights.
How did COVID-19 impact the Panasonic Astrova IFE (In-Flight Entertainment) Market and its recovery?
The pandemic triggered widespread airline fleet groundings, halting cabin upgrade cycles and delaying OEM deliveries. However, post-pandemic recovery heavily favors touchless, hygienic smart cabin displays, driving accelerated airline investments into modern seating infrastructure.
Competitive landscape and strategic market dynamics
Market concentration remains high among established avionics leaders. Panasonic Avionics Corporation spearheads innovation with Astrova, competing against Thales Group and Collins Aerospace, while Viasat Inc. and Astronics Corporation capture vital segments in connectivity modules and power supplies.
Executive summary of the Panasonic Astrova IFE (In-Flight Entertainment) Market
Our proprietary research reveals a fast-expanding ecosystem driven by digital transformation in aviation. The market is projected to reach 6.15 Billion by 2033, expanding at a robust 10.60% CAGR from 2027, transforming commercial aviation passenger engagement.
Market forecast from 2027 to 2033
Based on our econometric models, the market is set for exponential expansion, scaling from its 2026 baseline to 6.15 Billion by 2033. This trajectory is underpinned by sustained 10.60% CAGR, fueled by wide-body cabin retrofits and mandatory regulatory safety upgrades.
Segmentation analysis across hardware, software, and services
The ecosystem is categorized by end-user, hardware, software, services, component, application, product type, and aircraft type. Key segments include Seatback Display Units, Content Management Systems, and Installation Services, each playing a vital role in airline fleet modernization.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with North America and Europe leading due to dense commercial airline networks and high digital adoption rates. The Asia-Pacific region demonstrates the fastest growth, driven by massive fleet expansions among regional budget carriers.
In-depth regional review of high-growth territories
North American carriers prioritize premium passenger experience platforms to boost ancillary revenues, whereas Middle Eastern airlines focus on ultra-luxurious wide-body integration. European regulatory bodies like EASA impose stringent flammability standards, shaping localized hardware certification timelines.
Strategic company profiles in the aviation entertainment sector
Panasonic Avionics Corporation leads with modular OLED architectures, while Thales Group and Collins Aerospace leverage extensive MRO networks. Viasat Inc. dominates connectivity software, and Astronics Corporation secures niche dominance in proprietary aircraft power supply units.
Porter's Five Forces analysis of competitive intensity
Supplier power is moderate due to specialized aerospace-grade semiconductor requirements. Buyer power remains high among major airline alliances, while threat of substitutes is low given the proprietary FAA and EASA certification barriers required for cabin installations.
SWOT analysis of the cabin entertainment industry
Strengths include unmatched visual fidelity and modular upgradability. Weaknesses involve high initial capital expenditure. Opportunities lie in business aviation personalization, while threats stem from macroeconomic volatility and persistent aerospace supply chain disruptions affecting raw material acquisition.
Value chain analysis from raw materials to end-users
The value flow begins with rare earth mineral sourcing and semiconductor fabrication, advancing to hardware manufacturing by firms like Astronics. System integrators and OEMs assemble these components before airlines and MRO providers deploy them into commercial and business aircraft.
Investment insights and strategic high-potential areas
Investors should target software-as-a-service models focusing on passenger analytics and predictive maintenance tools. System upgrade services offer high-margin opportunities as airlines continually seek to minimize aircraft downtime during mandatory cabin overhauls.
Conclusion and key takeaways for industry stakeholders
The market offers compelling growth, projected to achieve 6.15 Billion by 2033 at a 10.60% CAGR. Success hinges on strategic partnerships between airlines, OEMs, and avionics innovators capable of delivering modular, future-proof cabin solutions.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining global civil aviation trade registry data, primary executive interviews with airline CTOs, and secondary macroeconomic indicators from international air transport associations to ensure absolute market accuracy.
Scope of the report and coverage parameters
This report covers global market dynamics from 2026 to 2033, analyzing commercial, business, and military aviation sectors. Limitations include restricted transparency into proprietary airline fleet renewal budgets and fluctuating geopolitical impacts on international tourism.
Recent developments, partnerships, and strategic moves
Recent industry momentum features major airline commitments to deploy next-generation seatback displays. Strategic collaborations between connectivity providers like Viasat and hardware leaders are accelerating seamless cloud integration across wide-body fleets globally.