Market overview of Traffic Alert And Collision Avoidance System II (TCAS II) Version 8.1 Upgrades Market
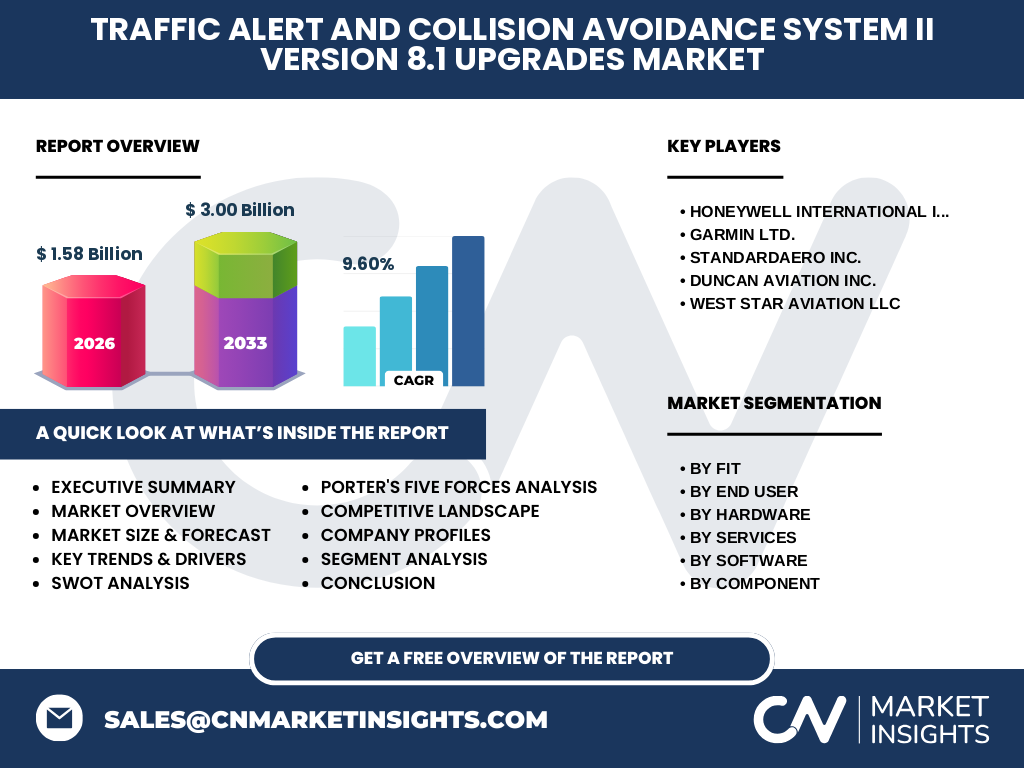
Our analysis indicates that the Traffic Alert And Collision Avoidance System II (TCAS II) Version 8.1 Upgrades Market stands at 1.58 Billion in 2026. This sector encompasses critical avionics modifications mandated by safety agencies to enhance airspace safety, minimize false Resolution Advisories, and improve tracking precision across commercial and business aviation fleets worldwide.
What are the key drivers, restraints, challenges, and opportunities shaping Traffic Alert And Collision Avoidance System II (TCAS II) Version 8.1 Upgrades Market?
Regulatory mandates by authorities like EASA and ICAO act as primary growth catalysts. However, supply chain bottlenecks for rare earth raw materials used in Antenna Systems and high retrofit downtime present notable restraints. Opportunities abound for providers delivering rapid-turnaround software patches.
Emerging trends and growth patterns in Traffic Alert And Collision Avoidance System II (TCAS II) Version 8.1 Upgrades Market
Industry trends highlight an accelerated shift toward integrated digital flight decks. Operators increasingly demand seamless compatibility between upgraded Resolution Advisory Software and legacy Flight Management Systems, reducing cockpit workload while ensuring compliance with stringent global air traffic management protocols.
How did COVID-19 impact Traffic Alert And Collision Avoidance System II (TCAS II) Version 8.1 Upgrades Market and what is the recovery trajectory?
The pandemic severely disrupted airline capital expenditure, causing delayed avionics maintenance cycles. As global passenger traffic rebounded, deferred compliance deadlines spurred a surge in demand for Maintenance Repair And Overhaul Providers to execute critical fleet modifications and catch up on overdue regulatory updates.
Competitive landscape of Traffic Alert And Collision Avoidance System II (TCAS II) Version 8.1 Upgrades Market
Market concentration remains moderately high, dominated by established tier-1 avionics manufacturers and specialized MRO facilities. Companies leverage proprietary testing protocols and strategic partnerships with commercial airlines to secure long-term service contracts and maintain robust competitive moats against emerging market entrants.
Executive summary of key findings for Traffic Alert And Collision Avoidance System II (TCAS II) Version 8.1 Upgrades Market
The data suggests exceptional momentum, with the market projected to reach 3.00 Billion by 2033 at a CAGR of 9.60% from 2027. Regulatory pressure, technological advancements in Traffic Alert Processors, and expanding commercial fleets underpin this robust long-term financial trajectory.
Market forecast and projected growth from 2027 to 2033
Driven by mandatory retrofit timelines and expanding commercial aircraft deliveries, the sector is set for sustained expansion. Growing from its 2026 baseline, the market will achieve a CAGR of 9.60% through 2033, culminating in a valuation of 3.00 Billion as operators rush to meet compliance.
Segmentation analysis of Traffic Alert And Collision Avoidance System II (TCAS II) Version 8.1 Upgrades Market
Categorized by fit (Line Fit, Retrofit), end user (Airlines, OEMs, MROs), hardware (Traffic Alert Processors, Mode S Transponders, Antenna Systems, Display Units, Surveillance Sensors), services, software, component, and aircraft type. Retrofit solutions dominate current demand due to existing global fleet compliance requirements.
Regional market analysis and geographic distribution
Geographic performance reflects regional airspace congestion and strict regulatory oversight. North America and Europe lead adoption due to early mandate implementation by civil aviation authorities, whereas Asia-Pacific displays the fastest-growing demand profile driven by expanding commercial airline fleets and modernization initiatives.
In-depth regional review of key markets
North America retains the largest market share, supported by dense air traffic and stringent FAA oversight. Meanwhile, European airspace mandates create continuous demand for Certification Services and specialized software integration, positioning the region as a vital hub for advanced avionics deployments.
Company profiles and strategic positioning of leading players
Major industry participants such as Honeywell International Inc. and Garmin Ltd. provide core hardware and software solutions, while service specialists like StandardAero Inc., Duncan Aviation Inc., and West Star Aviation LLC excel in executing complex aircraft retrofits and providing localized MRO support.
Porter's Five Forces analysis of the industry
Bargaining power of buyers is moderate to high given the availability of certified MRO alternatives. Threat of new entrants remains low due to high certification barriers, strict aerospace manufacturing standards, and the substantial capital required to develop reliable Traffic Alert Processors.
SWOT analysis for Traffic Alert And Collision Avoidance System II (TCAS II) Version 8.1 Upgrades Market
Strengths include established regulatory backing and proven technology. Weaknesses involve high initial upgrade costs. Opportunities lie in emerging regional airline markets, while threats include potential supply chain disruptions affecting specialized semiconductor components required for Mode S Transponders.
Value chain analysis from raw materials to end-users
The value flow begins with raw material suppliers of semiconductors and specialty metals, progressing to tier-1 component manufacturers, software developers, and system integrators. Finally, MRO providers and OEMs deliver the upgraded systems to commercial airlines, business jet operators, and military fleets.
Investment insights and high-potential areas
High-potential investment pockets center around proprietary Upgrade Software developers and specialized testing service providers. Investors should target firms offering turnkey compliance packages that minimize aircraft downtime for commercial airline operators facing tight scheduling constraints.
Conclusion and key takeaways for stakeholders
The market presents compelling growth prospects underpinned by mandatory safety upgrades. With a projected valuation of 3.00 Billion by 2033, stakeholders must prioritize agile software integration capabilities and strategic partnerships with leading MRO facilities to capture maximum market value.
Research methodology used for market sizing and forecasting
Our analysis triangulates baseline estimates by combining authoritative trade registry data, primary qualitative interviews with C-suite aviation executives, and secondary macroeconomic indicators. This rigorous multi-tiered approach ensures high accuracy in projecting the 9.60% CAGR through 2033.
Scope of the report and coverage parameters
This report covers global revenue trends, volume shipments, and technological evaluations across commercial aircraft, business jets, helicopters, and military fleets. Limitations include exclusion of unregistered private aircraft and uncertified regional retrofit providers operating outside major aviation jurisdictions.
Recent developments, company announcements, and strategic moves
Recent industry activity features collaborative partnerships between major avionics suppliers and MRO networks to streamline STC (Supplemental Type Certificate) approvals. Companies are actively expanding their suite of Diagnostic Software to support rapid fleet integration and compliance verification.