What is the market overview and industry significance of the Key Tag Label Inserts Market?
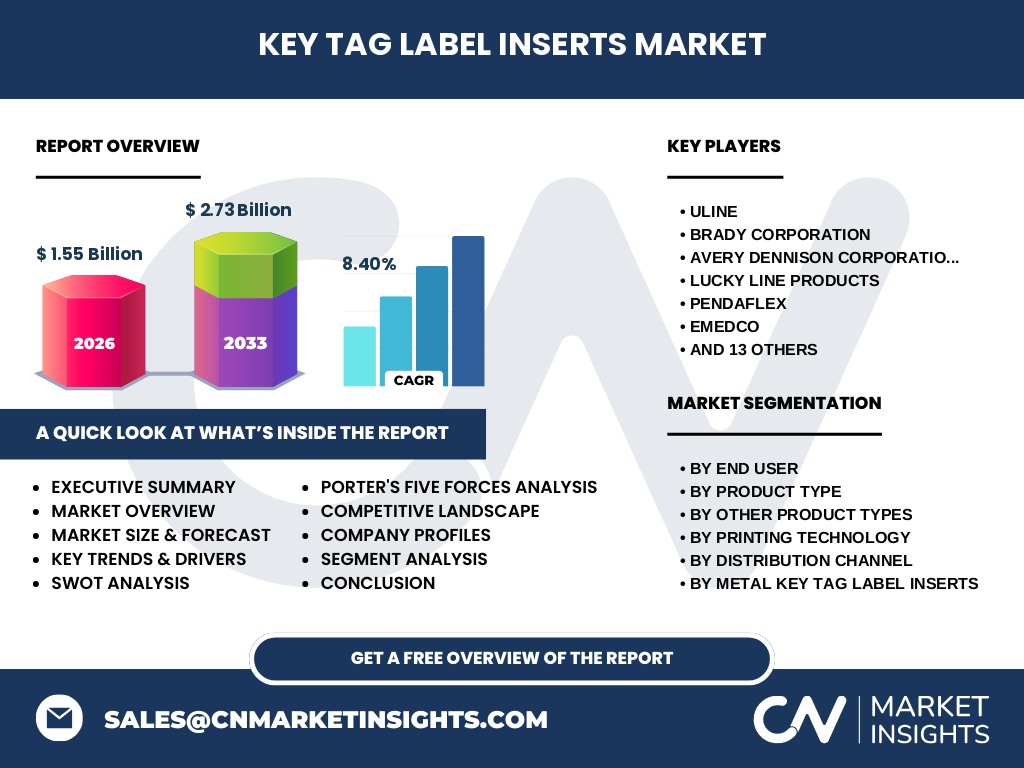
Our analysis indicates that the Key Tag Label Inserts Market reaches a valuation of 1.55 Billion in 2026. This specialized sector underpins global asset management, security compliance, and facility organization across commercial real estate, hospitality, and institutional verticals. Precise identification remains critical for operational security.
Key market drivers, restraints, challenges, and opportunities shaping the Key Tag Label Inserts Market
Growth is propelled by stringent workplace safety mandates and commercial real estate expansion. Conversely, supply chain volatility in petrochemical feedstock for Plastic Key Tag Label Inserts creates margin compression. Strategic opportunities emerge in antimicrobial coatings compliant with OSHA and ISO standards.
Emerging trends and growth patterns in Key Tag Label Inserts Market industry trends
The market demonstrates a profound pivot toward sustainability, with end-users replacing standard vinyl with biodegradable Writable Paper Inserts and recycled aluminum substrates. Digital integration via dynamic barcode printing is transforming traditional metal tags into connected IoT access points.
How did the COVID-19 pandemic impact the Key Tag Label Inserts Market and shape its recovery trajectory?
Pandemic-era office closures caused a temporary contraction in corporate procurement for hospitality and office key management. The post-pandemic recovery features an accelerated rebound as commercial facilities upgrade hygiene protocols, driving robust demand for Waterproof Plastic Inserts and sanitizable Laminated Paper Inserts.
Competitive benchmarking and strategic dynamics in the Key Tag Label Inserts Market analysis
The landscape is characterized by moderate consolidation. Heavyweights like Avery Dennison Corporation and Brady Corporation leverage global distribution to dominate enterprise supply chains, while specialized players focus on bespoke Engraved Metal Inserts for heavy industrial applications.
Executive summary of key findings for the Key Tag Label Inserts Market market size and forecast
Driven by robust demand across institutional verticals, the market is poised to expand from 1.55 Billion in 2026 to 2.73 Billion by 2033, achieving a stellar CAGR of 8.40%. Strategic market entry requires aligning product portfolios with automated thermal printing workflows.
Structural Growth Drivers: Projecting the Key Tag Label Inserts Market forecast from 2027 to 2033
Our predictive models show accelerated expansion, scaling the market from 2027 through 2033 to hit 2.73 Billion by the end of the forecast period. This trajectory is anchored by a consistent 8.40% CAGR, fueled by urbanization and infrastructure development across emerging economies.
Segmentation analysis of product types, end users, and printing technologies
The ecosystem is segmented by End Users (Hotels, Offices, Schools, Hospitals), Product Types (Paper, Plastic, Metal), and Printing Technologies (Thermal, Digital, Offset). Thermal Printing dominates due to its durability on Barcode Label Inserts used in high-throughput asset tracking.
Geographic distribution and regional performance across the global market
Regional consumption patterns mirror industrialization rates and corporate real estate density. North America and Europe account for the lion's share of consumption, driven by strict facility management regulations, while the Asia-Pacific region exhibits the fastest growth due to expanding commercial infrastructure.
In-depth regional review of manufacturing hubs and consumption centers
North America maintains leadership via advanced corporate asset management frameworks. Meanwhile, manufacturing output is increasingly concentrated in Asia-Pacific industrial zones, where low-cost polymer sourcing empowers high-volume production of Transparent Plastic Inserts and Flexible Plastic Inserts.
Company profiles and strategic positioning of leading industry participants
Industry leaders deploy distinct competitive moats. Uline and Avery Dennison Corporation leverage vast distribution networks for commoditized paper goods, whereas SATO Holdings Corporation and Evolis capture high-margin segments via advanced thermal and digital printing hardware integration.
Porter's Five Forces analysis of competitive intensity in the sector
Supplier power remains moderate due to diverse chemical feedstock availability. However, threat of substitution is rising as digital RFID solutions challenge traditional physical tags. Competitive rivalry is fierce among established converters vying for enterprise-level institutional supply contracts.
SWOT analysis of the Key Tag Label Inserts Market landscape
Key strengths lie in low manufacturing unit costs and high product indispensability. Weaknesses involve vulnerability to raw material price swings. Prime opportunities rest in IoT-enabled smart key tags, while regulatory threats center on tightening environmental restrictions regarding PVC plastics.
Value chain analysis from raw material extraction to end-user deployment
The value chain initiates with petrochemical refiners and paper mills supplying base substrates like vinyl and pulp. Converters utilize Digital Printing and Screen Printing technologies before distribution via specialized B2B channels, e-commerce, and industrial hypermarkets to final facility operators.
Investment insights and high-potential growth pockets for market entrants
Investors should target manufacturers specializing in eco-friendly alternatives, particularly Durable Metal Tags and biodegradable Color Coded Paper Inserts. High-margin opportunities exist in custom thermal-printable solutions catering to healthcare asset tracking and hospitality automation.
Conclusion and key takeaways for strategic decision-makers
The Key Tag Label Inserts Market offers robust expansion potential, backed by an impressive 8.40% CAGR leading to 2.73 Billion by 2033. Success demands agility in material sourcing, environmental compliance, and integration with automated printing technologies.
Research methodology for data triangulation and baseline estimation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with C-suite executives at Brady Corporation and CCL Industries Inc., and secondary macroeconomic indicators tracking commercial real estate build-outs.
Scope of the report, coverage parameters, and analytical limitations
This report evaluates global market dynamics for key tag label inserts across all major product categories, printing methods, and distribution channels. Limitations include unpredictable geopolitical shifts impacting localized supply chains for Aluminum Label Inserts and Stainless Steel Label Inserts.
Recent developments, strategic partnerships, and product launches across the industry
Recent market activity highlights sustainability mandates, with firms rolling out post-consumer recycled plastic substrates. Strategic acquisitions by industry consolidators like CCL Industries Inc. aim to expand regional footprints in thermal printing media and proprietary Custom Designed Inserts.