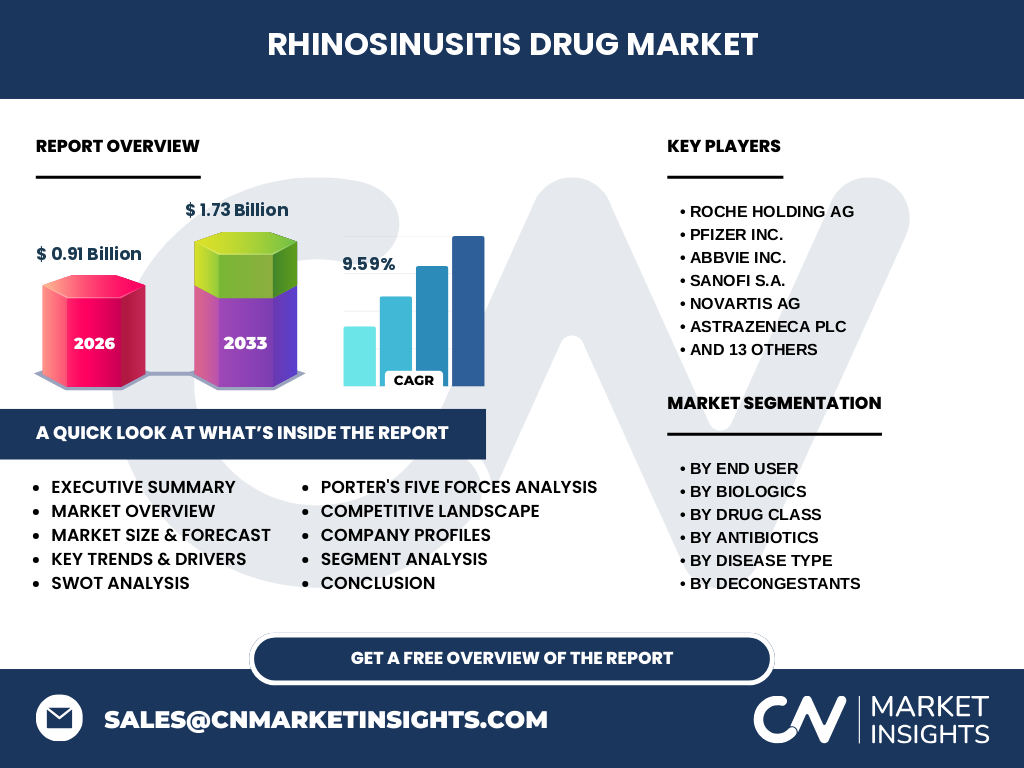
Market overview of the Rhinosinusitis Drug Market
Our analysis indicates that the Rhinosinusitis Drug Market represents a critical pharmaceutical segment valued at 0.91 Billion in 2026. This sector encompasses pharmacological interventions for acute and chronic sinus inflammations, utilizing active pharmaceutical ingredients distributed globally via major ports in Europe and Asia. Regulatory oversight by the FDA and EMA governs the complex supply chain, from raw chemical synthesis to finished nasal sprays and biologics.
Key market drivers, restraints, challenges, and opportunities in the Rhinosinusitis Drug Market
Growth is propelled by rising urban air pollution and high prevalence of chronic rhinosinusitis with nasal polyps. However, strict EMA and FDA approval pathways for novel biologics act as a restraint, alongside stringent cold-chain logistical hurdles for monoclonal antibodies. Lucrative opportunities persist in developing targeted cytokine inhibitors, allowing innovators to capture significant market share amidst growing demand for precision medicine.
Emerging trends and growth patterns in the Rhinosinusitis Drug Market
The shift toward biological therapies is transforming the Rhinosinusitis Drug Market industry trends, driven by increased adoption of monoclonal antibodies. Patients increasingly favor non-surgical management, pushing manufacturers to innovate in advanced nasal administration and combination therapies. This trend favors companies possessing robust R&D pipelines in targeted immunology, addressing severe cases unresponsive to traditional corticosteroids and antibiotics.
COVID-19 impact analysis and recovery trajectory
The pandemic caused temporary supply chain disruptions for basic raw materials used in penicillins and oral decongestants, alongside a sharp decline in elective otolaryngology visits. Recovery has been robust, as telehealth adoption and heightened awareness of respiratory health accelerated prescription volumes. Based on our research, post-pandemic demand has normalized above historical baselines, driven by renewed clinical focus on upper respiratory pathways.
Competitive landscape and strategic dynamics
The Rhinosinusitis Drug Market analysis reveals a moderately consolidated landscape dominated by global pharmaceutical giants such as Pfizer Inc., Sanofi S.A., and AstraZeneca Plc. These leaders leverage extensive distribution networks and heavy R&D investments to maintain dominance, while nimble generic players like Dr. Reddy's Laboratories Limited and Cipla Limited compete fiercely in the established antibiotic and corticosteroid segments.
Executive summary of the Rhinosinusitis Drug Market
Our comprehensive evaluation highlights a projected expansion to 1.73 Billion by 2033, expanding at a robust CAGR of 9.59% from 2027 to 2033. This impressive trajectory is anchored by expanding indications for biologics and rising chronic disease prevalence. Industry stakeholders must pivot toward advanced biologics and patient-centric nasal delivery platforms to capitalize on shifting consumer preferences.
Market forecast from 2027 to 2033
The data suggests steady acceleration, lifting the market from its 2026 baseline of 0.91 Billion toward the 1.73 Billion threshold by 2033. This trajectory reflects an expected compound annual growth rate of 9.59%. Expansion will be particularly pronounced in emerging Asian economies as healthcare infrastructure improves and patient access to specialty ear, nose, and throat clinics widens.
Segmentation analysis across product and disease categories
The market is comprehensively segmented by drug class, biologics, disease type, and route of administration. Key categories include antibiotics, corticosteroids, antihistamines, and decongestants, addressing conditions ranging from acute rhinosinusitis to allergic fungal variations. Nasal administration and oral administration dominate delivery routes, while specialty clinics and hospitals serve as primary distribution end-users.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with North America currently commanding the largest revenue share due to high healthcare expenditure and advanced diagnostic rates. Meanwhile, Asia-Pacific represents the fastest-growing regional market, driven by expanding pharmaceutical manufacturing hubs in India and China, alongside increasing air pollution levels that exacerbate chronic sinus conditions across urban centers.
In-depth regional review of key markets
North American growth is underpinned by favorable reimbursement policies for specialty biologic therapies from major insurers. In contrast, the European market exhibits steady, regulated demand supervised closely by the European Medicines Agency. The Latin American and Middle Eastern markets display high untapped potential, though constrained by uneven distribution logistics and variable regulatory harmonization across national borders.
Company profiles and strategic positioning
Industry leaders like Regeneron Pharmaceuticals Inc. and Novartis AG focus heavily on high-margin biologic innovations for severe nasal polyp cases. Meanwhile, generic powerhouses such as Aurobindo Pharma Limited and Teva Pharmaceutical Industries Limited prioritize volume manufacturing of foundational penicillins and antihistamines, securing resilient revenue streams across global retail pharmacy chains.
Porter's Five Forces analysis
Competitive rivalry is intense among established generics manufacturers, while the threat of new entrants remains moderate due to stringent FDA bioequivalence standards and high capital requirements for biologics R&D. Bargaining power of buyers is tempered by physician brand loyalty, whereas supplier power over chemical raw materials is low given numerous active API synthesis providers globally.
SWOT analysis of the Rhinosinusitis Drug Market
Strengths include robust pipelines of targeted monoclonal antibodies and established global supply chains for standard decongestants. Weaknesses involve high treatment costs for advanced biologics. Opportunities lie in expanding telemedicine consultations for chronic sufferers, while threats include potential generic price erosion and stringent environmental regulations governing chemical API manufacturing facilities.
Value chain analysis from raw materials to end-users
The value chain initiates with basic petrochemical and biochemical raw material synthesis by API manufacturers in India and China. Intermediates are then formulated into tablets, nasal sprays, and injectables by multinational pharmaceutical companies, and finally distributed through global logistics networks to hospitals, ambulatory surgical centers, and retail homecare settings.
Investment insights and high-potential areas
Strategic investors should direct capital toward companies pioneering subcutaneous and sublingual immunotherapy drugs, as well as novel cytokine inhibitors. These segments offer superior margins and address unmet clinical needs in chronic rhinosinusitis patients unresponsive to standard intranasal corticosteroids and antibiotic regimens.
Conclusion and key takeaways
The Rhinosinusitis Drug Market presents compelling long-term fundamentals, projected to reach 1.73 Billion by 2033 at a 9.59% CAGR. Success in this evolving sector requires balancing high-margin biologic innovation with efficient supply chain management for essential generic medications across global markets.
Research methodology for baseline estimates
Our estimates are rigorously triangulated by synthesizing proprietary trade registry data, customs import-export records for pharmaceutical intermediates, and primary stakeholder interviews with leading otolaryngologists and pharmaceutical executives. This bottom-up modeling is cross-verified against secondary macroeconomic indicators and national health expenditure databases.
Scope of the report and coverage parameters
This report covers global revenue performance from 2026 to 2033 across all major drug classes, delivery routes, and end-user segments. Excluded from this scope are surgical intervention hardware and over-the-counter herbal remedies lacking formal pharmacological validation from recognized national drug regulatory authorities.
Recent developments, partnerships, and strategic moves
Recent industry momentum features major licensing agreements between biotech innovators and global pharma firms to co-develop monoclonal antibodies. Companies such as GSK Plc and Boehringer Ingelheim International GmbH have recently announced expanded clinical trial phases for advanced biologic formulations targeting severe chronic rhinosinusitis.