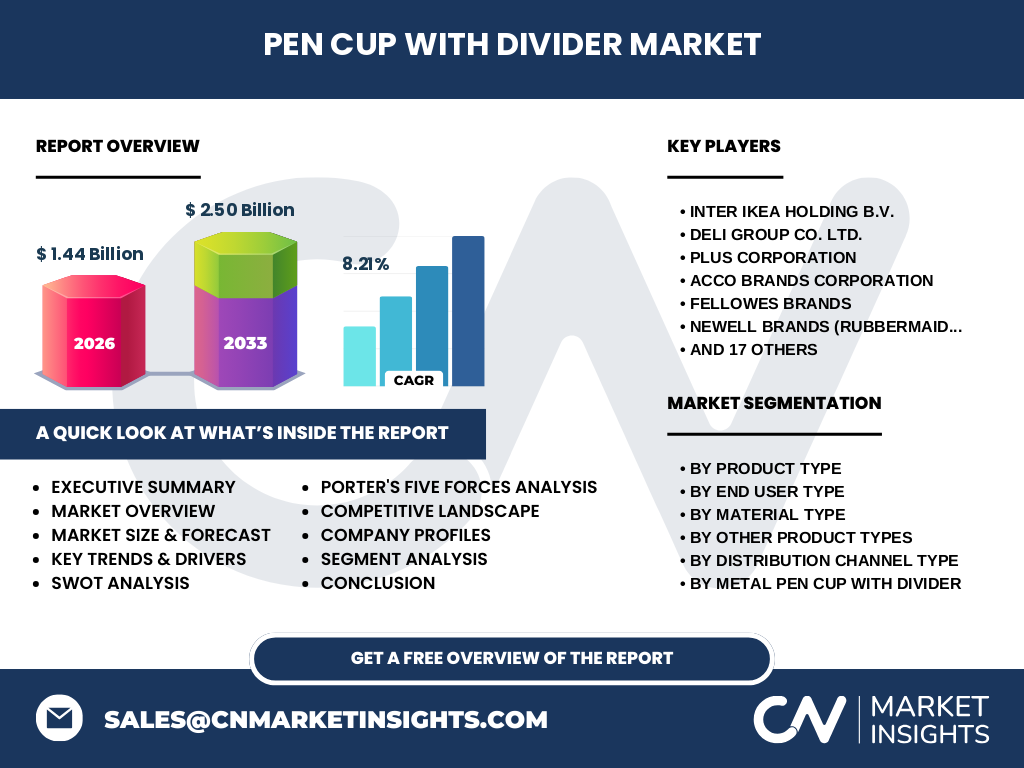
Market overview of the Pen Cup With Divider Market
Our analysis indicates the Pen Cup With Divider Market valuation reaches $1.44 Billion in 2026. This sector encompasses desk organization tools featuring structural partitions, driven by modern corporate ergonomic standards and professional workspace optimization requirements across global commercial hubs.
Key market drivers, restraints, challenges, and opportunities
Growth is accelerated by hybrid work models, though supply chain bottlenecks for polymer and aluminum raw materials create margin pressures. Opportunities lie in sustainable, eco-friendly procurement mandates enforced by regional environmental protection agencies globally.
Emerging trends and growth patterns in desk organization
The shift toward minimalist aesthetic and biophilic design has surged demand for bamboo and cork wood variants. Manufacturers increasingly leverage recycled plastics and modular designs to capture premium B2B office supply contracts.
COVID-19 impact analysis and recovery trajectory
Pandemic-era remote work initiatives temporarily depressed commercial desk accessories demand. The subsequent post-2021 recovery trajectory is propelled by corporate office redesigns and the corporate shift toward sanitized, dedicated multi-compartment workstation accessories.
Competitive landscape and strategic market concentration
Market concentration remains moderately fragmented, featuring global giants like Inter IKEA Holding B.V., Deli Group Co. Ltd., and ACCO Brands Corporation leveraging expansive distribution networks to outpace regional stationery manufacturers.
Executive summary of key findings
Based on our research, the market demonstrates robust expansion, scaling from $1.44 Billion in 2026 to $2.50 Billion by 2033 at a 8.21% CAGR, fueled by commercial workspace modernization and premium organizational solutions.
Market forecast from 2027 to 2033
The data suggests steady market ascension, projecting growth from $1.44 Billion in 2026 to reach $2.50 Billion by 2033. This consistent trajectory reflects rising corporate investments in employee workstation productivity and aesthetics.
Segmentation analysis across product, end-user, and material types
Segmentation is categorized by product type (Single Divider, Multiple Dividers, Stackable, Rotating), end-user (Individual, Commercial, Educational), and material (Plastic, Metal, Wood, Composite). Commercial end-users and multi-compartment configurations dominate enterprise procurement budgets.
Regional market analysis and geographic distribution
Geographic performance is led by North America and Europe, supported by stringent corporate procurement guidelines. Meanwhile, Asia-Pacific exhibits the fastest regional growth, driven by rapid urban commercial real estate development and expanding office infrastructure.
In-depth regional review of key markets
North American demand centers on ergonomic desk accessories, whereas European markets prioritize eco-labeled, sustainable materials under strict regulatory compliance frameworks overseen by regional environmental agencies and trade unions.
Company profiles and strategic positioning
Industry leaders like Muji, Fellowes Brands, and Newell Brands (Rubbermaid) employ distinct strategies, ranging from sleek aesthetic minimalism to heavy-duty commercial durability, securing dominant positions in global B2B procurement channels.
Porter's Five Forces analysis of competitive pressures
Rivalry is intense due to low product differentiation among commodity plastics, while supplier power over raw polymers remains moderate. Threat of substitution from digital planning tools is offset by tactile workspace preferences.
SWOT analysis of the industry ecosystem
Strengths include versatile manufacturing techniques; weaknesses involve vulnerability to raw material price volatility. Opportunities emerge in direct-to-consumer corporate gifting, while threats include low-cost counterfeit desktop accessories flooding e-commerce channels.
Value chain analysis from raw materials to end-users
The value chain flows from petrochemical and timber extraction to injection molding or woodworking hubs, passing through major logistics ports before reaching commercial distributors, e-commerce fulfillment centers, and end enterprise consumers.
Investment insights and high-potential areas
Investors should target premium modular and composite material producers capable of scaling through digital B2B marketplaces. High-margin opportunities exist in sustainable, certified eco-friendly desk organizers targeting enterprise ESG initiatives.
Conclusion and key takeaways for stakeholders
With a projected valuation of $2.50 Billion by 2033, stakeholders must prioritize sustainable material innovation and omnichannel distribution to capture high-value enterprise contracts in a competitive landscape.
Research methodology and data triangulation
Our findings combine quantitative trade registry data, primary stakeholder interviews with procurement directors, and secondary macroeconomic indicators to synthesize baseline estimates and validate market sizing models.
Scope of the report and coverage parameters
This report covers global revenue performance across specified material and end-user segments from 2026 to 2033, excluding custom bespoke artisanal desk accessories outside of commercial manufacturing parameters.
Recent developments and strategic industry moves
Recent strategic moves include ACCO Brands Corporation and Kokuyo Co. Ltd. launching recycled-content desk lines and expanding automated warehousing near major shipping ports to optimize B2B fulfillment efficiency.