Market overview and industry significance of the Reusable Trocars System Market
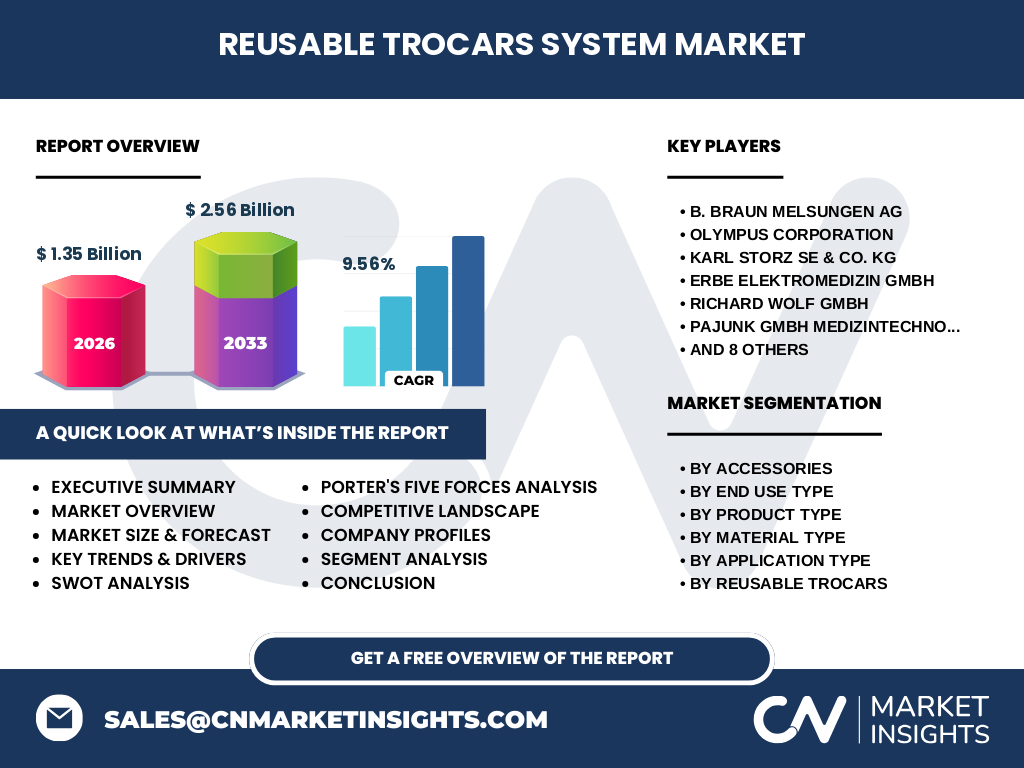
The Reusable Trocars System Market is valued at 1.35 Billion in 2026, representing a critical sector within minimally invasive surgery. Our analysis indicates that high-grade surgical steel and advanced composite materials are foundational to manufacturing durable obturators, trocar sleeves, and sealing valves. Regulatory compliance with bodies like the FDA and EMA remains paramount for manufacturers deploying these reusable surgical instruments across global healthcare infrastructures.
Structural Growth Drivers and Market Restraints
Growth is propelled by a rising volume of laparoscopic procedures globally, though stringent sterilization protocols and initial capital expenditure act as notable restraints. The market faces logistical hurdles in supply chains for specialized polymer components and cleaning brushes. Regulatory mandates regarding biocompatibility testing by agencies such as the ISO add compliance complexity for market entrants aiming to scale production.
Emerging Industry Trends in the Reusable Trocars System Market
A definitive shift toward sustainability in operating rooms is accelerating the adoption of hybrid material systems and valve-less reusable cannulas. Hospitals are increasingly prioritizing reusable trocars over disposable alternatives to curb medical waste. Technological advancements focus on ergonomic housing and advanced optical viewing capabilities to enhance precision during complex general and gynecological procedures.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic severely disrupted elective surgeries, causing temporary supply chain bottlenecks for raw stainless steel and specialized sealing caps. Post-pandemic recovery has been robust, driven by surgical backlogs and a renewed hospital focus on supply chain resilience. Facilities diversified their procurement strategies to mitigate future logistical disruptions for essential surgical accessories.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features established innovators like B. Braun Melsungen AG, Olympus Corporation, and KARL STORZ SE & Co. KG, who dominate through extensive distribution networks. Market concentration is moderate-to-high, with industry leaders leveraging proprietary locking mechanisms and modular designs. Strategic mergers and OEM partnerships remain key tactics for expanding regional footprints and portfolio depth.
Executive Summary of the Reusable Trocars System Market
Our research projects the Reusable Trocars System Market to expand from 1.35 Billion in 2026 to 2.56 Billion by 2033, achieving a robust CAGR of 9.56%. This trajectory underscores a fundamental transition toward cost-effective, sustainable surgical instrumentation. Key stakeholders must invest in advanced material science and automated reprocessing compatibility to capture outsized market share.
Long-Term Market Forecast from 2027 to 2033
Driven by a steady 9.56% CAGR, the market is set to reach 2.56 Billion by 2033 from its 2026 baseline of 1.35 Billion. This expansion is underpinned by rising healthcare expenditures in emerging economies and the continuous expansion of ambulatory surgical centers requiring durable, multi-use laparoscopic infrastructure.
Segmentation Analysis of Reusable Trocars Systems
The market segments by product type into reusable trocars, cannulas, and accessories like sealing caps and reducers. Material types range from stainless steel to polymer composites and hybrid systems. End-use categories span hospitals, ambulatory surgical centers, and specialty clinics, while application scope covers laparoscopic, general, gynecological, and urological surgeries utilizing 5mm to 15mm diameter sizes.
Geographic Distribution and Regional Market Performance
Regional performance varies based on hospital infrastructure density and local reimbursement policies for reusable medical devices. North America and Europe currently command significant revenue shares due to stringent green-hospital initiatives. Meanwhile, Asia-Pacific represents the fastest-growing frontier, fueled by expanding healthcare access and modernization of surgical suites in metropolitan hubs.
In-Depth Regional Review and Local Market Constraints
European markets enforce rigorous reprocessing standards governed by regional health authorities, favoring high-grade stainless steel systems from manufacturers like Erbe Elektromedizin GmbH and Richard Wolf GmbH. In contrast, North American adoption is heavily influenced by group purchasing organizations (GPOs) and cost-per-procedure models, challenging suppliers to demonstrate long-term durability and lower total cost of ownership.
Company Profiles and Strategic Positioning
Industry participants such as PAJUNK GmbH Medizintechnologie, Grena Ltd., and Ackermann Instrumente GmbH focus on specialized ergonomic designs and modular offerings. Companies like Bharat Surgical Co. and Gimmi GmbH leverage cost-competitive manufacturing capabilities to capture emerging market demand, while firms like Olympus Corporation integrate trocars seamlessly with advanced visualization platforms.
Porter's Five Forces Analysis of the Industry
Supplier power remains moderate due to the specialized nature of medical-grade raw materials. Buyer power is elevated through hospital GPOs negotiating volume discounts. Threat of substitutes is mitigated by the clinical preference for tactile feedback in reusable instruments, whereas industry rivalry is intense, driven by continuous product iteration from established European and Asian medical device makers.
SWOT Analysis of the Reusable Trocars System Market
Strengths include the superior durability and ecological benefits of stainless steel and hybrid systems. Weaknesses involve complex sterilization validation requirements. Opportunities lie in expanding ambulatory surgical center penetration across developing economies. Threats stem from stringent regulatory compliance audits and potential supply chain vulnerabilities for specialized polymer components.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material sourcing of medical-grade stainless steel and engineering polymers, followed by precision CNC machining and assembly. Distributors and logistics providers transport finished trocar sleeves and obturators through major maritime and air cargo hubs to hospital central sterile services departments (CSSD) for end-use deployment.
Investment Insights and High-Potential Areas
High-potential investment opportunities concentrate on the development of hybrid material systems and valve-less reusable cannulas that reduce gas leakage during extended laparoscopic procedures. Venture capital and private equity are increasingly targeting manufacturers offering integrated cleaning brushes and automated reprocessing solutions to address hospital labor shortages in CSSD units.
Conclusion and Strategic Key Takeaways
The Reusable Trocars System Market offers compelling growth prospects, projected to reach 2.56 Billion by 2033 at a 9.56% CAGR. Success in this landscape requires rigorous alignment with hospital sustainability goals, adherence to evolving regulatory standards, and continuous innovation in ergonomic, corrosion-resistant surgical instrument design.
Research Methodology and Data Triangulation
Baseline estimates are triangulated by combining exhaustive trade registry data, customs import-export logs, and primary stakeholder interviews with chief medical officers and procurement directors. Secondary macroeconomic indicators, including healthcare expenditure reports and surgical volume databases, are cross-referenced to validate market sizing and forecast models.
Scope of the Report and Coverage Parameters
This comprehensive report evaluates the global Reusable Trocars System Market across product types, accessories, materials, applications, diameters, and end-use sectors. Geographic coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Limitations include excluding single-use disposable trocars except for comparative market analysis.
Recent Developments and Strategic Industry Moves
Recent market activities involve strategic distribution agreements and product launches focusing on ergonomic bladed and bladeless reusable trocars. Companies such as Rudolf Medical GmbH and WISAP Medical Technology GmbH have invested in advanced surface-treatment technologies to enhance corrosion resistance during repeated steam sterilization cycles, strengthening their competitive positioning.