What is the market overview and industry significance of the Artificial Intelligence (AI)-Enabled Battlefield Management And Decision Support Systems Market?
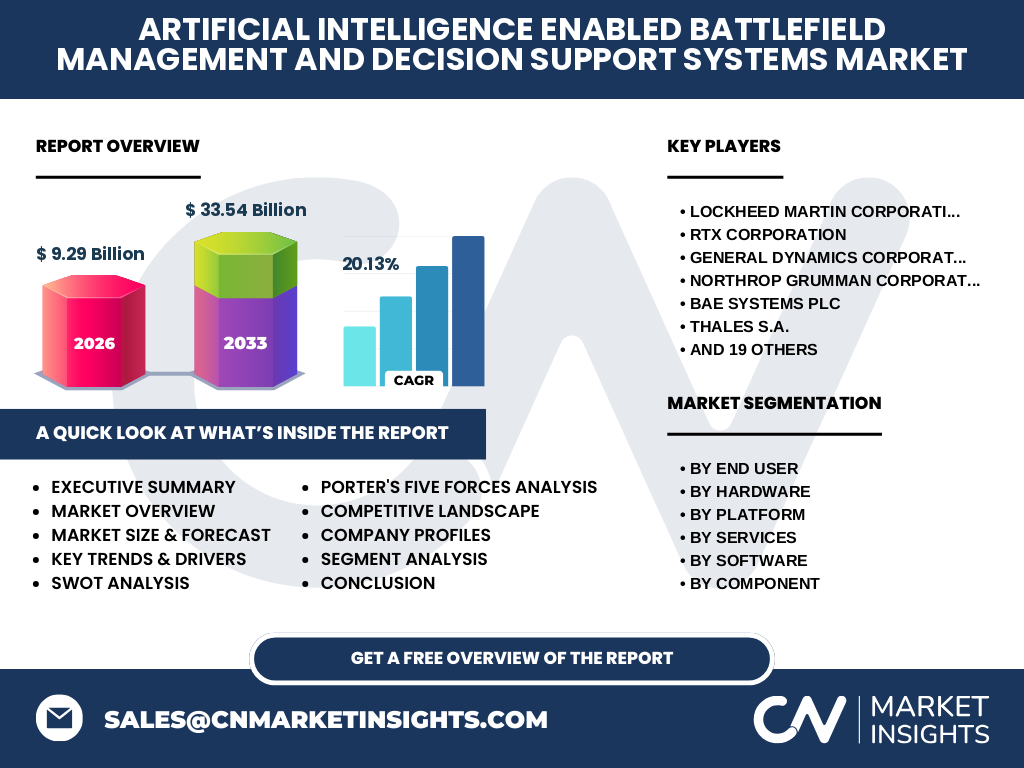
Our analysis indicates that the Artificial Intelligence (AI)-Enabled Battlefield Management And Decision Support Systems Market represents a critical paradigm shift in modern military operations. Valued at 9.29 Billion in 2026, this sector integrates advanced algorithms with hardware like edge computing devices to process multi-domain combat data, ensuring decisive technological superiority.
Structural Growth Drivers and Restraints
The market is propelled by escalating geopolitical tensions requiring rapid data fusion and automated threat analysis. However, rigorous ITAR regulations, strict military-grade hardware certification hurdles, and vulnerabilities in neural network cybersecurity act as prominent restraints, challenging procurement timelines across allied defense ministries.
Emerging industry trends in the Artificial Intelligence (AI)-Enabled Battlefield Management And Decision Support Systems Market
Industry trends highlight a rapid migration toward decentralized edge AI architectures. Defense contractors are increasingly combining Battlefield Data Fusion And Visualization Software with autonomous unmanned platforms to reduce cognitive overload for commanders operating in contested electromagnetic spectrum environments.
How did the COVID-19 pandemic impact the Artificial Intelligence (AI)-Enabled Battlefield Management And Decision Support Systems Market?
The pandemic exposed vulnerabilities in global semiconductor supply chains, temporarily stalling the production of specialized radar imaging systems and edge processors. Nevertheless, post-COVID recovery trajectories accelerated digital transformation budgets, as ministries prioritized resilient, cloud-enabled command frameworks to maintain operational continuity.
Competitive Benchmarking
The competitive landscape features a distinct dichotomy between legacy prime contractors like Lockheed Martin Corporation and RTX Corporation, and agile innovators like Palantir Technologies and Shield AI. While primes dominate heavy naval and airborne platforms, software-first entrants capture significant market share in rapid algorithmic decision support.
Executive summary of the Artificial Intelligence (AI)-Enabled Battlefield Management And Decision Support Systems Market
Our comprehensive findings show that the Artificial Intelligence (AI)-Enabled Battlefield Management And Decision Support Systems Market is poised for explosive expansion. Driven by an impressive 20.13% CAGR, market value will surge from 9.29 Billion in 2026 to 33.54 Billion by 2033, transforming global defense architectures.
Market forecast trajectory from 2027 to 2033
Based on our research, the market will experience sustained hyper-growth over the forecast period. Reaching 33.54 Billion by 2033 at a 20.13% CAGR, expansion will be heavily sustained by recurring software licensing, continuous integration upgrades, and large-scale procurement of autonomous systems coordination applications.
Segmentation analysis of components, platforms, and applications
The market is segmented by components (hardware, software, services), platforms (airborne, naval, land, space), and end users (army, navy, air force). Software dominates critical intelligence surveillance and reconnaissance missions, while hardware foundations like sensors and networking equipment anchor physical deployments.
Geographic distribution and regional performance
North America retains the dominant revenue share, underpinned by robust Department of Defense R&D budgets and Silicon Valley partnerships. Meanwhile, the Asia-Pacific region demonstrates the fastest growth rate, fueled by military modernization initiatives in nations like India, supported by domestic entities such as Bharat Electronics Limited.
In-depth regional review of key defense markets
European markets are prioritizing interoperability under NATO frameworks, benefiting regional leaders like BAE Systems plc, Thales S.A., and Rheinmetall AG. Concurrently, North American procurement focuses heavily on Joint All-Domain Command and Control initiatives, directly boosting demand for advanced AI analytics platforms.
Strategic positioning in company profiles
Industry leaders utilize distinct strategic approaches. General Dynamics Corporation and Northrop Grumman Corporation leverage massive platform integration capabilities, whereas niche specialists like C3.ai Inc. and Anduril Industries Inc. focus on scalable, cloud-native artificial intelligence and autonomous drone orchestration.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to specialized rare-earth material dependencies for advanced radar sensors. However, buyer power is low given strict national security procurement vetting, while threat of substitution is minimal owing to the irreplaceable nature of sovereign tactical AI software.
SWOT analysis of the defense technology ecosystem
Key strengths include unmatched real-time data processing capabilities and superior situational awareness. Weaknesses involve high algorithmic opacity. Opportunities lie in expanding managed defense IT cloud services, while threats stem from adversarial electronic warfare and sophisticated neural network poisoning attacks.
Value chain analysis from raw materials to end-users
The value chain initiates with semiconductor foundries and rare-earth mineral processors supplying raw hardware components. These feed into original equipment manufacturers building edge servers, which are subsequently integrated with proprietary software by firms like Leidos Holdings Inc. before final deployment to military end-users.
Investment insights and high-potential focus areas
Our analysis indicates that high-potential investment opportunities concentrate on edge computing devices, cybersecurity threat intelligence software, and automated logistics optimization. Venture capital and defense funds should target agile innovators bridging the gap between commercial AI and tactical military requirements.
Conclusion and key takeaways for stakeholders
The transition toward AI-driven warfare is irreversible. With the market reaching 33.54 Billion by 2033, stakeholders must prioritize software modularity, robust cybersecurity, and open-architecture compliance to secure long-term contracts within this rapidly evolving global defense landscape.
Research methodology for baseline estimates
Our baseline estimates are rigorously triangulated. We combine primary stakeholder interviews with senior defense officials, exhaustive analysis of defense trade registries, and secondary macroeconomic indicators, ensuring highly accurate market sizing for the Artificial Intelligence (AI)-Enabled Battlefield Management And Decision Support Systems Market.
Scope of the report and coverage parameters
This report covers global deployment dynamics across army, navy, and air force sectors from 2026 to 2033. Limitations include the exclusion of classified black-budget military programs and unverified proprietary defense startup revenues operating outside recognized procurement channels.
Recent developments in industry partnerships and product launches
Recent months have seen accelerated strategic partnerships between traditional defense primes and AI pioneers. Companies are aggressively deploying cloud-based mission planning software and autonomous swarm coordination tools, reflecting rapid commercial technology adoption by organizations such as Saab AB and Kratos Defense & Security Solutions Inc.