What is the baseline market overview for the Process Equipment Market?
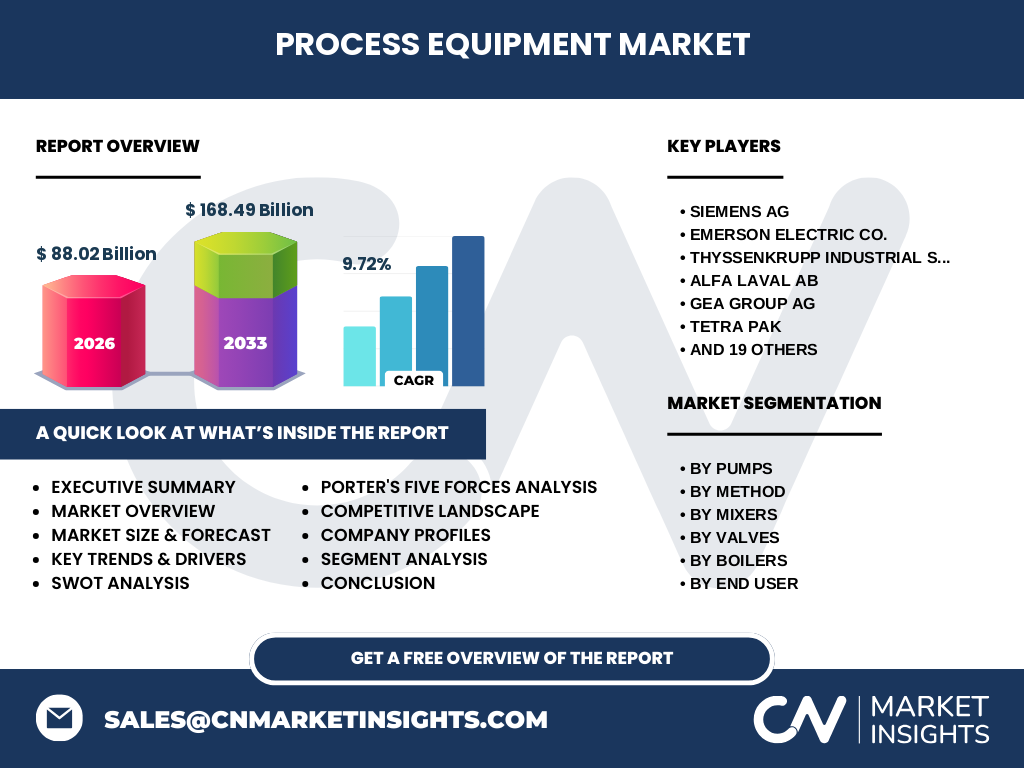
The Process Equipment Market represents a foundational industrial sector encompassing specialized machinery utilized across chemical synthesis, energy generation, and food processing. Valued at 88.02 Billion in 2026, the industry underpins global manufacturing by facilitating fluid handling, thermal transfer, and separation operations essential for continuous and batch production lines worldwide.
Structural Growth Drivers and Restraints shaping the Process Equipment Market
Rapid industrialization across emerging economies acts as a primary catalyst, while stringent environmental mandates enforced by regulatory bodies like the EPA and EU create operational headwinds. Our research indicates that strict compliance requirements for emissions and wastewater treatment compel capital-intensive retrofitting, shifting demand toward advanced filtration and high-efficiency heat exchangers.
Emerging trends and transformation patterns in the Process Equipment Market
The integration of predictive maintenance and Internet of Things (IoT) architecture is fundamentally altering plant operations. Asset monitoring solutions provided by innovators like Emerson Electric Co. and Siemens AG allow operators to minimize unplanned downtime in critical compressor and pump assemblies, maximizing overall equipment effectiveness.
How did the COVID-19 pandemic impact the Process Equipment Market and shape its recovery?
Pandemic-induced supply chain disruptions and localized lockdowns severely constrained capital expenditure for heavy industrial machinery through 2020. However, the post-pandemic recovery trajectory has been exceptionally robust, driven by automated manufacturing investments and reshoring initiatives designed to insulate supply chains against future logistical bottlenecks.
Competitive Benchmarking within the Process Equipment Market
Market concentration remains moderately fragmented, featuring diversified conglomerates alongside specialized engineering firms. Industry leaders such as Flowserve Corporation, Alfa Laval AB, and Sulzer Ltd. dominate through proprietary fluid dynamics technologies and expansive global service footprints, continually outpacing regional competitors in patent generation.
Executive Summary of the Process Equipment Market
Driven by robust demand across chemical and energy verticals, the global sector is poised for sustained expansion. We project the market will surge from 88.02 Billion in 2026 to reach 168.49 Billion by 2033, expanding at a remarkable CAGR of 9.72% throughout the forecast horizon.
Market Forecast and Valuation Trajectory (2027 to 2033)
Accelerated deployment of advanced automation systems and stringent purity standards in biopharmaceuticals will propel stellar financial growth. The data confirms a high-growth trajectory, scaling the valuation from the 2026 baseline to 168.49 Billion by 2033, underpinned by an impressive 9.72% CAGR fueled by continuous process optimization.
Segmentation Analysis of the Process Equipment Market
The industry spans multiple critical categories designed for diverse operational parameters:
- By Equipment Type: Conveyor Systems, Filtration Systems, Mixers, Pumps, Compressors, Valves, Heat Exchangers, Boilers, Cooling Towers, and Reactors.
- By Operation Type: Continuous Process Equipment and Batch Process Equipment.
- By Material of Construction: Stainless Steel Equipment, Carbon Steel Equipment, Alloy Based Equipment, and Other Materials.
Regional Market Analysis and Geographic Performance
Geographic performance exhibits distinct regional specializations, with Asia-Pacific leading in capacity additions due to aggressive petrochemical investments in China and India. North America and Europe prioritize technological upgrades, focusing on energy-efficient retrofits to comply with stringent local environmental standards and carbon-reduction targets.
In-depth Regional Review of Industrial Hubs
Industrial corridors in Western Europe and the United States exhibit high demand for modular, skid-mounted processing units that minimize on-site installation time. Meanwhile, rapid infrastructure development in Southeast Asia drives massive procurement volumes for heavy-duty pumps, centrifugal compressors, and robust boiler systems.
Strategic Company Profiles in the Process Equipment Industry
Key market participants leverage distinct competitive strategies to capture share. GEA Group AG and Tetra Pak specialize in hygienic processing equipment for the food and beverage sectors, while thyssenkrupp Industrial Solutions and Flowserve Corporation focus on heavy-duty chemical reactors and severe-service valve technologies for petrochemical refineries.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers is moderate due to the specialized nature of custom reactors and heat exchangers, whereas supplier power remains low given the commoditized nature of raw carbon and stainless steel inputs. The threat of substitutes is minimal, restricted by strict ASME and ISO certification requirements governing pressure vessels.
SWOT Analysis of the Process Equipment Sector
Key strengths lie in robust engineering expertise and high switching costs for installed processing lines. Conversely, vulnerabilities stem from exposure to volatile raw material costs. Growth opportunities abound in green hydrogen production equipment, though regulatory compliance hurdles and geopolitical trade friction present persistent operational threats.
Value Chain Analysis from Raw Materials to End-Users
The value stream initiates with raw material sourcing of stainless steel, nickel alloys, and specialized polymers. Component fabricators and metallurgical specialists process these inputs into engineered valves, pumps, and heat exchangers. System integrators then assemble these components for end-users spanning oil and gas, power generation, and automotive manufacturing.
Investment Insights and High-Potential Growth Areas
Strategic investors should direct capital toward digitalized, energy-saving continuous process equipment and specialized membrane filtration systems. High-potential opportunities center on equipment designed for green energy transition applications, including carbon capture facilities and next-generation biofuel synthesis plants.
Conclusion and Strategic Takeaways
The industry presents compelling growth dynamics, anchored by an anticipated valuation of 168.49 Billion by 2033. Success in this evolving landscape requires continuous R&D investment in smart, connected machinery that satisfies both rigorous output demands and strict international environmental protocols.
Research Methodology for Baseline Estimation
Our research methodology employs a rigorous triangulation model combining primary stakeholder interviews with C-level executives, exhaustive secondary analysis of trade registries, and macroeconomic indicators. Bottom-up data aggregation from major manufacturing hubs is cross-validated against top-down macroeconomic forecasts to ensure absolute analytical accuracy.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for process equipment across six major end-user verticals and fifteen distinct product segments from 2026 through 2033. Geographic scope encompasses North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, excluding localized custom fabrication shops operating below regional revenue thresholds.
Recent Developments and Strategic Industry Moves
Recent market activity highlights an acceleration of strategic acquisitions and eco-friendly product launches. Industry leaders are actively expanding their digital service portfolios and investing in advanced alloy manufacturing techniques to withstand highly corrosive chemical processing environments and meet evolving customer sustainability mandates.