What is the market overview and industry significance of the Recombinant Humanized Collagen Market?
Our analysis indicates that the Recombinant Humanized Collagen Market represents a paradigm shift from animal-derived tissue extraction to precision genetic engineering. Valued at $2.08 Billion in 2026, this sector eliminates zoonotic transmission risks inherent in bovine or porcine sources. Innovators utilize yeast, bacterial, and mammalian cell systems to synthesize bio-identical structures, revolutionizing biomedical and cosmetic applications globally.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
Growth is propelled by rising demand for animal-free biomaterials and stringent FDA and NMPA purity standards. However, high upstream fermentation costs and complex downstream purification remain formidable restraints. Significant opportunities lie in scaling Pichia pastoris and E. coli expression platforms to lower production barriers for high-yield pharmaceutical grades.
The Shift Toward Bio-Synthetic Precision and Advanced Biomaterials
Industry trends reveal a rapid pivot from native animal extraction toward precisely engineered peptide and cross-linked collagen variants. Companies increasingly leverage genetic profiling to design recombinant chains with tailored thermal stability and cell-adhesive properties, directly addressing the growing clinical need for scarless wound healing and durable tissue scaffolds.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
The pandemic severely disrupted global supply chains for specialized fermentation media and bioreactor components, temporarily delaying clinical trials. Nevertheless, post-pandemic recovery has been aggressive, accelerated by heightened consumer awareness of health safety. This crisis underscored the fragility of animal-derived supply chains, permanently redirecting institutional investments toward resilient, locally fermentable recombinant bio-manufacturing.
Competitive Benchmarking and Strategic Dynamics
The landscape is characterized by high market concentration among pioneering Asian and Western biotech firms. Industry leaders such as Giant Biogene Holding Co. Ltd. and Jiangsu Jinbo Bio-Pharmaceutical Co. Ltd. dominate commercialized cosmetics, while Western players focus on high-margin medical devices, driving aggressive cross-border patent filings and strategic joint ventures.
Executive Summary: Navigating the Multi-Billion Dollar Biosynthetic Frontier
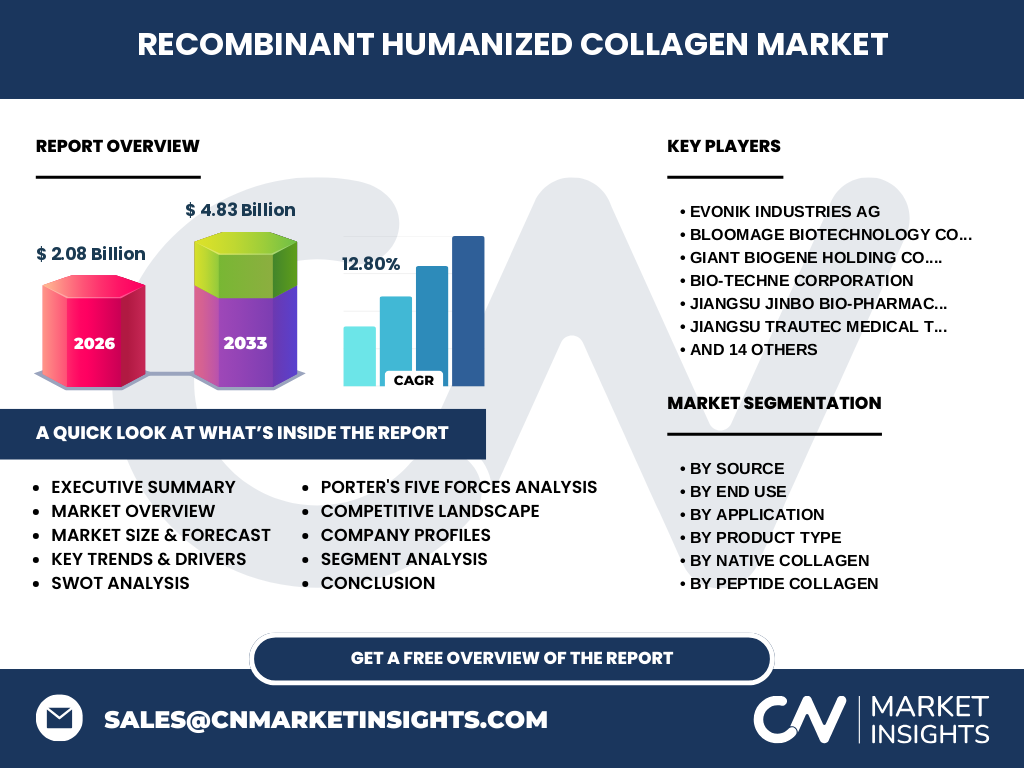
Our comprehensive research confirms that the Recombinant Humanized Collagen Market market size is poised for exponential expansion, scaling from $2.08 Billion in 2026 to $4.83 Billion by 2033 at a robust 12.80% CAGR. Stakeholders must prioritize scalable fermentation infrastructure and regulatory compliance to capture high-margin pharmaceutical and aesthetic segments.
Market Forecast Projections from 2027 to 2033
Based on our econometric modeling, the industry will achieve accelerated momentum during the 2027-2033 forecast period, culminating in a market valuation of $4.83 Billion by 2033. This trajectory is underpinned by a 12.80% CAGR, driven by mainstream adoption in functional nutraceuticals, injectable medical devices, and advanced tissue engineering scaffolds.
Segmentation Analysis Across Sources, End Uses, and Applications
The market segments by source into Bacterial, Yeast, Plant, and Mammalian Cell systems, with yeast dominating scalable output. End-use spans Pharmaceutical and Biotechnology Companies, alongside cosmetic giants. Applications diverge into medicine, cosmetics, and biomaterials, requiring specialized product types like hydrolyzed and cross-linked variants to match specific rheological and biocompatibility profiles.
Regional Market Analysis and Geographic Performance
Geographic performance exhibits distinct regulatory and consumer drivers across continents. Asia-Pacific leads commercial adoption, fueled by favorable regulatory frameworks in China for cosmetic collagen. Meanwhile, North America and Europe prioritize high-end pharmaceutical, clinical-grade injectable, and tissue engineering applications, supported by advanced venture capital funding ecosystems and stringent FDA oversight.
In-Depth Regional Review of Manufacturing Hubs and Regulatory Landscapes
China functions as the primary manufacturing epicenter, anchored by players like Jiangsu Trautec Medical Technology Co. Ltd. and Guangzhou Trauer Biotechnology Co. Ltd., benefiting from streamlined domestic NMPA approvals. Conversely, North American markets focus heavily on proprietary recombinant human collagen sequences for regenerative medicine, navigating complex FDA biologics license applications.
Strategic Positioning of Leading Industry Participants
Market leaders deploy distinct differentiation strategies. CollPlant Biotechnologies Ltd. leverages its proprietary plant-based rhCollagen platform for regenerative medicine, whereas Bloomage Biotechnology Corporation Limited utilizes massive fermentation capacity for commercial scale cosmetics. Specialty suppliers like ACROBiosystems Co. Ltd. target high-purity research reagents, cementing robust B2B positioning.
Porter's Five Forces Analysis of Competitive Pressures
Supplier power remains moderate due to specialized fermentation inputs, while buyer power is tempered by the strict purity demands of medical applications. Threat of new entrants is constrained by high capital expenditure for bioreactor scaling and complex downstream purification IP, though substitute animal collagens face mounting regulatory friction.
SWOT Analysis of the Recombinant Humanized Collagen Sector
Key strengths include absolute batch consistency and zero disease transmission risks. Weaknesses involve high initial capital expenditure. Opportunities abound in emerging nutraceutical delivery systems and injectable dermal fillers. Threats stem from potential reimbursement hurdles for advanced medical devices and intellectual property infringement in emerging markets.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with genetic sequence design and upstream microbial fermentation using carbon feedstocks. Midstream activities encompass advanced chromatography and ultrafiltration purification. Downstream value capture occurs via formulation into medical scaffolds or retail skincare by brands like Rixin Cosmetics Co. Ltd., ultimately reaching clinics and consumers.
Investment Insights and High-Potential Growth Pockets
Institutional investors should direct capital toward companies pioneering photo-cross-linked and scaffold-based native collagen for orthopedic and cardiovascular repair. High-margin biomedical applications offer superior insulation against commoditization compared to mass-market topical cosmetics, promising exceptional return on investment through 2033.
Conclusion and Strategic Takeaways for Industry Stakeholders
The transition to animal-free biomaterials is irreversible. Achieving a $4.83 Billion valuation by 2033 demands that market participants aggressively optimize fermentation yields and secure broad intellectual property portfolios. Companies failing to transition toward recombinant alternatives risk obsolescence amid tightening global safety regulations.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data from customs authorities, primary stakeholder interviews with C-suite biotech executives, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in tracking historical revenues and projecting the 12.80% CAGR through 2033.
Scope of the Report and Coverage Parameters
This report covers the global Recombinant Humanized Collagen Market industry trends across North America, Europe, Asia-Pacific, and RoW. Limitations include exclusion of traditional animal-derived collagen except where used as a comparative benchmark, focusing exclusively on bacterially, yeast, plant, and mammalian-expressed recombinant variants.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum highlights aggressive R&D commercialization. Firms like Geltor Inc. have expanded sustainable ingredient portfolios, while Evonik Industries AG and specialized biotech startups forge strategic distribution agreements to scale biomedical-grade supplies globally, reflecting rapid consolidation and technological maturation across the sector.