What is the market overview and industry significance of the Beer Brewing Centrifuge Market?
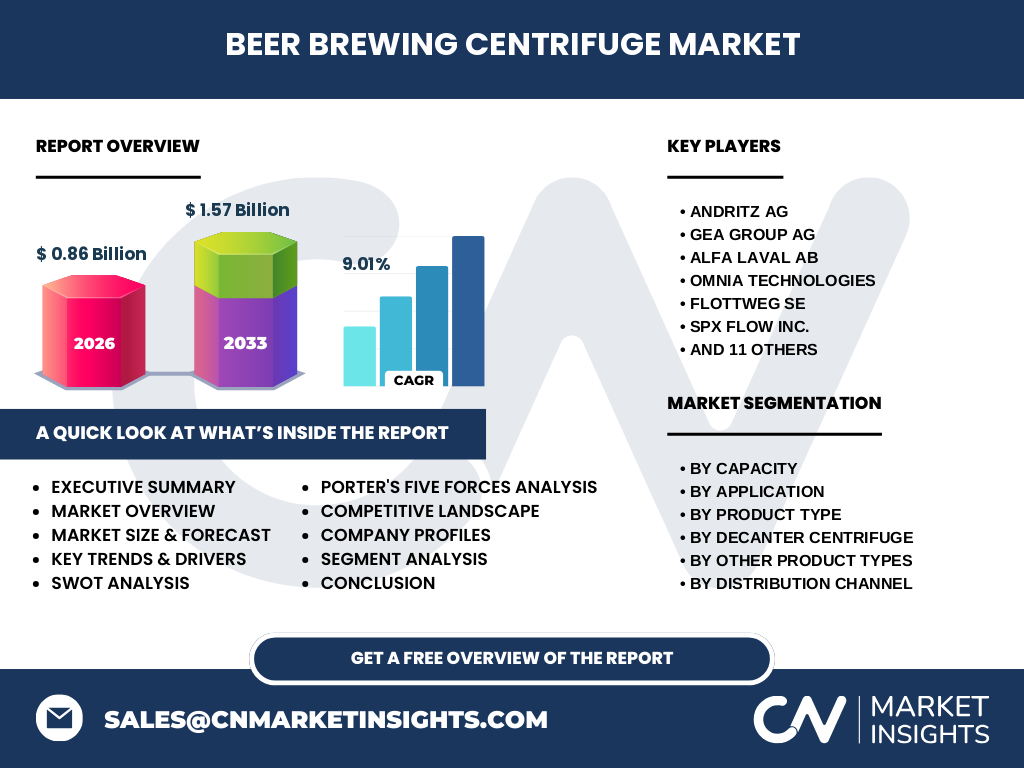
The Beer Brewing Centrifuge Market is valued at $0.86 Billion in 2026, serving as a cornerstone for modern high-efficiency breweries. These specialized separation systems utilize high-G-force rotational dynamics to clarify wort and green beer, drastically reducing yeast and trub loss compared to traditional settling tanks. By accelerating maturation cycles and improving overall liquid yield, centrifugation has become mission-critical for craft and industrial brewers alike navigating rising raw material costs.
Structural Growth Drivers and Market Restraints
Our analysis indicates that market expansion is heavily propelled by the global surge in craft brewing and the operational imperative for automated solid-liquid separation. High capital expenditure requirements for advanced disc stack units act as a notable restraint for smaller facilities, while strict sanitary regulatory compliances mandated by food safety authorities ensure that only high-performance, CIP-compatible engineering succeeds commercially.
Emerging trends and growth patterns in Beer Brewing Centrifuge Market
The industry is witnessing an accelerated shift toward continuous, automated processing modules that minimize oxygen pickup during yeast separation. Energy-efficient hermetic designs pioneered by market leaders are gaining rapid traction, as sustainability mandates and rising utility tariffs force facility managers to prioritize low-shear, low-power centrifugal units over conventional filtration aids like diatomaceous earth.
How did the pandemic impact the Beer Brewing Centrifuge Market and shape its recovery?
COVID-19 temporarily disrupted supply chains for specialized stainless steel alloys and delayed capital equipment upgrades across major brewing hubs in Europe and North America. However, the post-pandemic recovery trajectory has been robust, driven by a renewed industry focus on touchless, automated brewery operations that reduce labor dependency and maximize extract recovery in response to fluctuating consumer demand.
Competitive Benchmarking and Strategic Landscape
The competitive ecosystem is characterized by established heavyweights like GEA Group AG, Alfa Laval AB, and Andritz AG, who leverage extensive global distribution networks and patented hermetic sealing technologies. Market concentration remains moderately high, pushing mid-tier innovators to compete aggressively on specialized footprint configurations, lower lifecycle maintenance costs, and modular scalability tailored for regional brewing enterprises.
Executive Summary of the Beer Brewing Centrifuge Market
Our comprehensive research synthesis reveals a dynamic global marketplace poised for substantial expansion, underpinned by technological shifts toward closed-system clarification. Industry stakeholders are increasingly prioritizing equipment that guarantees zero oxygen ingress and minimal aroma stripping, ensuring that capital investments in centrifugation directly translate into superior product consistency and extended shelf life.
Market forecast and growth projections from 2027 to 2033
The data projects the Beer Brewing Centrifuge Market to reach $1.57 Billion by 2033, expanding at a robust CAGR of 9.01% from 2027 onward. This accelerated growth trajectory is fueled by widespread technological upgrades across emerging brewing markets in Asia-Pacific and Latin America, alongside continuous replacement cycles for aging, labor-intensive filtration systems in traditional European strongholds.
Segmentation Analysis: Capacity, Application, and Product Architecture
Market segmentation is structured around diverse operational scales and engineering typologies to address specific brewery throughput needs:
- By Capacity: Small Scale, Medium Scale, and Large Scale systems.
- By Application: Microbreweries, Brewpubs, Contract Brewing Companies, Regional Breweries, and Other Applications.
- By Product Type: Disc Stack Centrifuge, Decanter Centrifuge, Tubular Bowl Centrifuge, and Other Product Types.
Geographic distribution and regional performance dynamics
Regional performance varies significantly based on local beer consumption patterns, regulatory frameworks, and the concentration of industrial brewing facilities. Europe maintains a dominant baseline due to its mature brewing heritage, while the Asia-Pacific region represents the fastest-growing frontier, driven by rapid urbanization, expanding middle-class disposable incomes, and the proliferation of craft microbreweries in urban centers.
In-depth regional review of primary manufacturing and consumption hubs
In North America, strict environmental disposal regulations regarding spent filter aids have accelerated the adoption of closed-loop disc stack centrifuges. Meanwhile, European markets focus heavily on energy optimization and water conservation during Clean-in-Place (CIP) cycles, positioning premium German and Italian engineering firms at the forefront of sustainable brewery equipment design.
Strategic positioning of leading companies in the industry
Industry participants such as Flottweg SE, SPX FLOW Inc., and Pieralisi Maip S.p.A. differentiate themselves through proprietary bowl geometries and advanced automation interfaces. Companies like Trucent Inc. and US Centrifuge Systems focus on tailored integration services and fluid recovery optimization, ensuring high retention of valuable wort while minimizing solid waste disposal expenses for their clients.
Porter's Five Forces analysis of the competitive forces
The threat of new entrants remains constrained by high intellectual property barriers, precision manufacturing requirements, and established brand loyalty among major brewery conglomerates. Bargaining power of buyers is moderate to high, as large regional breweries leverage their purchasing volume, whereas supplier power over high-grade corrosion-resistant alloy components remains a critical cost-influencing variable.
SWOT analysis of the global separation equipment sector
Key strengths lie in high separation efficiency, reduced product loss, and automated sanitation capabilities. Weaknesses involve high initial capital outlays and complex maintenance protocols. Opportunities abound in emerging craft beer markets and sustainable water-saving retrofits, while threats stem from global macroeconomic volatility and fluctuating stainless steel raw material tariffs.
Value chain analysis from raw materials to final consumer deployment
The value chain initiates with specialized metallurgy and precision machining of high-grade stainless steel components. Equipment manufacturers then assemble advanced centrifugal bowls and drive systems, distributing them either through direct sales channels or specialized integrators. End-users deploy these systems post-fermentation to streamline clarification before packaging, directly impacting commercial yield and profitability.
Investment insights and high-potential strategic growth areas
Investors should target manufacturers specializing in compact, modular disc stack units designed specifically for the burgeoning microbrewery and contract brewing segments. Smart IoT-enabled predictive maintenance features represent a high-yield investment area, as brewers increasingly demand real-time telemetry to prevent unexpected downtime during peak production windows.
Conclusion and key takeaways for industry stakeholders
The Beer Brewing Centrifuge Market represents a high-growth, technology-driven sector essential for modern brewing efficiency. Stakeholders who embrace automated, energy-efficient, and low-shear centrifugal solutions will capture significant market share as global brewers continuously seek to optimize yield, reduce operating expenditure, and meet stringent sustainability benchmarks.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with master brewers and engineering directors, and secondary macroeconomic indicators. We cross-reference customs export statistics for industrial centrifuges with regional brewery licensing data to construct an accurate, verified market sizing model.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market dynamics for beer brewing centrifugation systems from 2026 to 2033, encompassing all major capacity tiers, product architectures, and distribution channels. Limitations include potential variance in localized import tariffs and unrecorded informal micro-brewery equipment installations in developing economies.
Recent developments, corporate partnerships, and strategic expansions
Recent industry moves highlight an aggressive push toward digital connectivity, with key players integrating AI-driven turbidity sensors into their latest centrifuge models. Strategic partnerships between equipment manufacturers and brewing conglomerates have focused on retrofitting legacy plants with energy-saving hermetic drives, underscoring the sector's commitment to sustainable, high-yield operational excellence.