What is the market overview and scope of the Sports Podiatry Clinic Market?
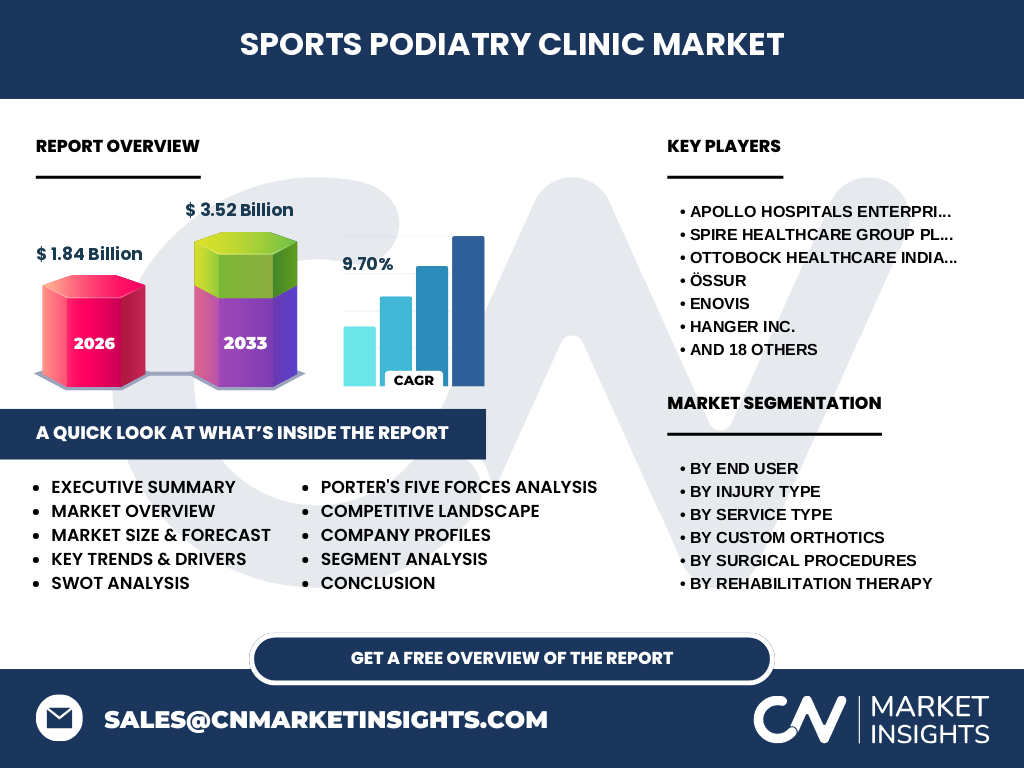
Our analysis indicates that the Sports Podiatry Clinic Market is valued at 1.84 Billion in 2026, delivering specialized clinical interventions for athletes, hospitals, and research institutes. The sector integrates advanced biomechanical assessments, custom orthotics, and surgical procedures regulated by bodies like the FDA to mitigate structural lower-limb pathologies.
What are the structural growth drivers and challenges shaping the Sports Podiatry Clinic Market industry trends?
The market is propelled by a surge in athletic participation and demand for customized injury prevention training. However, growth is restrained by high equipment costs for 3D printing and rigorous compliance mandates from health authorities. Regulatory hurdles for surgical innovations remain a key operational challenge for clinics.
What are the emerging trends and growth patterns in the Sports Podiatry Clinic Market analysis?
The shift toward Three Dimensional Printed Orthotic Services and digital gait analysis is transforming patient care. Leading players like Össur and Bauerfeind AG are pioneering sport-specific orthotic designs, which significantly enhance recovery efficiency and drive higher patient retention across elite sports facilities.
How did the COVID-19 pandemic impact the Sports Podiatry Clinic Market and recovery trajectory?
Pandemic-related lockdowns initially suppressed elective biomechanical assessments and non-urgent surgical procedures. The market recovered robustly as clinics adopted telehealth triage and accelerated investments in digital rehabilitation therapy, stabilizing supply chains for essential raw materials used in molded custom foot orthotics.
What does the competitive landscape look like in the Sports Podiatry Clinic Market?
Market concentration is moderate, featuring a mix of sprawling healthcare networks like Apollo Hospitals and specialized entities such as ProLab Orthotics. Strategic dynamics focus on technological integration, with providers acquiring advanced pressure mapping systems to capture higher-margin sports injury treatment segments.
Executive Summary of the Sports Podiatry Clinic Market
Our research projects the Sports Podiatry Clinic Market to expand from 1.84 Billion in 2026 to 3.52 Billion by 2033, achieving a robust 9.70% CAGR. This expansion is anchored by rising demand for preventive foot care and specialized rehabilitation services globally.
What is the market forecast for the Sports Podiatry Clinic Market from 2027 to 2033?
Driven by accelerating adoption of custom orthotics and minimally invasive foot surgery, the sector will scale rapidly to 3.52 Billion by 2033 at a 9.70% CAGR. Investment in post-injury recovery programs will be the primary catalyst during this forecast horizon.
Segmentation Analysis of the Sports Podiatry Clinic Market
The market segments by end-user into athletes, coaches, physiotherapists, hospitals, and research institutes. Injury types span foot, ankle, heel pain, and tendon issues. Service types range from surgical procedures to preventive foot care, while custom orthotics feature 3D-printed and sport-specific designs.
Regional market analysis and geographic distribution
North America and Europe dominate the geographic distribution due to advanced healthcare infrastructure and high sports participation rates. Meanwhile, the Asia-Pacific region exhibits the fastest growth, propelled by expanding medical tourism and rising investments by market participants in India and Southeast Asia.
In-depth regional review of key markets
Localized constraints in Western markets involve stringent reimbursement policies for custom orthotics, whereas emerging Asian hubs benefit from lower operational costs. Regional networks like Aster Hospitals and Yashoda Healthcare are rapidly expanding their sports medicine divisions to capture localized demand.
Company profiles and strategic positioning in the Sports Podiatry Clinic Market
Key players including Spire Healthcare Group Plc, Enovis, and Hanger Inc. leverage vertical integration and proprietary orthotic technologies. Companies like Aspetar focus on elite athlete rehabilitation, while retail-oriented chains like Foot Solutions target broader preventive foot care demographics.
Porter's Five Forces analysis of the industry
Rivalry is intense among established clinic networks, while supplier power remains moderate due to specialized orthotic materials. Threat of substitutes is low given the clinical precision required for sports injury treatment, though high capital requirements create a formidable barrier to new market entrants.
SWOT analysis of the Sports Podiatry Clinic Market
Strengths include advanced diagnostic accuracy and proprietary 3D printing capabilities. Weaknesses stem from high initial device costs. Opportunities lie in expanding performance enhancement programs, while threats involve regulatory delays and potential economic downturns impacting discretionary preventive care spending.
Value chain analysis from raw materials to end-users
The value chain flows from raw material suppliers providing thermoplastic resins and carbon fiber, through manufacturers creating orthotic shells, to clinical practitioners delivering services. End-users ranging from amateur athletes to professional teams capture the ultimate utility through enhanced recovery metrics.
Investment insights and strategic recommendations
High-potential areas include Three Dimensional Printed Orthotic Services and advanced gait analysis platforms. Investors should prioritize clinics integrating multidisciplinary rehabilitation therapy with cutting-edge surgical services to maximize margins in high-growth urban centers.
Conclusion and key takeaways for stakeholders
The Sports Podiatry Clinic Market represents a high-growth frontier reaching 3.52 Billion by 2033. Stakeholders must embrace digital transformation, 3D printing technology, and strategic partnerships with athletic organizations to maintain a competitive edge in this rapidly evolving sector.
Research methodology used for baseline estimates
Baseline estimates are triangulated by combining trade registry data, primary stakeholder interviews with clinical directors, and secondary macroeconomic indicators from global health organizations. This multi-layered approach ensures high fidelity in market sizing and growth projections.
Scope of the report and coverage parameters
This report covers global revenue projections from 2026 to 2033, segmenting the market by end-user, injury type, service type, and technological application. Limitations include restricted data transparency in private clinic networks across emerging economies.
Recent developments, company announcements, and strategic moves
Recent industry momentum features strategic acquisitions and product launches by firms like Ottobock Healthcare and StrideCare Inc. Partnerships between specialized clinics and tech innovators are accelerating the deployment of AI-driven pressure mapping and automated custom orthotic manufacturing lines.