Market overview of the Artificial Intelligence (AI)-Based Workflow Automation In Hospitals Market
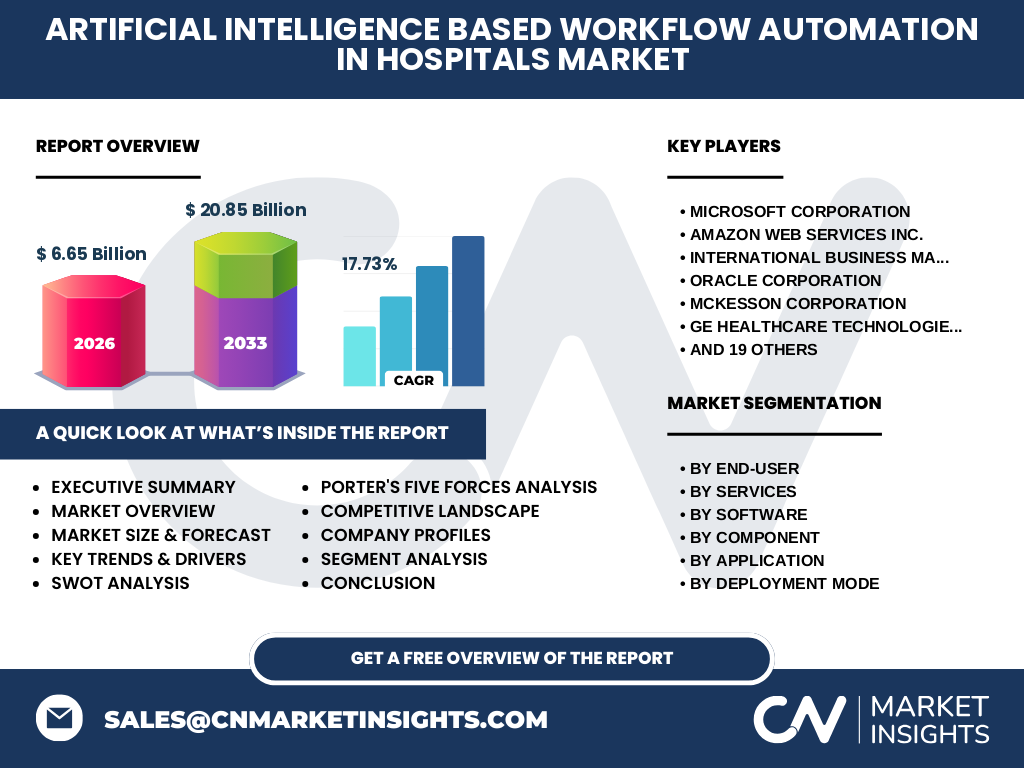
Our analysis indicates that the Artificial Intelligence (AI)-Based Workflow Automation In Hospitals Market stands at 6.65 Billion in 2026, driven by the urgent need to streamline clinical and administrative operations. Regulatory bodies like the FDA and HIPAA compliance frameworks heavily influence deployment parameters across acute care facilities worldwide.
Structural Growth Drivers and Restraints
The data suggests that skyrocketing clinician burnout and rising administrative overhead act as core catalysts. Conversely, severe data privacy regulations and legacy IT infrastructure incompatibility restrain rapid adoption. Vendors such as Epic Systems Corporation and Cerner actively navigate these hurdles through EHR-native AI integrations.
Emerging trends and growth patterns in Artificial Intelligence (AI)-Based Workflow Automation In Hospitals Market
The shift toward generative AI for clinical documentation and automated patient triage is dominating the Artificial Intelligence (AI)-Based Workflow Automation In Hospitals Market industry trends. Hospitals increasingly demand cloud-native solutions that bypass on-premises hardware constraints, favoring scalable vendor ecosystems.
COVID-19 impact analysis and recovery trajectory
The pandemic exposed severe hospital resource bottlenecks, permanently accelerating digital health investments. Post-pandemic recovery trajectories prioritize automated bed management and predictive capacity planning. Market participants like Microsoft Corporation and Amazon Web Services Inc. capitalized on this by deploying scalable cloud infrastructure for remote patient monitoring.
Competitive benchmarking and strategic dynamics
Competitive intensity is high, with tech giants and specialized health-IT vendors vying for dominance. GE HealthCare Technologies Inc., Siemens Healthineers AG, and NVIDIA Corporation leverage proprietary hardware-software synergies, while pure-play automation leaders like UiPath Inc. focus on robotic process automation for revenue cycle management.
Executive summary of the Artificial Intelligence (AI)-Based Workflow Automation In Hospitals Market
Our research underscores a massive market expansion, projecting the Artificial Intelligence (AI)-Based Workflow Automation In Hospitals Market to reach 20.85 Billion by 2033. Achieving a robust CAGR of 17.73% from 2027 to 2033, the sector represents a critical frontier for healthcare digital transformation.
Market forecast from 2027 to 2033
Based on our predictive models, the Artificial Intelligence (AI)-Based Workflow Automation In Hospitals Market market size will scale dramatically from its 2026 baseline of 6.65 Billion to hit 20.85 Billion by 2033. This growth trajectory reflects a sustained 17.73% CAGR driven by acute care digitization.
Segmentation analysis by end-user, services, software, component, application, and deployment
The market breaks down by end-user into Public Hospitals, Private Hospitals, and Specialty Hospitals. Software categories feature Workflow Management Software and Clinical Decision Support Software. Services include Consulting Services, Implementation And Integration Services, and Training And Education Services, spanning On-Premises and Cloud deployments.
Regional market analysis and geographic distribution
Geographic performance is heavily skewed toward North America due to early EHR adoption and favorable venture capital funding. Meanwhile, Asia-Pacific exhibits rapid growth spurred by government-backed digital hospital initiatives. Localized reimbursement policies and strict data sovereignty laws across the EU shape European deployment speeds.
In-depth regional review of key markets
North America dominates revenue generation, anchored by advanced health systems integrating platforms from Oracle Corporation and Change Healthcare. European markets prioritize strict GDPR compliance, favoring federated learning approaches. Asia-Pacific demonstrates high-volume adoption in metropolitan public networks managed by regional health ministries.
Company profiles and strategic positioning
Industry leaders maintain distinct strategic positioning. International Business Machines Corporation (IBM) and Nuance Communications focus on cognitive computing and ambient clinical intelligence. Meanwhile, Salesforce Inc. and ServiceNow Inc. optimize patient journey management and enterprise service workflows for large health networks.
Porter's Five Forces analysis of the sector
Bargaining power of buyers is moderate to high as hospitals demand interoperable, cost-effective solutions. Threat of new entrants remains constrained by high regulatory barriers, FDA clearance timelines, and proprietary health data access requirements needed to train robust clinical automation models.
SWOT analysis of the industry landscape
Strengths include dramatic reductions in clinician burnout and administrative error rates. Weaknesses involve high initial integration costs and legacy system friction. Opportunities lie in predictive analytics expansion, while threats center on cybersecurity vulnerabilities and evolving medical liability regulations regarding automated decisions.
Value chain analysis from raw materials to end-users
The value chain initiates with raw computational silicon and healthcare datasets, flowing through cloud providers like Amazon Web Services Inc. and Microsoft Corporation. Specialized vendors build clinical algorithms before system integrators like Cognizant Technology Solutions Corporation and Wipro Limited deploy them inside hospital workflows.
Investment insights and high-potential areas
Investors should target cloud-native workflow orchestration tools and specialized clinical decision support systems. Companies partnering with major EHR vendors like Epic Systems Corporation or Athenahealth Inc. exhibit superior scalability and reduced customer acquisition friction within target hospital segments.
Conclusion and key takeaways
The Artificial Intelligence (AI)-Based Workflow Automation In Hospitals Market analysis confirms that automated healthcare workflows are no longer optional. Reaching 20.85 Billion by 2033 at a 17.73% CAGR, early adopters leveraging solutions from GE HealthCare Technologies Inc. and Siemens Healthineers AG will secure lasting operational efficiencies.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining health ministry trade registry data, primary stakeholder interviews with hospital Chief Information Officers (CIOs), and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of the 6.65 Billion 2026 baseline and the subsequent forecast.
Scope of the report and coverage parameters
This report covers global deployment trends across public, private, and specialty hospitals. It evaluates software, service components, and deployment modes from 2026 through 2033. Excluded from this scope are outpatient ambulatory surgical centers and veterinary medical workflow automation platforms.
Recent developments in corporate strategies and partnerships
Recent market activity highlights aggressive strategic partnerships between tech giants and health systems. NVIDIA Corporation continues launching healthcare-specific microservices, while Infor Healthcare and Voluntis announce collaborative clinical workflow integrations aimed at reducing administrative burdens in emergency departments.