Market Overview of the On-Demand Jet Charter Market
Our analysis indicates the On-Demand Jet Charter Market size stands at $47.93 Billion in 2026, capturing the economic significance of non-scheduled aviation services. Regulatory frameworks governed by the FAA and EASA dictate operational clearances for key operators navigating complex airspace constraints across global transport hubs.
Key Market Drivers, Restraints, Challenges, and Opportunities
Growth is propelled by surging corporate demand for time-sensitive routing bypassing congested commercial hubs like Teterboro and London Luton. Operational headwinds include volatile jet fuel pricing, titanium alloy supply chain bottlenecks for aircraft maintenance, and stringent carbon-offset mandates enforced by international regulatory bodies.
Emerging Trends and Growth Patterns in the On-Demand Jet Charter Market
The shift toward digital brokerage apps has revolutionized client booking workflows. Industry innovators like Magellan Jets LLC and Stratos Jet Charters Inc. leverage proprietary software integrations to streamline fleet allocation, driving heightened aircraft utilization rates across light and mid-size jet categories.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic forced a structural reset, accelerating adoption as high-net-worth individuals and corporate executives sought bio-secure travel alternatives. Operators adapted through rigorous cabin sanitization protocols and contactless boarding, paving the way for sustained post-pandemic volume expansion across primary business aviation corridors.
Competitive Landscape and Strategic Dynamics
Market concentration features a mix of massive fractional fleet operators and localized boutique brokers. Industry leaders like NetJets and Vista Global Holding Limited dominate through expansive global footprints, while regional players like GlobeAir AG capture niche European short-haul intra-city routes.
Executive Summary of the On-Demand Jet Charter Industry
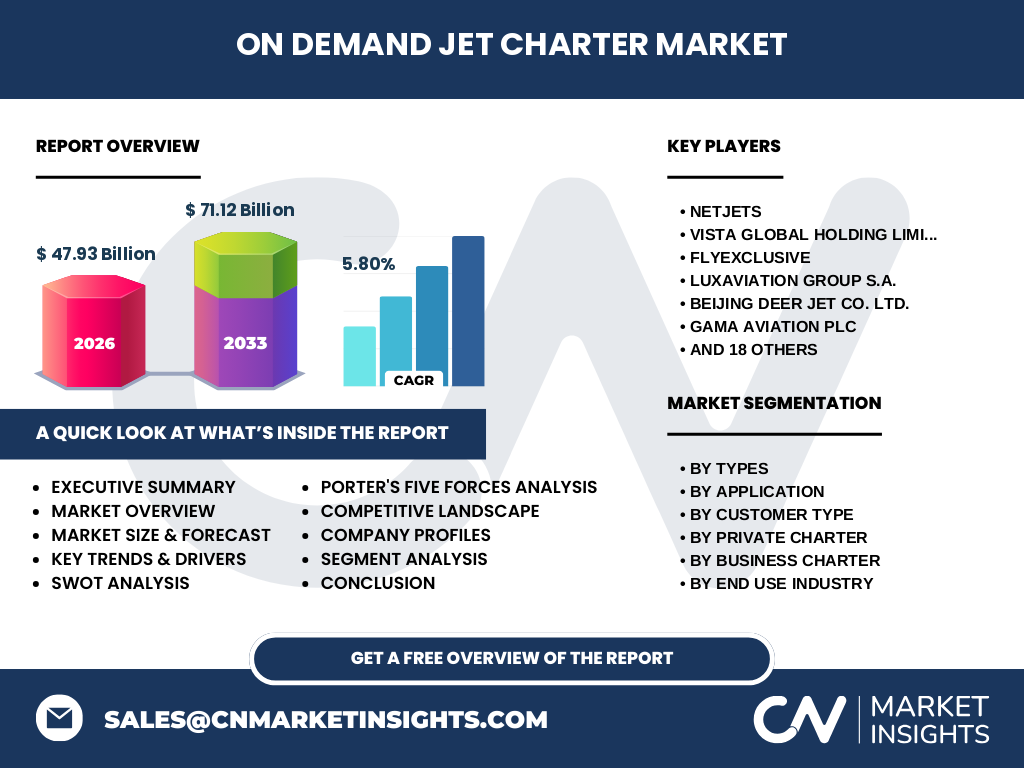
The On-Demand Jet Charter Market industry trends point to robust expansion, scaling from $47.93 Billion in 2026 to $71.12 Billion by 2033 at a 5.80% CAGR. Strategic agility in fleet management and digital integration remain critical differentiators for sustained profitability.
Market Forecast from 2027 to 2033
Based on our research, the market will expand steadily at a 5.80% CAGR, propelling valuations from $47.93 Billion in 2026 to $71.12 Billion by 2033. This trajectory is underwritten by escalating corporate travel budgets and rising wealth accumulation in emerging economic zones.
Segmentation Analysis Across Categories
Segmentation breaks down by Types into Private Charter and Business Charter; Applications into Passenger and Cargo; and Customer Types spanning Corporate Travelers, High Net Worth Individuals, and Government And Defense Clients. End-use industries range from healthcare to energy and mining sectors.
Regional Market Analysis and Geographic Distribution
North America commands the largest market share due to mature corporate infrastructure and dense FBO networks. Meanwhile, the Asia-Pacific region demonstrates the fastest growth velocity, supported by rising infrastructure investments in mainland China and India's expanding private aviation hubs.
In-Depth Regional Review
European markets face stringent environmental taxation, pushing operators toward sustainable aviation fuels (SAF). In contrast, North American operations benefit from streamlined FAA air traffic management and extensive regional airport access, favoring agile operators like Solairus Aviation LLC and Clay Lacy Aviation Inc.
Company Profiles and Strategic Positioning
Major ecosystem participants include flyExclusive, Luxaviation Group S.A., and Beijing Deer Jet Co. Ltd., each deploying distinct fleet acquisition and membership strategies. Firms like Gama Aviation Plc and TAG Aviation Holdings S.A. focus heavily on aircraft management and maintenance engineering excellence.
Porter's Five Forces Analysis of Competitive Pressures
Competitive rivalry is intense among mid-tier brokers, while buyer power remains moderate to high due to transparent digital price comparison tools. Supplier power is constrained by duopolistic aircraft manufacturing bottlenecks involving Gulfstream, Bombardier, and Dassault aviation assembly lines.
SWOT Analysis of the On-Demand Jet Charter Sector
Strengths include unmatched schedule flexibility and time efficiency. Weaknesses involve high fixed operational overhead. Opportunities lie in expanding medical emergency and organ transport flights, while threats center on intensifying carbon tax regulations and potential macroeconomic recessions curbing discretionary spending.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw aerospace composite and avionics manufacturing to OEMs, aircraft management firms, and charter brokers. Downstream delivery involves FBO ground handling, catering logistics, and fuel suppliers culminating in the end-user corporate or private passenger experience.
Investment Insights and High-Potential Areas
High-potential investment zones center on digital trip-support platforms, electric vertical takeoff and landing (eVTOL) integration, and SAF supply partnerships. Institutional investors should target asset-light brokerages scaling proprietary booking infrastructure to capture high-margin corporate accounts.
Conclusion and Key Takeaways
The data confirms that the On-Demand Jet Charter Market analysis reflects a resilient sector poised to reach $71.12 Billion by 2033. Operators that successfully balance technological innovation with regulatory compliance will capture disproportionate market share.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining civil aviation registry data, primary stakeholder interviews with C-suite executives at firms like DC Aviation GmbH and Líder Táxi Aéreo S/A, and secondary macroeconomic indicators tracking global wealth indices.
Scope of the Report and Coverage Parameters
This report covers global on-demand charter operations across commercial, corporate, and private aviation domains. Limitations exclude scheduled commercial airline networks and fractional ownership models that operate outside pure on-demand spot-charter parameters.
Recent Developments and Strategic Industry Moves
Recent market activities highlight aggressive fleet expansion and strategic cross-border partnerships. Industry participants such as GlobeAir AG and Club One Air Pvt. Ltd. have formed alliances to extend regional service capabilities, addressing surging post-pandemic demand for point-to-point executive mobility.