What is the scope and industry significance of the Reusable Medical Sensors Market?
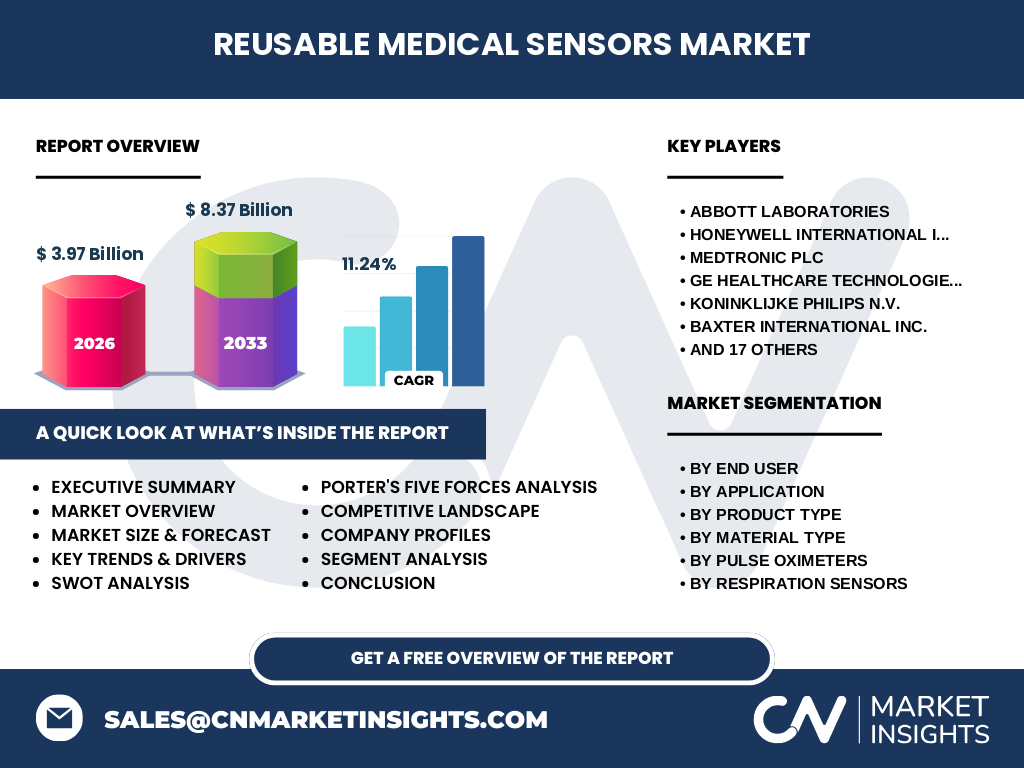
Our analysis indicates that the Reusable Medical Sensors Market reaches a valuation of 3.97 Billion in 2026. This sector encompasses durable diagnostic and monitoring instruments deployed across clinical and decentralized environments, fundamentally reducing medical waste compared to single-use alternatives while demanding rigorous sterilization protocols compliant with FDA and EMA standards.
Structural Growth Drivers and Restraints in the Reusable Medical Sensors Market
Growth is heavily propelled by rising chronic disease burdens and cost-containment pressures in acute care facilities. Conversely, the market faces notable restraints from strict regulatory validation processes governed by bodies like the FDA, alongside logistical bottlenecks in managing high-temperature autoclaving and chemical sterilization for silicone-based and hybrid sensors.
Emerging trends and growth patterns in the Reusable Medical Sensors Market industry trends
The sector is witnessing a decisive pivot toward miniaturized, wireless patient monitoring and advanced continuous blood glucose tracking. Innovators are increasingly utilizing hybrid material sensors that combine biocompatible polymers with conductive silicon, improving patient comfort during extended wear while maintaining signal fidelity across ECG and respiration applications.
How did the COVID-19 pandemic affect the Reusable Medical Sensors Market market size and recovery?
The pandemic initially fractured global supply chains—particularly for electronic components routed through major Asian maritime ports—while driving unprecedented demand for pulse oximeters and bedside monitoring hardware. The post-pandemic recovery reflects a stabilized manufacturing cadence, with institutional buyers prioritizing robust, easily sterilizable hardware to insulate against future supply shocks.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, anchored by multinational conglomerates like Medtronic plc, GE HealthCare Technologies Inc., and Koninklijke Philips N.V. These industry leaders leverage expansive distribution channels and proprietary sensor algorithms, while agile specialists like Masimo Corporation and Nonin Medical Inc. compete via specialized pulse oximetry innovations and high-precision optical technology.
Executive summary of key findings for the Reusable Medical Sensors Market analysis
Driven by an anticipated expansion to 8.37 Billion by 2033 at a robust CAGR of 11.24% from 2027, the market represents a high-growth frontier. Strategic investments in wireless ECG and home health telemetry are critical as healthcare delivery decentralizes away from traditional hospital settings.
Market forecast trajectory from 2027 to 2033
Our forecasting models show the Reusable Medical Sensors Market expanding from 2027 through 2033 at a steady 11.24% CAGR, culminating in a market valuation of 8.37 Billion by the end of the forecast period. This trajectory is fueled by surging adoption in ambulatory surgical centers and home health care settings.
Comprehensive segmentation analysis of the Reusable Medical Sensors Market
Segmentation spans end users, applications, product types, material types, and distribution channels. Key product vectors include electrocardiogram sensors, pulse oximeters, and blood glucose monitors. Material classifications—specifically silicone, plastic, and hybrid variants—dictate durability, patient comfort, and compatibility with specific hospital sterilization protocols.
Regional market analysis and geographic distribution
Geographic performance is led by North America, supported by sophisticated hospital infrastructure and high reimbursement rates for remote patient monitoring. Meanwhile, Asia-Pacific represents the fastest-growing frontier, propelled by expanding healthcare access in urban centers and rising manufacturing investments by local firms in China and India.
In-depth regional review of high-potential territories
North America dominates revenue generation due to early adoption of smart blood glucose monitors and wearable health devices. Concurrently, European markets exhibit strict regulatory oversight via the European Medicines Agency, favoring established domestic manufacturers like Drägerwerk AG & Co KGaA and SCHILLER AG that meet rigorous MDR compliance standards.
Company profiles and strategic positioning of leading participants
Market leaders such as Abbott Laboratories and Dexcom Inc. anchor the continuous glucose monitoring space, while Shenzhen Mindray Bio-Medical Electronics Co. Ltd. and Nihon Kohden Corporation drive competitive pressure through cost-effective, high-reliability patient monitoring solutions tailored for emerging clinical markets and emergency care environments.
Porter's Five Forces analysis of the Reusable Medical Sensors Market
Bargaining power of buyers is moderate to high due to consolidated group purchasing organizations in hospital networks. Supplier power remains constrained by the abundance of raw polymer and silicone providers, whereas threat of substitution is mitigated by the clinical precision required in professional ECG and continuous telemetry.
SWOT analysis of the Reusable Medical Sensors Market
Strengths lie in durability and long-term cost efficiency for healthcare institutions. Weaknesses involve strict cleaning validation requirements. Opportunities abound in telehealth expansion and emerging economies, while threats stem from aggressive pricing pressures by low-cost single-use sensor manufacturers and stringent regulatory hurdles.
Value chain analysis from raw materials to end-users
The value chain initiates with specialty chemical and silicone raw material synthesis, progressing to precision component fabrication by specialized manufacturers. Finished sensors flow through direct sales, specialized distributors, and online channels before reaching hospitals, research laboratories, and individual consumers at-home.
Investment insights and strategic high-potential areas
Capital deployment should target wireless ECG sensors, wearable temperature patches, and advanced hybrid material integration. Investors should prioritize firms demonstrating strong compliance frameworks capable of navigating FDA 510(k) clearances and international medical device regulations efficiently.
Conclusion and key takeaways for stakeholders
The Reusable Medical Sensors Market offers compelling growth, backed by an impressive expansion to 8.37 Billion by 2033. Stakeholders must align product roadmaps with wireless connectivity and biocompatible hybrid materials to capture expanding market share across both clinical and home care verticals.
Research methodology behind our market sizing and forecasts
Our baseline estimates are rigorously triangulated by combining international trade registry data, primary stakeholder interviews with C-level executives in medical device firms, and secondary macroeconomic indicators, ensuring high data integrity and robust predictive accuracy for the Reusable Medical Sensors Market.
Scope of the report and analytical limitations
This report covers global revenue performance, segmentation vectors, and competitive dynamics from 2026 to 2033. Limitations include unforeseen macroeconomic shifts, localized geopolitical trade disruptions, and sudden regulatory policy updates from bodies such as the US FDA and European Commission.
Recent developments, product launches, and strategic partnerships
Recent industry momentum highlights strategic acquisitions and product clearances aimed at wireless integration. Companies like Infinium Medical Inc. and Edan Instruments Inc. have advanced modular patient monitors, while major players form joint distribution agreements to expand their footprint in high-growth ambulatory care networks.