What is the market overview of the Clinical Genomics Software Market?
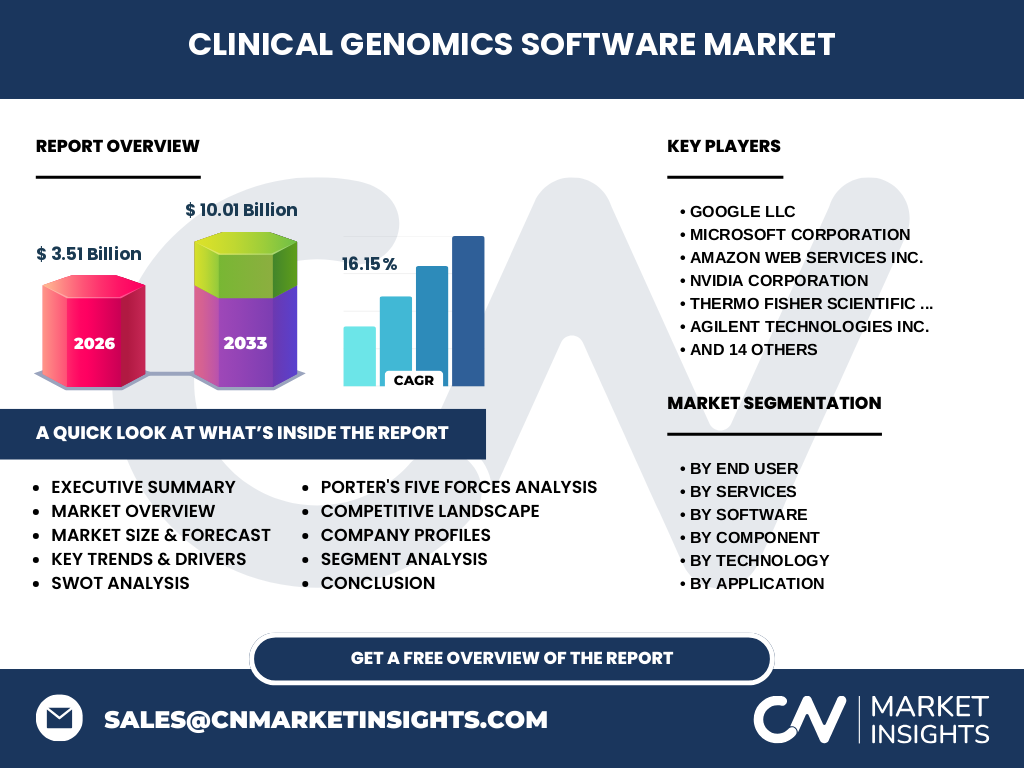
Our analysis indicates that the Clinical Genomics Software Market encompasses specialized informatics solutions designed to process, analyze, and interpret complex sequencing data for patient diagnosis. Valued at 3.51 Billion in 2026, this industry is foundational for translating raw genomic reads into actionable clinical insights across oncology and rare disease diagnostics.
Structural Growth Drivers and Restraints
Based on our research, the Clinical Genomics Software Market industry trends are heavily propelled by declining sequencing costs and the integration of Artificial Intelligence And Machine Learning Based Genomics. However, stringent compliance demands from regulatory bodies like the FDA regarding Software as a Medical Device (SaMD) act as notable adoption hurdles for smaller diagnostic laboratories.
Emerging Trends in Genomic Informatics
The data suggests a massive industry pivot toward multi-omics integration and cloud-native architectures. Innovators like Amazon Web Services Inc. and Google LLC are dominating this space by enabling scalable storage for massive Whole Genome Sequencing datasets, directly empowering platforms such as SOPHiA GENETICS SA to deliver decentralized variant interpretation.
How did the COVID-19 pandemic reshape the Clinical Genomics Software Market?
The pandemic drastically accelerated pathogen surveillance via Ribonucleic Acid Sequencing, permanently embedding bioinformatics pipelines into public health infrastructure. Our analysis shows that this operational stress test catalyzed a rapid post-pandemic recovery, driving robust investments into Cloud Based Genomics Analytics Software to support remote variant interpretation engines.
Competitive Benchmarking and Industry Concentration
The Clinical Genomics Software Market analysis reveals a dynamic landscape characterized by both tech conglomerates and specialized biotech leaders. Giants like NVIDIA Corporation provide the necessary GPU acceleration for deep learning pipelines, while specialists such as Tempus Labs Inc. and Caris Life Sciences Inc. leverage proprietary clinical-genomic databases to dominate oncology-focused software deployment.
Executive Summary
Our comprehensive findings project the Clinical Genomics Software Market to surge from 3.51 Billion in 2026 to 10.01 Billion by 2033, exhibiting a robust CAGR of 16.15%. This exponential expansion underscores the critical transition toward personalized medicine, heavily supported by advancements in Next Generation Sequencing and Clinical Decision Support Software.
Market Forecast and Long-Term Trajectory
Driven by widespread clinical adoption across hospitals and diagnostic laboratories, the forecast period from 2027 to 2033 anticipates a total market value reaching 10.01 Billion. This trajectory reflects a phenomenal 16.15% CAGR, highlighting unprecedented commercial opportunities for software vendors providing scalable bioinformatics workflow management.
Segmentation Analysis of the Clinical Genomics Software Market
Our market research segments the industry across End Users, Services, Software, Component, Technology, Application, and Deployment Model. Key sectors include Hospitals And Clinics and Diagnostic Laboratories utilizing Genomic Data Analysis Software, alongside diverse deployment strategies ranging from On Premises to Cloud Based infrastructures.
Geographic Distribution and Regional Market Performance
Geographically, the Clinical Genomics Software Market demonstrates concentrated growth in regions with advanced healthcare reimbursement frameworks and stringent data privacy laws. North America leads the adoption curve, followed closely by Europe, where localized bioethics frameworks heavily influence the deployment of cloud hosting services and genomic data visualization tools.
In-Depth Regional Review
The North American market commands the largest share, fueled by high concentrations of biotechnology firms and early adoption of Whole Exome Sequencing in clinical workflows. Meanwhile, Asia-Pacific is emerging as the fastest-growing region, driven by massive government-backed population genomics initiatives in countries like China and Singapore, benefiting regional players like BGI Genomics Co. Ltd.
Strategic Positioning of Leading Companies
Industry leaders like Illumina Inc. and Thermo Fisher Scientific Inc. maintain strong footholds by bundling proprietary sequencing hardware with native bioinformatics pipelines. Concurrently, agile software innovators such as Golden Helix Inc. and Genomenon Inc. focus on specialized variant interpretation engines, securing critical niches within clinical diagnostic workflows.
Porter's Five Forces Analysis
Our analysis indicates moderate-to-high competitive rivalry within the Clinical Genomics Software Market, driven by continuous algorithmic advancements from firms like Pacific Biosciences of California Inc. and Oxford Nanopore Technologies plc. Buyer power remains significant among large hospital networks, whereas the threat of substitution is mitigated by proprietary clinical validation data.
SWOT Analysis of the Industry
Strengths include high diagnostic precision and massive scalability via cloud infrastructure; weaknesses involve complex regulatory validation protocols. Opportunities lie in untapped emerging markets for rare disease diagnostics, while threats center on escalating cybersecurity vulnerabilities surrounding sensitive genomic data managed by providers like Guardant Health Inc.
Value Chain Analysis from Raw Data to End-Users
The value chain flows from raw sequencing raw materials and hardware supplied by pioneers like Bio-Rad Laboratories Inc. through to cloud infrastructure providers and downstream bioinformatics developers. Ultimate value is captured by clinical end-users utilizing Clinical Decision Support Software for targeted oncology treatments.
Investment Insights and High-Potential Areas
Investors should prioritize software developers specializing in multi-omics data integration and real-time variant interpretation. Companies leveraging artificial intelligence to reduce secondary analysis bottlenecks represent prime acquisition targets, particularly as diagnostic labs demand turnkey solutions from vendors like Benchling Inc. and QIAGEN N.V.
Conclusion and Key Takeaways
The Clinical Genomics Software Market is on an explosive trajectory, scaling to 10.01 Billion by 2033 at a 16.15% CAGR. Stakeholders must align their product roadmaps with cloud scalability, rigorous regulatory compliance, and advanced AI-driven variant interpretation to capture sustainable market share.
Research Methodology
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with C-level executives, secondary trade registry data, and macroeconomic healthcare expenditure indicators. This multi-layered approach ensures precise sizing of the Clinical Genomics Software Market across all evaluated segments and regions.
Scope of the Report and Limitations
This report evaluates the global Clinical Genomics Software Market from 2026 to 2033, covering detailed segmentations by software type, service model, technology, and regional deployment. Limitations include unpredictable regulatory shifts in localized health jurisdictions and varying public healthcare budgetary allocations across developing economies.
Recent Developments and Strategic Moves
Recent industry momentum is defined by strategic partnerships between cloud giants and diagnostic leaders, such as Veracyte Inc. integrating advanced machine learning workflows. Furthermore, platform enhancements by companies like Microsoft Corporation and NVIDIA Corporation continue to redefine real-time genomic data processing capabilities across global health networks.