What is the market overview and scope of the Dermatosurgical Devices Market?
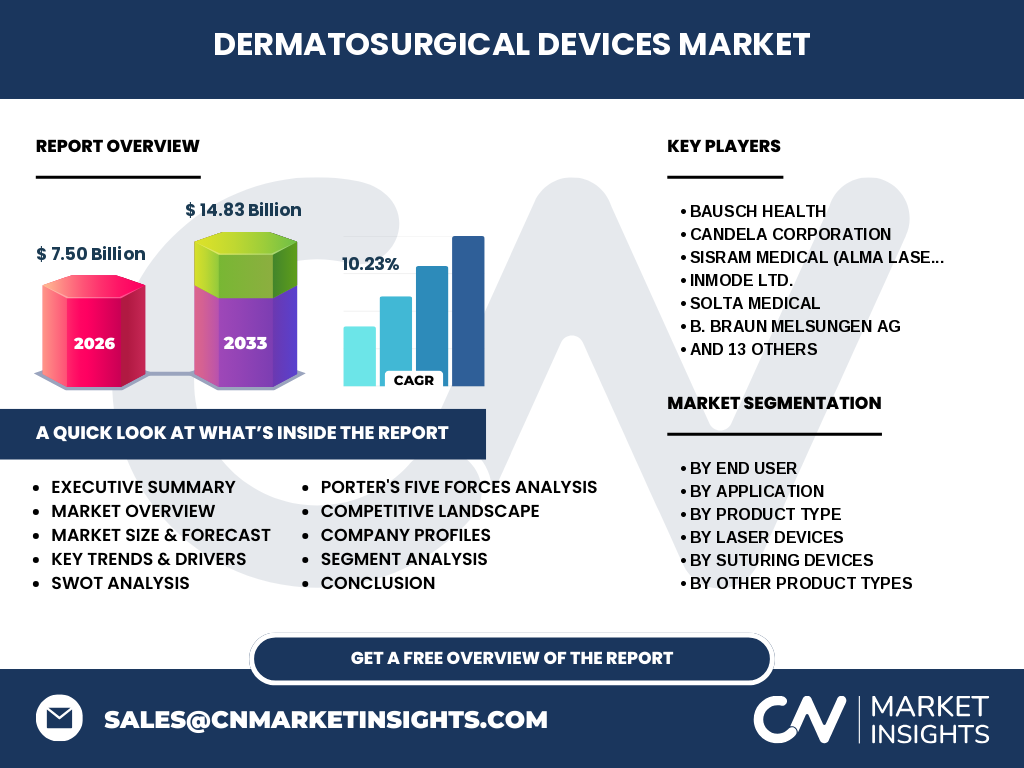
Our analysis indicates that the Dermatosurgical Devices Market valued at $7.50 Billion in 2026 encompasses specialized tools and equipment utilized in therapeutic and cosmetic skin procedures. This sector covers advanced laser systems, electrosurgical units, and precision suturing tools deployed globally by practitioners navigating stringent medical device regulations enforced by bodies like the FDA and EMA.
What are the core drivers, restraints, challenges, and opportunities shaping the Dermatosurgical Devices Market?
Growth in the Dermatosurgical Devices Market industry trends is propelled by rising demand for minimally invasive cosmetic interventions and advanced skin cancer treatments. However, stringent reimbursement policies and high capital costs for laser equipment act as major restraints. Opportunities thrive in emerging economies where rising disposable incomes expand patient access to dermatology clinics.
Emerging trends and growth patterns in the Dermatosurgical Devices Market
The shift toward multi-platform energy-based systems is redefining clinical workflows. Innovations in fractional and non-ablative laser devices allow practitioners to achieve superior aesthetic outcomes with minimal patient downtime. Companies like InMode Ltd. and Solta Medical are leading this wave by introducing versatile consoles that reduce equipment footprint in ambulatory surgical centers.
COVID-19 impact analysis and recovery trajectory
The pandemic caused a temporary contraction in the Dermatosurgical Devices Market market size as elective aesthetic procedures were deferred globally. Supply chain bottlenecks affecting raw materials like optical crystals and medical-grade titanium hindered device assembly. A robust recovery materialized as hospitals and specialized clinics resumed full-scale surgical operations, backed by telehealth pre-consultations.
Competitive benchmarking and strategic dynamics
The competitive landscape is moderately consolidated, featuring aggressive portfolio expansion by heavyweights like Bausch Health, Candela Corporation, and Sisram Medical (Alma Lasers). Strategic mergers and acquisitions allow these players to integrate proprietary radiofrequency and cryosurgical technologies, creating high barriers to entry for smaller, independent device manufacturers.
Executive summary of the Dermatosurgical Devices Market
The Dermatosurgical Devices Market is poised for remarkable expansion, projected to surge from $7.50 Billion in 2026 to $14.83 Billion by 2033 at a robust CAGR of 10.23%. This trajectory is underpinned by technological convergence in laser and electrosurgical modalities, high prevalence of dermatological disorders, and expanding outpatient surgical infrastructure.
Market forecast from 2027 to 2033
Our forecasting models confirm that the Dermatosurgical Devices Market will accelerate rapidly between 2027 and 2033, achieving a market valuation of $14.83 Billion. This sustained 10.23% CAGR reflects increasing adoption rates of automated suturing devices and liquid nitrogen delivery systems across specialized outpatient facilities.
Segmentation analysis across product, application, end-user, and distribution channels
The market breaks down by product type including laser, electrosurgical, and cryosurgical devices; by application covering tattoo removal, skin cancer, and cosmetic surgery; by end-user spanning hospitals, ambulatory surgical centers, and dermatology clinics; and via distribution channels like online sales channels and direct sales. Specialized laser devices dominate revenue share due to high procedural volumes.
Regional market analysis and geographic performance
Geographic performance highlights North America as the dominant revenue contributor, sustained by high healthcare expenditure and rapid adoption of advanced dermatologic technologies. Meanwhile, the Asia-Pacific region exhibits the fastest-growing adoption rate, driven by expanding medical tourism hubs in Thailand and South Korea, alongside rising demand for aesthetic enhancements.
In-depth regional review of key geographic markets
North America remains anchored by favorable FDA clearance pathways and robust reimbursement frameworks for medically necessary skin cancer excisions. Conversely, European markets face complex regulatory hurdles under the EU Medical Device Regulation (MDR), compelling local innovators like El.En. S.p.A. (DEKA) and Erbe Elektromedizin GmbH to prioritize rigorous clinical trial documentation.
Company profiles and strategic positioning of leading participants
Industry leaders maintain competitive moats through continuous R&D and targeted acquisitions. B. Braun Melsungen AG and CONMED Corporation dominate the suturing and electrosurgical segments, whereas Cutera Inc. and Sciton Inc. focus heavily on high-end energy delivery platforms for specialized dermatology practices and premier aesthetic clinics.
Porter's Five Forces analysis of the industry
Buyer power is moderate, as practitioners demand high clinical efficacy and reliable warranties. Supplier power remains low-to-moderate due to specialized raw material requirements for optical fibers and semiconductors. Threat of substitutes is minimal given the specialized precision required in dermatosurgery, keeping overall industry rivalry intensely high among established players.
SWOT analysis of the Dermatosurgical Devices Market
Key strengths include high procedural efficacy and strong demographic demand. Weaknesses involve prohibitive equipment costs and stringent maintenance requirements. Opportunities lie in emerging microdermabrasion and ultrasound-based devices, while threats include regulatory delays and risks associated with counterfeit consumable components traded through unauthorized online sales channels.
Value chain analysis from raw materials to end-users
The value chain initiates with advanced material sourcing—such as medical-grade stainless steel, optical crystals, and specialized polymers—followed by precision engineering and assembly. Finished goods flow through direct sales or third-party distributors to reach end-users like hospitals, ambulatory surgical centers, and dedicated dermatology clinics.
Investment insights and high-potential growth areas
Investors should target manufacturers specializing in fractional laser systems, portable cryoablation units, and hybrid radiofrequency electrosurgical devices. High-growth opportunities are concentrated in emerging regional markets where third-party distributors are rapidly scaling logistical networks to supply underserved private dermatology practices.
Conclusion and key takeaways for stakeholders
The Dermatosurgical Devices Market offers compelling long-term potential, underpinned by a forecasted expansion to $14.83 Billion by 2033. Stakeholders must prioritize regulatory compliance under evolving global frameworks and invest in multi-functional device platforms to capture market share across hospitals and ambulatory surgical centers.
Research methodology for baseline estimates and data triangulation
Our research methodology combines exhaustive primary stakeholder interviews with C-level executives, regulatory filing audits from bodies like the FDA, and secondary macroeconomic indicators. Data triangulation reconciles customs export registries with annual corporate reports from key participants like Johnson & Johnson and Olympus Corporation to ensure precise baseline estimates.
Scope of the report and coverage parameters
This report covers global revenue performance for the Dermatosurgical Devices Market from historical baselines through the forecast period ending in 2033. Analysis is segmented strictly across specified product types, applications, end-users, and distribution channels, explicitly excluding non-surgical consumer skincare products and over-the-counter topical treatments.
Recent developments, product launches, and strategic partnerships
Recent industry momentum is defined by strategic portfolio expansions. Innovators like Aerolase Corporation, Cartessa Aesthetics LLC, and Lynton Lasers Ltd. have introduced next-generation portable laser systems equipped with advanced cooling technologies. Meanwhile, partnerships between device manufacturers and specialized clinic chains are accelerating market penetration across North America and Europe.