What is the scope and industry significance of the Cocoa Butter Market?
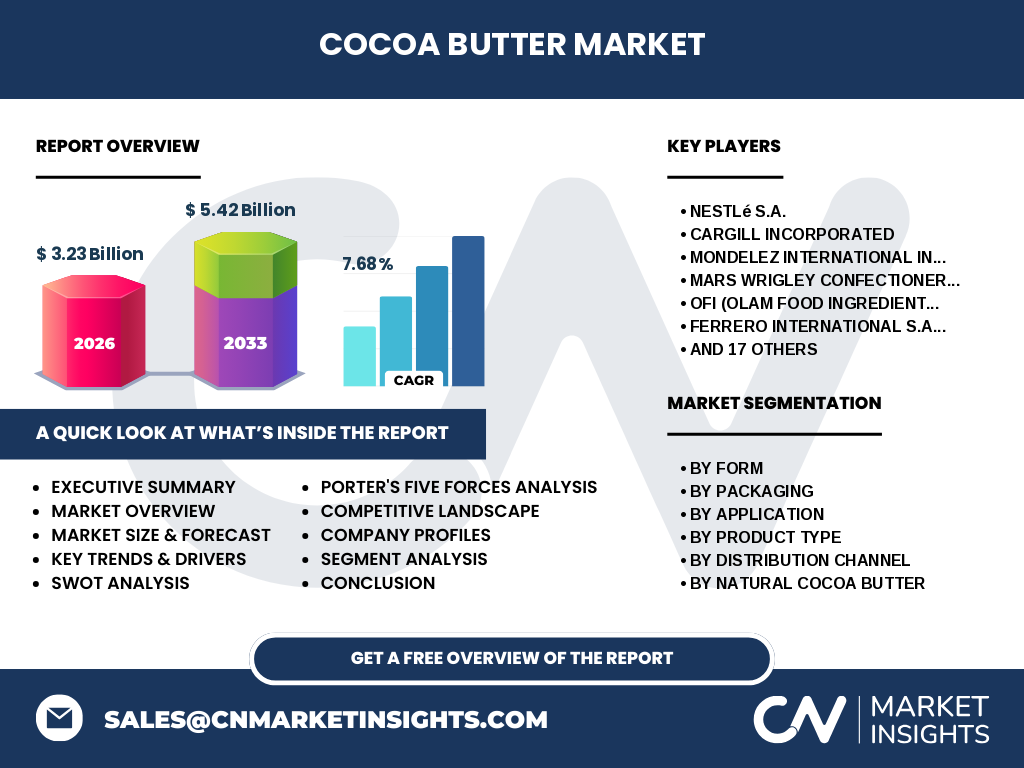
Our analysis indicates that the Cocoa Butter Market valued at 3.23 Billion in 2026 is a cornerstone of global food and cosmetic processing. Derived from Theobroma cacao beans, this vegetable fat governs the melting profile of premium confectionery and provides vital emollient properties for personal care formulations worldwide.
What are the key market drivers, restraints, challenges, and opportunities shaping the Cocoa Butter Market?
The Cocoa Butter Market industry trends reveal robust demand driven by consumer preference for clean-label, plant-based cosmetics. However, acute supply chain bottlenecks, climate-induced crop failures in West Africa, and volatile raw material pricing act as major restraints. This creates lucrative opportunities for valorizing secondary streams like deodorized and organic grades.
Emerging trends and growth patterns in the Cocoa Butter Market
The market is witnessing an aggressive pivot toward sustainably sourced ingredients. Industry titans like Barry Callebaut AG and Cargill Incorporated are spearheading traceable supply chains. Growth patterns emphasize cold-pressed and unrefined natural varieties tailored for high-end skincare and artisanal chocolate manufacturers.
How did COVID-19 impact the Cocoa Butter Market and shape its recovery trajectory?
The pandemic severely disrupted port logistics in Amsterdam and Abidjan, causing erratic price spikes. As international trade stabilized, our research highlights a V-shaped recovery propelled by e-commerce expansion in online retail channels, heavily benefiting direct-to-consumer cosmetic and confectionery brands.
Competitive Benchmarking and Industry Concentration
The Cocoa Butter Market analysis demonstrates a moderately consolidated landscape dominated by global processing giants such as ofi (Olam Food Ingredients), Nestlé S.A., and Mondelez International Inc. These players leverage massive milling capacities and integrated origination networks to maintain pricing power against boutique competitors.
Executive Summary of the Cocoa Butter Market
Driven by rising disposable incomes and clean-label demands, the Cocoa Butter Market is poised for significant expansion. Grounded by rigorous empirical data, our report projects the market to surge from 3.23 Billion in 2026 to 5.42 Billion by 2033, expanding at a robust CAGR of 7.68%.
Market Forecast and Long-Term Projections (2027-2033)
Based on our research models, the Cocoa Butter Market market size will expand consistently through the forecast window. Achieving a 7.68% CAGR to reach 5.42 Billion by 2033, growth will be heavily supported by pharmaceutical excipient innovations and premium confectionery adoption across developing economies.
Segmentation Analysis across Forms, Packaging, and Applications
The market bifurcates across multiple dimensions. By form, it spans blocks or solid, liquid, and powder. Packaging includes tins, cartons, and plastic containers. Applications cover Chocolate And Confectionery, Cosmetics And Personal Care, and Pharmaceuticals, each utilizing specific natural, deodorized, or organic product types.
Geographic Distribution and Regional Performance
Regional performance varies due to localized manufacturing hubs and consumer demographics. Europe remains a dominant processing and consumption center anchored by institutional players like Puratos Group N.V., while Asia-Pacific registers the fastest acceleration driven by expanding confectionery capacities in Malaysia and Indonesia.
In-Depth Regional Review of High-Growth Territories
West Africa continues to control upstream bean grinding through entities like Cocoa Processing Company Limited, while North America anchors downstream demand. Regulatory frameworks enforced by bodies like the FDA and EFSA strictly govern melting point standards and contaminant thresholds across these key regional importing territories.
Strategic Positioning of Leading Companies
Key market participants such as Mars Wrigley Confectionery, The Hershey Company, and Fuji Oil Holdings Inc. focus heavily on vertical integration and specialty fraction development. Companies like Guan Chong Berhad (GCB) and JB Cocoa Sdn. Bhd. optimize large-scale milling efficiencies in Asia.
Porter's Five Forces Analysis of the Cocoa Butter Market
Supplier power remains intensely high due to geographic concentration of cocoa bean production in West Africa. Buyer power is moderate-to-high, dictated by multinational confectioners. Threat of substitutes is mitigated by strict regulatory definitions of real cocoa butter in premium chocolate standards.
SWOT Analysis of the Global Industry
Strengths include superior crystallization properties and rich emollient profiles. Weaknesses stem from supply chain vulnerability and commodity price volatility. Opportunities lie in organic and fair-trade certifications, while threats include climate change impacts on crop yields and synthetic fat alternatives.
Value Chain Analysis from Raw Materials to End-Users
The value flow begins with smallholder farmers harvesting Theobroma cacao, moving through primary aggregation by traders like ECOM Agroindustrial Corp. Ltd. and Touton S.A., industrial pressing by processors, and final formulation by cosmetic and confectionery brands targeting retail channels.
Investment Insights and Strategic Recommendations
High-potential areas include investing in traceable, cold-pressed organic supply chains and sustainable milling infrastructure. Stakeholders should prioritize long-term farming partnerships in origin countries to hedge against raw material shortages and secure premium-grade inputs for pharmaceutical applications.
Conclusion and Key Takeaways
The Cocoa Butter Market industry trends confirm an accelerating transition toward high-purity, traceable ingredients. With a projected valuation of 5.42 Billion by 2033, industry participants must proactively address supply chain risks while capitalizing on surging cosmetic and food processing demand.
Research Methodology for Data Triangulation
Our baseline estimates are rigorously triangulated by combining direct trade registry data from major ports, primary stakeholder interviews with executives at firms like Niche Cocoa Industry Limited and Indcresa S.A., and secondary macroeconomic indicators regarding agricultural commodities.
Scope of the Report and Analytical Limitations
This report covers global consumption, production, and trade dynamics of cocoa butter across specified product grades, forms, packaging types, and distribution channels. Limitations include unforeseen geopolitical trade disruptions and rapid currency fluctuations impacting emerging market valuations.
Recent Corporate Developments and Strategic Moves
Recent industry momentum features strategic facility expansions by Plot Enterprise Ghana Limited and targeted sustainability partnerships by Ferrero International S.A. Concurrently, innovators like Kocoatrait Co. Ltd. are advancing eco-friendly packaging and zero-waste processing methodologies to meet evolving consumer expectations.