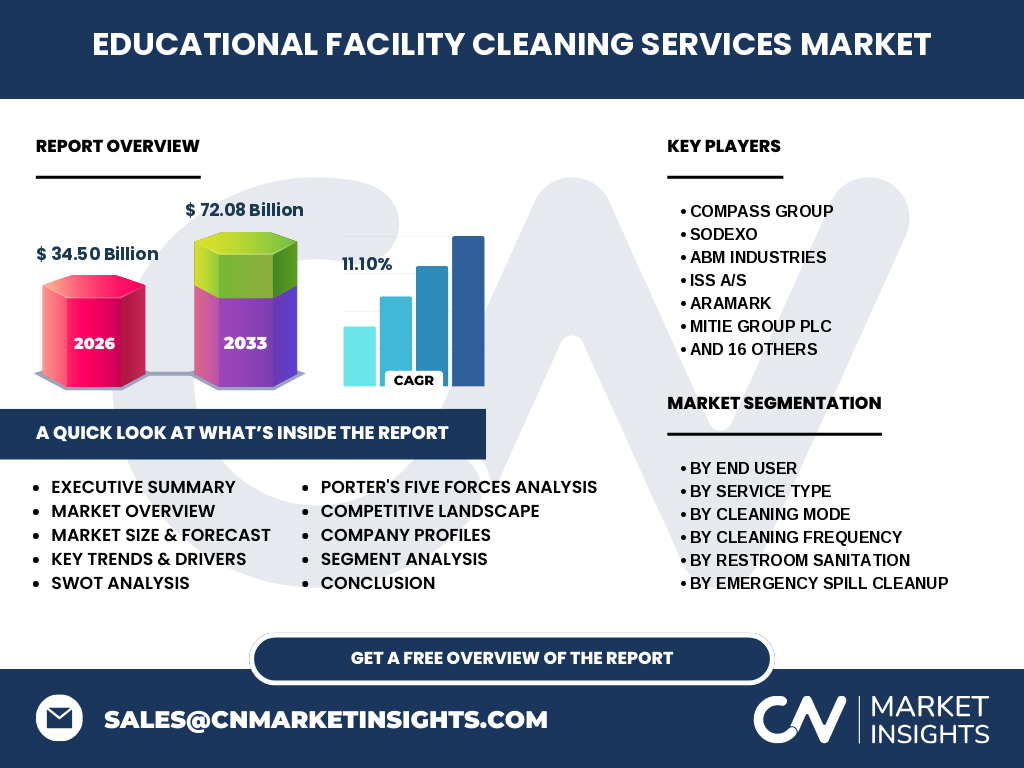
What is the market overview of the Educational Facility Cleaning Services Market?
Our analysis indicates the Educational Facility Cleaning Services Market encompasses professional janitorial, disinfection, and specialized maintenance solutions tailored for academic environments. Valued at 34.50 Billion in 2026, this sector is essential for maintaining health compliance, protecting institutional assets, and ensuring safe learning spaces across primary, secondary, and higher education facilities globally.
What are the key market drivers, restraints, challenges, and opportunities shaping the industry?
The market is propelled by stringent OSHA and public health mandates requiring rigorous sanitation. However, high labor turnover and rising chemical procurement costs act as primary restraints. Significant opportunities lie in adopting autonomous floor-scrubbing technologies and specialized biohazard mitigation protocols to meet post-pandemic cleanliness expectations across campuses.
Emerging trends and growth patterns in Educational Facility Cleaning Services Market
The sector is witnessing a definitive shift toward green cleaning chemistry and sustainable waste management. Facilities increasingly demand data-driven, on-demand sanitation models rather than rigid, fixed schedules, allowing providers to optimize labor deployment and reduce environmental impact while adhering to strict local municipal waste regulations.
How did the COVID-19 pandemic impact the Educational Facility Cleaning Services Market and its recovery trajectory?
The pandemic fundamentally transformed the industry, elevating janitorial services from a background utility to a core operational priority. Infection control protocols, such as electrostatic disinfection, became mandatory. The recovery trajectory shows sustained budget allocations for hygiene, cementing a permanent demand baseline for advanced pathogen removal services.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
The market features a mix of multinational facility conglomerates and specialized janitorial franchises. Industry leaders like Compass Group, Sodexo, and ABM Industries leverage massive scale, while specialized providers like Jani-King International Inc. and Coverall North America Inc. dominate localized contracts through robust franchise networks.
Executive summary of key findings in the Educational Facility Cleaning Services Market
Driven by heightened health awareness and institutional expansion, our research projects the market to reach 72.08 Billion by 2033, expanding at a robust 11.10% CAGR from 2027. Outsourced models are gaining significant share over in-house operations as administrators seek liability reduction and cost predictability.
Market forecast and growth projections from 2027 to 2033
Based on our econometric modeling, the market will experience accelerated expansion, surging from its 2026 baseline to 72.08 Billion by 2033. This trajectory reflects an 11.10% CAGR, fueled by rising investments in higher education infrastructure and mandatory sanitation standards enforced by regional health departments.
Segmentation analysis across end-users, services, cleaning modes, and frequencies
The market is segmented by end-users (Public/Private Institutions, Higher Ed Campuses), service types (General Janitorial, Deep Cleaning, Restroom Sanitation), cleaning modes (In-House vs. Outsourced), and frequencies (Daily, Weekly, Periodic). Higher Education Campuses and Outsourced Contract Cleaning represent the largest revenue-generating segments due to complex facility layouts.
Geographic distribution and regional performance in the Educational Facility Cleaning Services Market
Regional performance varies based on municipal hygiene budgets and school infrastructure spending. North America leads in market adoption due to stringent health guidelines, while Asia-Pacific represents the fastest-growing region, driven by rapid urbanization and the expansion of private educational institutions and international coaching centers.
In-depth regional review of key geographic markets
North America commands the highest market share, supported by rigorous state-level facility inspection standards. Meanwhile, Europe demonstrates steady growth driven by strict European Union environmental directives regarding chemical usage. Emerging markets in Latin America and MEA show increasing reliance on structured outsourcing to upgrade hygiene standards.
Strategic positioning of leading companies in the industry
Industry giants such as ISS A/S, Aramark, and Mitie Group Plc focus on integrated facility management contracts bundling cleaning with security and maintenance. Meanwhile, firms like Cintas Corp and Rentokil Initial Plc specialize in hygiene supply replenishment and high-margin pathogen control services.
Porter's Five Forces analysis of the cleaning services sector
Competitive rivalry is intense, driven by numerous localized operators and low initial startup barriers. However, buyer power is moderate to high due to competitive bidding processes in public tenders. Supplier power remains low regarding cleaning chemicals, though labor scarcity elevates workforce-related operational pressures across all regions.
SWOT analysis of the Educational Facility Cleaning Services Market
Key strengths include essential service demand and recurring revenue models. Weaknesses involve high employee turnover and wage inflation. Opportunities emerge from IoT-enabled smart restroom monitoring, while threats include macroeconomic downturns impacting municipal education budgets and unforeseen supply chain disruptions for sanitizing agents.
Value chain analysis from raw materials to educational end-users
The value chain initiates with chemical manufacturers and equipment fabricators, flowing through national distributors to facility service providers. Contractors then deploy trained labor and proprietary software to execute protocols for educational institutions, capturing value through service reliability, compliance assurance, and workforce management efficiency.
Investment insights and high-potential growth areas
High-potential investment targets include technology-enabled cleaning providers utilizing autonomous scrubbers and IoT supply monitoring. Investors should prioritize firms offering specialized laboratory deep sanitization and biohazard spill management, as these niche capabilities command higher margins and defend against commoditization.
Conclusion and key takeaways for industry stakeholders
The Educational Facility Cleaning Services Market offers compelling growth, projected to hit 72.08 Billion by 2033 at an 11.10% CAGR. Success requires balancing technological integration, such as electrostatic disinfection, with rigorous labor retention strategies to meet evolving institutional demands.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are established by triangulating primary stakeholder interviews with facility directors, secondary trade registry data, and macroeconomic educational spending indicators. This multi-layered approach ensures precise sizing of segments like floor care, restroom sanitation, and waste management.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue streams for educational facility cleaning from 2026 to 2033. Scope parameters encompass all major cleaning modes, frequencies, and end-user tiers. Limitations include potential variance in localized informal cleaning markets where municipal procurement data is restricted or unrecorded.
Recent developments, corporate partnerships, and strategic expansions
Recent industry activity highlights strategic acquisitions by firms like Bidvest Noonan and Churchill Contract Services to expand their educational portfolios. Concurrently, companies are heavily investing in eco-friendly chemical formulations and IoT-enabled dispenser networks to secure long-term municipal and university contracts.