What is the market overview of the Minimally Invasive Medical Robots Market?
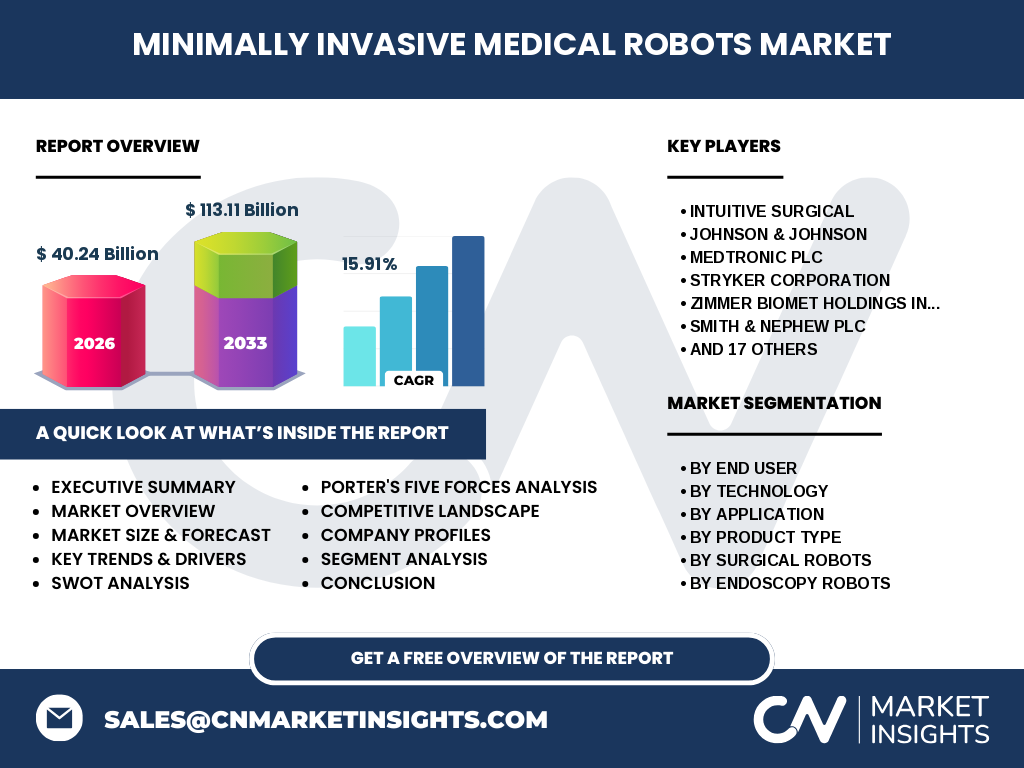
Our analysis indicates that the Minimally Invasive Medical Robots Market encompasses advanced surgical systems, rehabilitation devices, and navigation platforms engineered to minimize patient trauma. Valued at 40.24 Billion in 2026, the industry is witnessing robust integration of medical-grade titanium raw materials and specialized optical sensors, driven by strict regulatory approvals from bodies like the US FDA and EMA.
Structural Growth Drivers and Restraints
The market is propelled by a rising preference for scarless surgeries and rapid recovery times, yet constrained by high capital expenditure requirements for robotic consoles. Supply chain bottlenecks involving semiconductor shortages for AI-enabled robotic systems continue to pose logistical hurdles for manufacturers sourcing precision actuators globally.
Emerging trends and growth patterns in the Minimally Invasive Medical Robots Market
The shift toward cloud-connected telesurgery and machine-learning diagnostic overlays is transforming the Minimally Invasive Medical Robots Market industry trends. Innovations in flexible endoscopy and remote telepresence are allowing specialists at major medical hubs to perform procedures across international borders with minimal latency.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced elective surgery cancellations temporarily depressed device utilization rates, but accelerated the adoption of telepresence and patient monitoring robots to reduce infection risks. Post-pandemic recovery has been aggressive, fueled by hospital capital reinvestment into automated surgical suites and remote-controlled assistance platforms.
Competitive Benchmarking and Market Concentration
The landscape features high concentration among pioneers like Intuitive Surgical, Medtronic plc, and Stryker Corporation, who dominate through proprietary instruments and extensive hospital networks. Meanwhile, emerging contenders like CMR Surgical Ltd. and Moon Surgical SAS challenge incumbents with modular, cost-effective architectures.
Executive summary of key findings for the Minimally Invasive Medical Robots Market
Our research projects the market to surge from 40.24 Billion in 2026 to 113.11 Billion by 2033, representing a remarkable 15.91% CAGR. Hospitals and ambulatory surgical centers remain the primary revenue engines, heavily prioritizing AI-enabled and image-guided systems to enhance clinical precision.
Market forecast trajectory from 2027 to 2033
Driven by compounding technological adoption and expanding reimbursement codes, the Minimally Invasive Medical Robots Market market size is set for exponential acceleration, scaling from 2027 through 2033 to reach 113.11 Billion at a 15.91% CAGR, significantly outpacing traditional open-surgery equipment growth.
Segmentation analysis across product types, technologies, applications, and end-users
Segmentation spans product types (surgical, rehabilitation, endoscopy, telepresence, navigation robots), technologies (AI-enabled, image-guided, remote), applications (general, orthopedic, neuro, cardio, urology), and end-users (hospitals, ASCs, specialty clinics, research institutes). Hospitals currently command the largest revenue share due to high patient throughput and substantial capital budgets.
Regional market analysis and geographic distribution
North America leads consumption due to advanced healthcare infrastructure and early Medicare/private insurance reimbursement for robotic procedures. Concurrently, Asia-Pacific represents the fastest-growing region, stimulated by rising healthcare expenditures in urban centers across China, Japan, and South Korea.
In-depth regional review of high-growth territories
Regulatory harmonization by the Pharmaceuticals and Medical Devices Agency (PMDA) in Japan and expedited clearance pathways in the US create fertile ground for market expansion. Localized hospital procurement policies in Europe increasingly favor modular systems that integrate seamlessly with existing operating room infrastructure.
Strategic positioning of leading companies in the sector
Industry giants such as Johnson & Johnson, Zimmer Biomet Holdings Inc., and Smith & Nephew plc leverage robust distribution networks to entrench orthopedic and general surgical platforms. Niche players like Accuray Incorporated and Stereotaxis Inc. focus on precision radiation and magnetic navigation technologies, respectively.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to specialized optical and computing components, while buyer power is high as hospital procurement committees demand bundled pricing. Threat of new entrants is mitigated by steep R&D costs, stringent clinical trial hurdles, and extensive intellectual property moats held by incumbents.
SWOT analysis for strategic market navigation
Strengths include high clinical efficacy and surgeon brand loyalty; weaknesses involve prohibitive unit costs and lengthy training curves. Opportunities lie in ambulatory surgery center expansion and AI software upgrades, while threats encompass tightening cybersecurity regulations for connected surgical units.
Value chain analysis from raw materials to end-users
The value chain flows from rare earth metals and medical-grade polymers suppliers to precision component fabricators, robotic system assemblers (such as MicroPort MedBot Co. Ltd. and Medicaroid Corporation), and finally to hospital surgical suites where clinical deployment occurs.
Investment insights and high-potential areas
Investors should target early-stage innovators developing portable, AI-driven navigation systems and low-latency telesurgery infrastructure. Companies offering software-as-a-service (SaaS) updates for existing robotic hardware present particularly attractive recurring revenue models.
Conclusion and key takeaways
The Minimally Invasive Medical Robots Market represents a high-growth frontier in healthcare technology, underpinned by a 15.91% CAGR toward 2033. Strategic consolidation, technological convergence with artificial intelligence, and expanding global healthcare access will continue to define market leaders.
Research methodology and baseline estimation triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with Chief Medical Officers and procurement directors, and macroeconomic indicators such as national healthcare expenditure growth across major economies.
Scope of the report and coverage parameters
This report covers global revenue performance, volume shipments, and technological evaluations across all specified product categories from 2026 to 2033. Limitations include excluding veterinary robotic applications and strictly focusing on human clinical healthcare delivery systems.
Recent developments, partnerships, and strategic product launches
Recent milestones include Globus Medical Inc. and THINK Surgical Inc. launching next-generation open-platform orthopedic robots, alongside Virtual Incision Corporation and Robocath SAS securing regulatory clearances for miniaturized abdominal and vascular intervention systems.