What is the market overview and industry significance of the Clinical Genomics Interpretation Platforms Market?
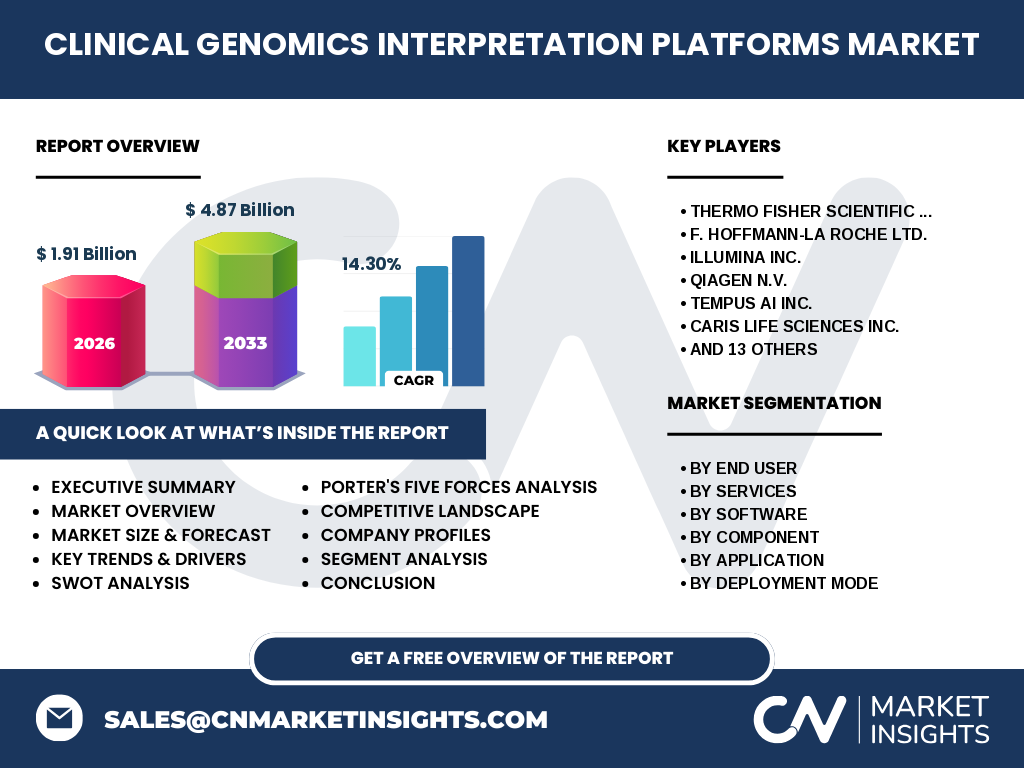
Our analysis indicates the Clinical Genomics Interpretation Platforms Market represents a critical digital bridge between high-throughput sequencing data and actionable clinical oncology, achieving a 1.91 Billion valuation in 2026. These specialized bioinformatics frameworks transform raw genomic variants into structured clinical insights under stringent regulatory frameworks like FDA and CE-IVD mandates.
Structural Growth Drivers and Market Restraints
The market thrives on plummeting sequencing costs and expanding multi-omic clinical trials, yet faces severe headwinds regarding variant interpretation bottlenecks. Based on our research, compliance hurdles with GDPR and HIPAA alongside reimbursement complexities for somatic profiling restrict rapid deployment across smaller community hospitals.
Emerging Trends in Genomic Analytics
The shift toward Artificial Intelligence Based Genomic Interpretation Platforms is redefining diagnostic precision. Leaders like Tempus AI Inc. and Nference leverage proprietary real-world evidence repositories to streamline variant curation, drastically reducing manual curation workloads for molecular pathologists.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic catalyzed a structural pivot toward cloud-native bioinformatics infrastructure, as remote molecular pathology teams required decentralized access. Our research confirms that post-pandemic diagnostic backlogs accelerated hospital investments in scalable Cloud-Based pipelines to process surging oncology and infectious disease panels.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high among established molecular diagnostics giants such as Illumina Inc., F. Hoffmann-La Roche Ltd., and Thermo Fisher Scientific Inc., who bundle sequencing hardware with proprietary annotation software. Meanwhile, agile innovators like SOPHiA GENETICS SA and DNAnexus carve out defensible niches via agnostic, interoperable platform ecosystems.
Executive Summary of Clinical Genomics Interpretation Platforms Market
Driven by an exceptional CAGR of 14.30%, the market is projected to surge from 1.91 Billion in 2026 to 4.87 Billion by 2033. Accelerated adoption of precision oncology and rare disease diagnostics fuels this trajectory, rewarding platform vendors offering robust clinical decision support and seamless electronic health record integration.
Long-Term Market Forecast from 2027 to 2033
The data suggests sustained double-digit expansion will push total revenues to 4.87 Billion by 2033. This exponential scaling is propelled by mainstream clinical adoption of pharmacogenomics and liquid biopsy assays, demanding high-throughput variant annotation and automated clinical reporting workflows.
Segmentation Analysis Across Software, Services, and Applications
The market divides across software, services, and end-user verticals.
- Software: Includes Variant Interpretation, Clinical Decision Support, and AI-driven engines.
- Services: Encompasses Genomic Data Interpretation and Maintenance.
- Applications: Dominated by Oncology and Rare Diseases.
- End Users: Hospitals, Diagnostic Labs, and Research Institutes.
Regional Market Analysis and Geographic Distribution
North America commands the largest market share, sustained by favorable reimbursement policies and high concentrations of precision medicine cancer centers. Conversely, Asia-Pacific represents the fastest-growing regional frontier, fueled by massive national sequencing initiatives in genomics hubs across East Asia.
In-Depth Regional Review
European adoption is heavily influenced by centralized healthcare procurement and stringent IVDR compliance mandates favoring certified software like those from QIAGEN N.V. and BC Platforms AG. Meanwhile, the US market prioritizes rapid clinical utility, driving widespread hospital adoption of commercial decision support systems.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct competitive moats: Caris Life Sciences Inc. and Variantyx Inc. leverage proprietary clinical-genomic databases for companion diagnostics, whereas Genomenon Inc. and Golden Helix Inc. excel in high-speed genomic search engines and transparent variant annotation software.
Porter's Five Forces Analysis of the Industry
Competitive rivalry remains intense among software vendors striving for interoperability standards. Buyer power is moderate-to-high, as large hospital networks demand custom EHR integration, while threat of new entrants is mitigated by high regulatory barriers and proprietary variant knowledge bases.
SWOT Analysis of the Sector
Key strengths include powerful AI variant classification algorithms and scalable cloud architectures. Weaknesses involve complex clinical validation requirements and workflow integration friction. Opportunities lie in emerging pharmacogenomics applications, while data privacy breaches remain a persistent threat.
Value Chain Analysis from Raw Data to End-Users
The value flow begins with raw sequencing data generated on hardware from Illumina or Thermo Fisher, moves through secondary alignment tools, and culminates in tertiary interpretation platforms by players like Fabric Genomics Inc. and SeqOne Genomics. End-users receive finalized, actionable oncology reports.
Investment Insights and High-Potential Areas
Venture capital and strategic acquirers should prioritize platforms featuring embedded Large Language Models for automated clinical report generation. Small and specialty clinics also represent an underpenetrated, high-potential segment requiring lightweight, turnkey SaaS interpretation solutions.
Conclusion and Key Takeaways
The Clinical Genomics Interpretation Platforms Market is transitioning from an academic luxury into an essential clinical utility. Achieving a 4.87 Billion valuation by 2033, market success will decisively favor vendors who seamlessly blend regulatory compliance, AI-driven automation, and frictionless hospital workflow integration.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining secondary macroeconomic indicators from global health registries, primary stakeholder interviews with chief medical officers, and proprietary trade data from enterprise software deployments across diagnostic laboratories and large hospital networks.
Scope of the Report and Coverage Parameters
This report encompasses global software, services, deployment modes, and application verticals from 2026 through 2033. Excluded from this scope are wet-lab sequencing instruments and general laboratory information management systems not directly involved in tertiary genomic variant interpretation.
Recent Developments and Strategic Industry Moves
Recent market activity highlights aggressive consolidation and strategic partnerships, such as Velsera Inc. expanding clinical data networks and IntelliSeq Corporation launching modular consumer-clinical reporting pipelines. These moves underscore a broader industry drive toward modularity, interoperability, and accelerated variant turnaround times.