What is the market overview and industry significance of the Artificial Intelligence (AI) Cloud Cost Optimization Market?
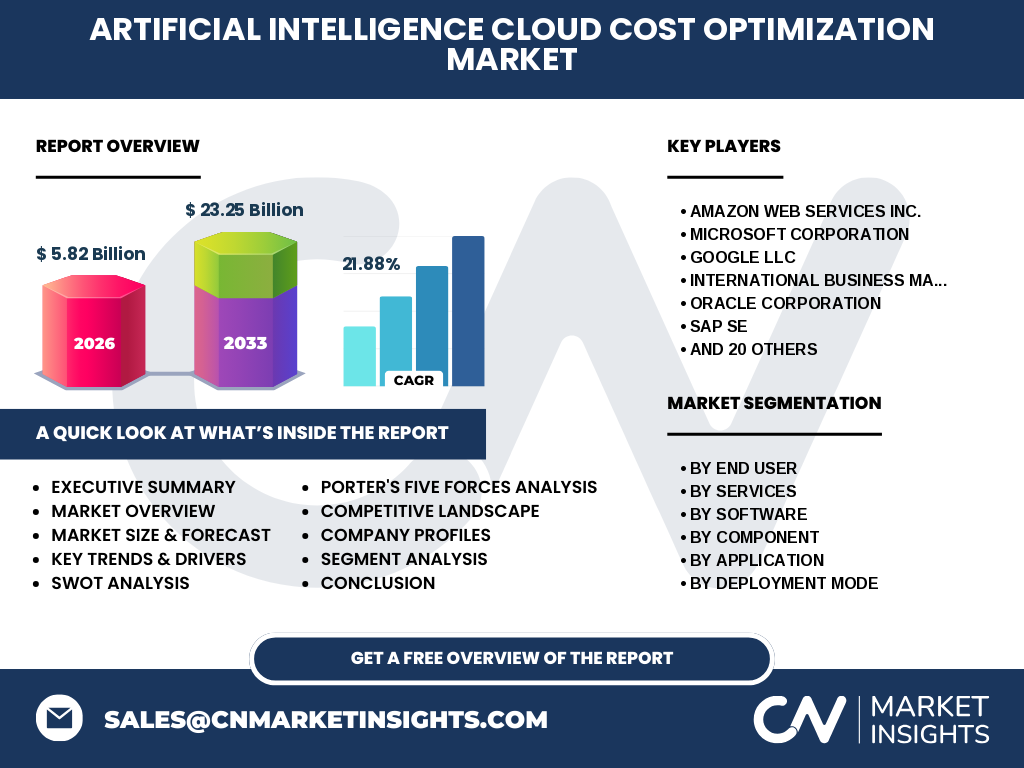
Our analysis indicates that the Artificial Intelligence (AI) Cloud Cost Optimization Market reaches $5.82 Billion in 2026. This sector encompasses specialized software and services designed to autonomously reduce hyperscale infrastructure waste. As enterprises scale resource-intensive machine learning workloads across AWS and Azure, automated FinOps tools become indispensable for margin protection.
What are the key market drivers, restraints, challenges, and opportunities shaping the Artificial Intelligence (AI) Cloud Cost Optimization Market?
The market is propelled by explosive LLM training expenses and complex multi-cloud billing structures. However, stringent data sovereignty regulations in the European Union under the GDPR constrain automated cross-border workload migration. The primary opportunity lies in integrating predictive forecasting with real-time Kubernetes container orchestration.
What are the emerging trends and growth patterns in the Artificial Intelligence (AI) Cloud Cost Optimization Market?
The shift toward autonomous cost remediation represents a defining trend. Rather than relying on static alerts, platforms developed by innovators like CAST AI and Zesty Tech are executing live instance rightsizing without human intervention, dramatically shrinking cloud bills for data-heavy organizations.
How did COVID-19 impact the Artificial Intelligence (AI) Cloud Cost Optimization Market and shape its recovery trajectory?
The pandemic accelerated digital migration, resulting in unchecked cloud spending across distributed enterprise networks. Post-COVID economic tightening forced CFOs to prioritize strict unit economics, transforming AI cloud cost tools from optional utilities into essential survival mechanisms.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
The competitive landscape features a mix of cloud native hyperscalers and agile pure-plays. Companies like Datadog, Dynatrace, and New Relic integrate observability with cost data, while specialized players like CloudZero and Finout deliver granular unit cost allocation for engineering teams.
Executive Summary: High-level synthesis of key findings about the Artificial Intelligence (AI) Cloud Cost Optimization Market
Our proprietary research confirms that the market is scaling rapidly toward $23.25 Billion by 2033. Achieving a robust 21.88% CAGR from 2027 to 2033, the sector is driven by the urgent need to control unstructured machine learning infrastructure expenses.
Market Forecast: Projected growth trajectory from 2027 to 2033
Growing from the 2026 baseline of $5.82 Billion to $23.25 Billion by 2033 at a 21.88% CAGR, expansion is fueled by widespread enterprise adoption of generative AI applications requiring continuous, automated resource governance.
Segmentation Analysis: Breaking down category roles in the Artificial Intelligence (AI) Cloud Cost Optimization Market
The market is segmented by end user (Banking, Financial Services, Insurance, Healthcare, Retail, IT and Telecom, Manufacturing, Government), services, software, component, application, deployment mode, and organization size. Each segment addresses specific operational requirements, from strict government compliance to high-frequency retail transaction processing.
Regional Market Analysis: Geographic distribution and performance dynamics
North America dominates adoption due to a high concentration of hyperscale data centers and early enterprise AI integration. Meanwhile, Asia-Pacific is registering the fastest acceleration, driven by rapid cloud transformation initiatives across financial hubs in Singapore, Tokyo, and Sydney.
In-Depth Regional Review: Key regional markets and localized constraints
Europe maintains steady expansion, heavily influenced by strict EU regulatory frameworks governing automated algorithmic decision-making. North American enterprises prioritize high-performance computing cost efficiency, whereas Latin American markets focus on hybrid cloud migration strategies.
Company Profiles: Strategic positioning of leading market participants
Industry leaders leverage distinct strategic advantages. Amazon Web Services, Microsoft, and Google provide native cloud financial management tools, while specialists like NetApp Spot, Kubecost, and Harness offer deep Kubernetes and multi-cloud optimization capabilities tailored for enterprise engineering workflows.
Porter's Five Forces Analysis of the Artificial Intelligence (AI) Cloud Cost Optimization Market
Threat of new entrants remains moderate due to high proprietary algorithm development costs. Buyer power is substantial as enterprises demand immediate ROI, while intense rivalry among specialized startups and established observability giants keeps pricing competitive.
SWOT Analysis for Artificial Intelligence (AI) Cloud Cost Optimization Market stakeholders
Strengths include high predictive accuracy and automated remediation. Weaknesses involve integration friction with legacy architectures. Opportunities center on generative AI workload tuning, while threats include potential security vulnerabilities during automated instance shutdowns.
Value Chain Analysis: Industry structure and value flow
The value chain flows from raw cloud telemetry data collection to advanced machine learning analytics and automated execution. Software vendors and managed service providers capture significant value by translating complex metering data into actionable financial intelligence for enterprise stakeholders.
Investment Insights: Strategic recommendations and high-potential areas
Investors should focus on early-stage innovators specializing in multi-cloud cost visibility and automated workload rightsizing. Companies partnering with major cloud providers or offering seamless Kubernetes integration present the highest potential for near-term valuation growth.
Conclusion and Key Takeaways for Market Stakeholders
The Artificial Intelligence (AI) Cloud Cost Optimization Market represents a critical frontier in modern enterprise IT financial management. With a projected expansion to $23.25 Billion by 2033, automated FinOps capabilities are vital for sustaining long-term artificial intelligence innovation.
Research Methodology: How baseline estimates are triangulated
Our baseline figures combine exhaustive trade registry data, primary stakeholder interviews with enterprise CIOs and FinOps directors, and secondary macroeconomic indicators. This triangulated approach ensures high fidelity in sizing the $5.82 Billion market.
Scope of the Report: Coverage parameters and analytical limitations
This report covers global deployment models across public, private, and hybrid cloud infrastructures. Limitations include rapid software version updates and unquantified shadow IT spending within emerging small and medium enterprise segments.
Recent Developments: Strategic moves, partnerships, and product launches
Recent market activities feature aggressive product rollouts from firms like CloudFix and Finout, alongside strategic acquisitions by major observability vendors. These moves emphasize real-time cost anomaly detection and automated multi-cloud unit economics.