Market overview of the Coke Dry Quenching (CDQ) Equipment Market
Our analysis indicates that the Coke Dry Quenching (CDQ) Equipment Market is a critical industrial sector valued at $0.90 billion in 2026. This technology captures sensible heat from red-hot coke via inert gas circulation, replacing traditional wet quenching to significantly reduce water consumption, lower carbon emissions, and recover waste energy in metallurgical steelmaking operations.
Key market drivers, restraints, challenges, and opportunities shaping Coke Dry Quenching (CDQ) Equipment Market
Stringent environmental mandates by regulatory bodies like the EPA and EU Industrial Emissions Directive act as primary structural growth drivers. However, high initial capital expenditure for complex refractory Coke Dry Quenching Cooling Rooms and Waste Heat Boilers restrains adoption among mid-tier steel producers. Significant opportunities lie in retrofitting legacy wet quenching batteries in developing Asian industrial corridors.
Emerging trends and growth patterns in Coke Dry Quenching (CDQ) Equipment Market
The sector is witnessing a rapid pivot toward automated, energy-efficient operations. Steel manufacturers increasingly demand Modular Cooling Rooms and Variable Speed Circulation Fans to optimize thermal efficiency and handle fluctuating coking cycles seamlessly, minimizing downtime during high-intensity production phases.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions and deferred capital expenditures for heavy industrial machinery. Despite these logistical hurdles, post-crisis stimulus packages prioritizing green manufacturing accelerated a robust recovery, pushing the Coke Dry Quenching (CDQ) Equipment Market industry trends toward accelerated decarbonization and automated plant upgrades.
Competitive landscape and strategic dynamics
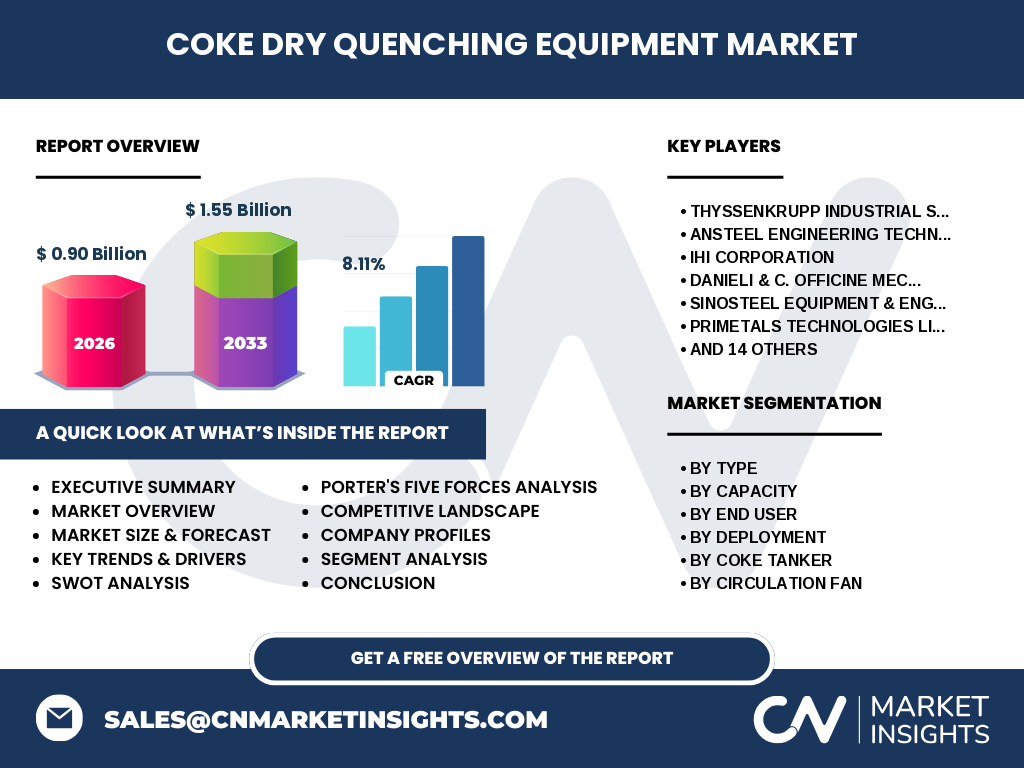
Market concentration remains moderately high, dominated by engineering giants like thyssenkrupp Industrial Solutions AG, Nippon Steel Engineering Co. Ltd., and Primetals Technologies Limited. These tier-one players leverage turnkey EPC capabilities, proprietary heat recovery designs, and global service networks to outmaneuver regional equipment fabricators.
Executive summary of key findings
Driven by stringent global decarbonization targets, the market demonstrates stellar expansion. Based on our research, the Coke Dry Quenching (CDQ) Equipment Market analysis projects a robust compound annual growth rate, cementing CDQ systems as non-negotiable assets for modern, environmentally compliant blast furnace steel plants.
Market forecast from 2027 to 2033
Our comprehensive forecasting models project the Coke Dry Quenching (CDQ) Equipment Market size to expand from $0.90 billion in 2026 to reach $1.55 billion by 2033, expanding at a notable CAGR of 8.11% over the forecast period, fueled by continuous environmental compliance upgrades.
Segmentation analysis across core categories
The industry is segmented by type, capacity, end user, and deployment. Key categories include Coke Dry Quenching Cooling Rooms, Circulation Fans, and Waste Heat Boilers. Capacity brackets range from less than 100 tons per hour to over 250 tons per hour, primarily serving Steel Manufacturers and the broader metallurgical industry.
Regional market analysis and geographic distribution
Asia-Pacific dominates the global footprint, propelled by massive steel production capacities in China and India where stringent environmental regulations compel a transition from wet to dry quenching. Meanwhile, Europe exhibits steady demand centered on brownfield retrofits aimed at carbon neutrality targets.
In-depth regional review of high-growth territories
In developing Asian markets, government mandates on energy conservation have made CDQ adoption mandatory for new coking plant licenses. Conversely, Western European steelmakers focus on high-efficiency Electric Coke Tankers and advanced Gas Cleaning Systems to comply with the EU's strict carbon border adjustment mechanisms.
Company profiles and strategic positioning
Industry leaders such as Sinosteel Equipment & Engineering Co. Ltd. and Danieli & C. Officine Meccaniche S.p.A. focus on technological differentiation through proprietary waste heat recovery configurations. Meanwhile, specialized firms like Thermax Limited and Isgec Heavy Engineering Limited target regional retrofitting projects with custom-engineered boiler solutions.
Porter's Five Forces analysis of the sector
Supplier power is moderate due to specialized refractory material requirements. Buyer power remains constrained by the high technical barrier to entry and critical reliance on proven engineering pedigree. However, threat of substitution is low given the unique environmental advantages of dry versus wet quenching.
SWOT analysis of the industry
Key strengths include exceptional energy recovery efficiency and severe particulate emission reductions. Weaknesses stem from high initial capital outlays and complex maintenance schedules. Opportunities thrive in emerging green steel initiatives, while threats include macroeconomic volatility affecting global raw material prices.
Value chain analysis from raw materials to end-users
The value chain spans raw material suppliers providing high-grade refractory bricks and specialized steel alloys, through OEM engineering firms fabricating Rail Mounted Coke Tankers and Natural Circulation Waste Heat Boilers, ultimately delivering turnkey systems to integrated steel manufacturers and energy producers.
Investment insights and strategic recommendations
Investors should direct capital toward firms offering modular, easily retrofitted CDQ packages. Our research highlights high-potential ROI in developing intelligent Temperature Monitoring Systems and advanced Dust Collection Systems that integrate seamlessly with existing blast furnace infrastructure.
Conclusion and key takeaways
The Coke Dry Quenching (CDQ) Equipment Market represents a high-conviction growth sector within heavy industrial engineering. Supported by a 8.11% CAGR through 2033, technological innovation in waste heat recovery and automated material handling will dictate long-term market leadership.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with C-suite executives at Paul Wurth S.A. and JFE Engineering Corporation, and secondary macroeconomic indicators tracking global coking coal consumption and steel output indices.
Scope of the report and coverage parameters
This report evaluates the global market across all designated equipment types, capacities, and end-user verticals from 2027 to 2033. Limitations include localized trade policy shifts and unforeseen macroeconomic fluctuations impacting heavy industrial capital expenditure cycles across emerging economies.
Recent developments and strategic moves in the market
Recent strategic moves feature major engineering alliances focusing on digital twin integration for predictive maintenance in Vertical Cooling Rooms. Companies like Ansteel Engineering Technology Corporation Limited and Shougang International Engineering Technology Co. Ltd. have announced proprietary upgrades targeting ultra-low emissions standards.