What is the scope and industry significance of the Automatic Wire Processing Machines Market?
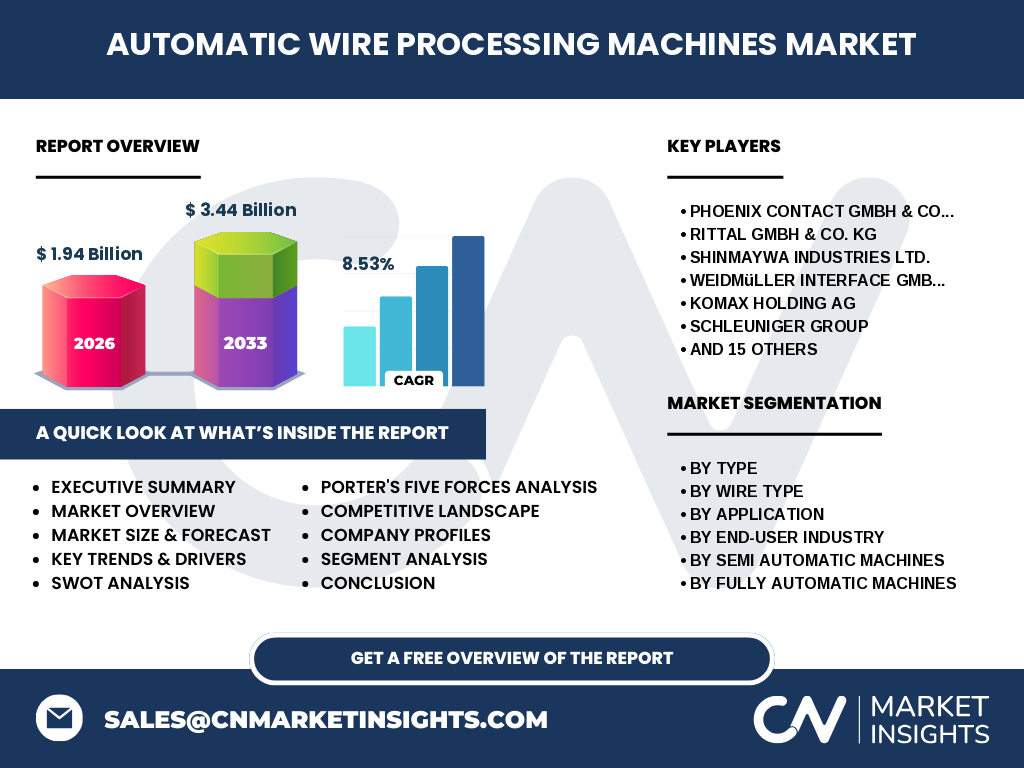
Our analysis indicates that the Automatic Wire Processing Machines Market valued at 1.94 Billion in 2026, forms the backbone of global electrical harness manufacturing. This sector encompasses precision systems handling everything from raw copper coils to integrated sub-assemblies. Industry significance lies in eliminating human error during high-speed cutting, stripping, and crimping, ensuring absolute compliance with stringent automotive and aerospace electrical standards.
Structural Growth Drivers and Restraints Shaping the Sector
The market is propelled by relentless automation demands in electric vehicle architecture and miniaturized electronics. Structural growth drivers include the shift toward lightweight aluminum and tinned copper wires requiring specialized mechanical adjustments. Conversely, restraints involve high initial capital expenditure for integrated wire processing systems and supply chain bottlenecks for high-grade tungsten carbide blades and precision servo motors.
Emerging Industry Trends in Wire Processing Automation
Industry trends highlight a rapid pivot toward fully automatic solutions equipped with intelligent vision systems and real-time quality monitoring. Komax Holding AG and Schleuniger Group are leading this charge by integrating IoT capabilities that enable predictive maintenance and remote diagnostics. This technological leap dramatically reduces setup times for complex multi-core and flat wire configurations.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted the Automatic Wire Processing Machines Market through factory shutdowns and raw material shortages of electrolytic copper and engineering plastics. However, our research reveals an accelerated post-pandemic recovery driven by aggressive factory automation initiatives. Manufacturers heavily invested in touchless, fully automatic machinery to insulate production lines from future labor shortages and localized lockdowns.
Competitive Benchmarking and Strategic Market Dynamics
Competitive dynamics reflect intense rivalry among specialized European and Asian engineering powerhouses. Key innovators like ShinMaywa Industries Ltd. and Phoenix Contact GmbH & Co. KG leverage modular architecture to capture market share across diverse manufacturing hubs. Consolidation remains active as established players acquire niche software firms to enhance their proprietary wire harness design and machine integration platforms.
Executive Summary of the Automatic Wire Processing Machines Market
Our comprehensive evaluation confirms that the Automatic Wire Processing Machines Market is on an aggressive upward trajectory. Driven by booming renewable energy installations and advanced automotive electronics, the market is poised to reach 3.44 Billion by 2033, expanding at a robust CAGR of 8.53% from 2027 onward.
Long-Term Market Forecast from 2027 to 2033
Based on our econometric modeling, the market valuation will scale from its 2026 baseline of 1.94 Billion to achieve 3.44 Billion by 2033. This consistent 8.53% CAGR underscores sustained global demand for high-throughput cable assembly solutions across both traditional industrial machinery and emerging EV charging infrastructure.
Comprehensive Segmentation Analysis of Equipment and Wire Types
The market divides across several critical vectors: By Type (Fully Automatic Machines, Semi Automatic Machines); By Wire Type (Single-Core Wires, Multi-Core Wires, Flat Wires, Customized Wires, Tinned Copper Wires); and By Application (Automotive, Electronics And Electrical Equipment, Aerospace, Telecommunications, Industrial Machinery). Furthermore, Fully Automatic variants feature Automatic Cutting And Stripping Machines, Automatic Crimping Machines, Automatic Twisting Machines, Automatic Labeling Machines, and Integrated Wire Processing Systems.
Geographic Distribution and Regional Performance Overview
Regional performance varies significantly based on industrial density and automotive manufacturing maturity. Asia-Pacific dominates volume consumption, anchored by extensive electronics manufacturing clusters in China and Japan. Meanwhile, North America and Europe prioritize high-value, fully automatic integrated systems complying with rigorous IPC/WHMA-A-620 standards for aerospace and medical device wiring.
In-Depth Regional Review of High-Growth Industrial Hubs
In-depth regional analysis highlights strong growth within European automotive corridors, where companies like Rittal GmbH & Co. KG and Weidmüller Interface GmbH & Co. KG supply advanced cabinet assembly tooling. Concurrently, Asian markets see rapid adoption led by Zhejiang Junquan Automation and Kodera Electronics, satisfying immense domestic demand for consumer electronics and industrial automation cabling.
Strategic Positioning of Leading Industry Players
Market leaders utilize distinct competitive moats. Artos Engineering Company and Eubanks Engineering Company focus on robust, heavy-duty processing for industrial applications, whereas Mecal S.r.l. excels in high-precision crimping technology. These strategic positions allow firms to command strong margins in specialized application segments.
Porter's Five Forces Analysis of the Competitive Landscape
Porter's framework reveals moderate-to-high rivalry driven by continuous technological differentiation and software integration. Supplier power is constrained by specialized raw material availability for cutting blades, while buyer power remains balanced due to the high capital investment required for automated lines. Threat of substitution is low given the specialized mechanical precision needed for micro-wire processing.
SWOT Analysis of the Automatic Wire Processing Machines Market
Strengths include high machine repeatability and labor cost reduction. Weaknesses involve steep upfront hardware investments. Opportunities shine brightly within renewable energy grid infrastructure and medical harness manufacturing. Threats stem from macroeconomic currency volatility and geopolitical trade frictions affecting precision component supply chains.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material sourcing of high-grade alloy steels, tungsten, and electronic components. Mid-stream involves precision CNC machining, software development, and machine assembly by OEMs such as Schleuniger Group and Komax Holding AG. Downstream flow culminates in deployment across automotive harness plants, aerospace manufacturers, and renewable energy equipment builders.
Investment Insights and High-Potential Growth Pockets
Our analysis advises venture and strategic investors to target software-defined automation and integrated AI quality control systems. High-potential pockets exist in specialized processing machinery tailored for tinned copper wires used in offshore wind turbines and high-voltage electric vehicle architectures.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Automatic Wire Processing Machines Market represents a high-growth technological frontier essential for modern electrification. Reaching 3.44 Billion by 2033 at an 8.53% CAGR, the sector rewards firms that successfully merge mechanical precision with IoT connectivity and advanced machine vision.
Robust Research Methodology and Data Triangulation
Baseline estimates are synthesized through rigorous triangulation. We combine official customs trade registry data, primary executive interviews with CTOs of major machinery manufacturers, and secondary macroeconomic indicators assessing global automotive and electronics production outputs to ensure absolute market sizing accuracy.
Scope of the Report and Operational Parameters
This report covers global revenue performance, volume shipments, and technological evaluations across all specified machinery types and end-user verticals from 2026 through 2033. Limitations exclude unverified aftermarket modifications and custom artisanal tooling not produced at an industrial manufacturing scale.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum features aggressive R&D investments by market leaders launching AI-driven wire sorting and error-detection modules. Strategic partnerships between European automation specialists and Asian electronics suppliers continue to expand global distribution footprints, drastically reducing lead times for fully automatic crimping lines.